
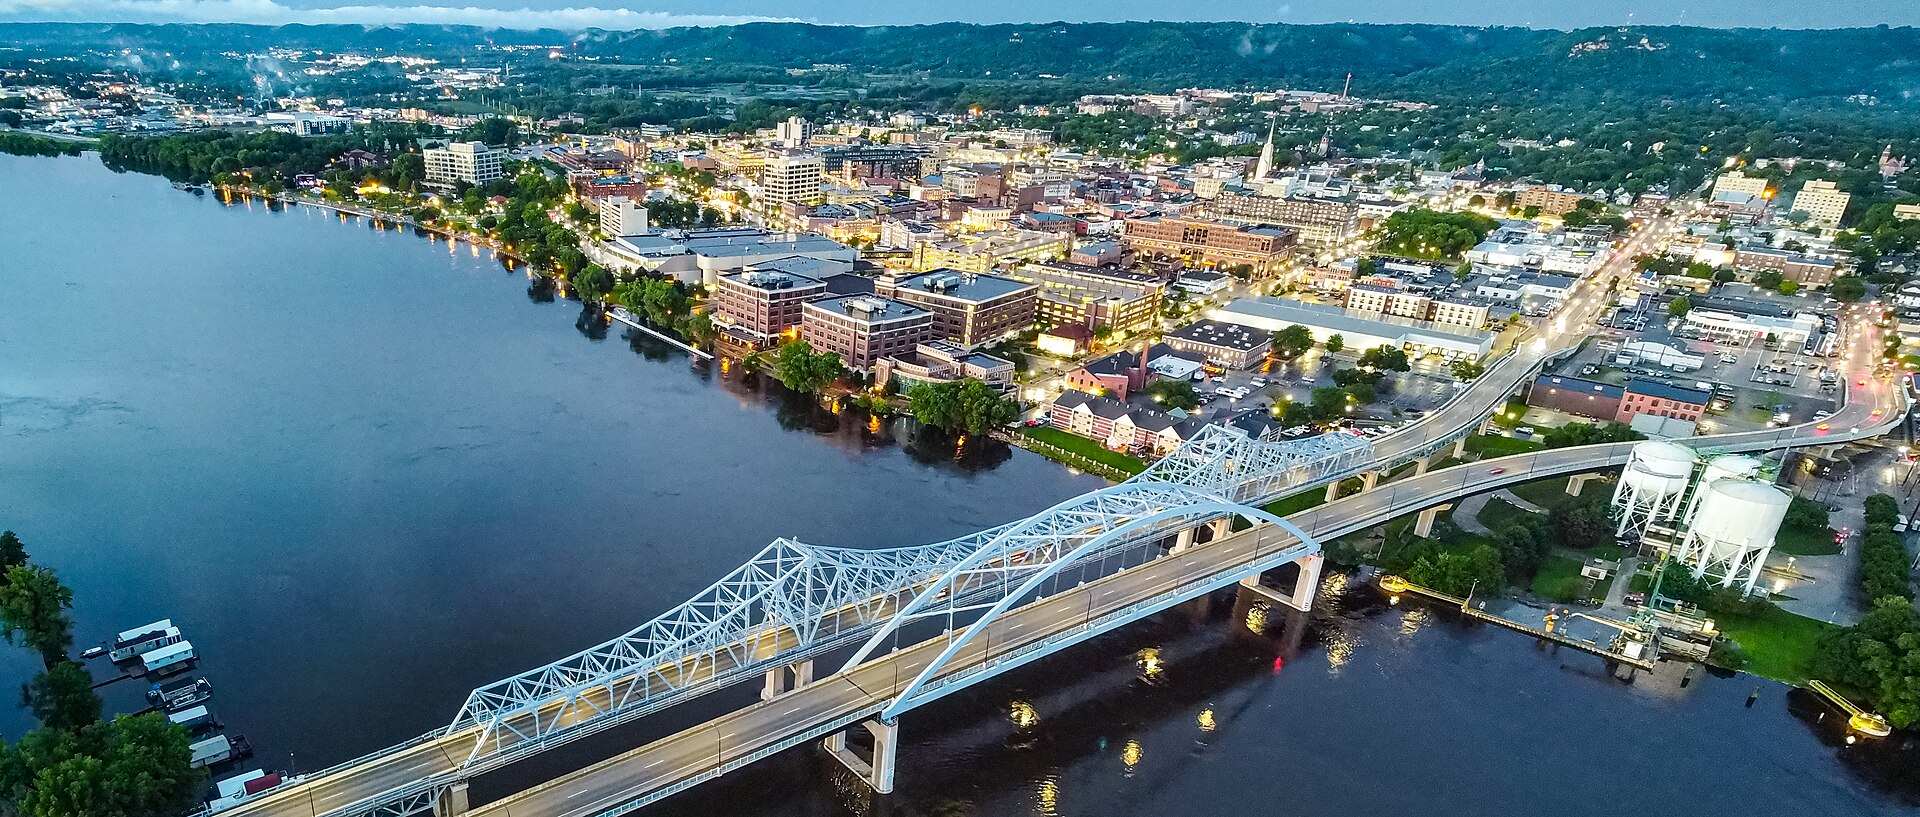
Sell My House Fast in La Crosse, WI We Buy Houses in La Crosse, WI
For “sell my house fast in La Crosse, WI,” call or submit your address today. We buy houses in La Crosse, WI as-is: review a written cash offer, then arrange title review and an available closing date if you accept.
The 5–10-minute offer window applies when enough property information is available. Final price and terms follow property review; closing depends on signing authority, title requirements and scheduling.
Tell us about the property and your preferred timing.
Requesting an offer does not commit you to selling. Review the written agreement before deciding.
La Crosse market watch • September 2026 snapshot
A Fast Retail Market Still Calls for a Property-Specific Decision
The supplied Redfin La Crosse city report covers the three months ending September 2026; its chart is labeled September. The separate competitiveness panel reports about 13 days to go pending. That is a different measure from the 9-day median and neither tells you when a seller receives proceeds.
A well-prepared house may benefit from retail exposure. If your property needs basement work, older-home repairs or ownership documents, compare the likely preparation and closing requirements with a written as-is offer. The city median is not an appraisal of your home.
Research snapshot: October 23, 2026. City of La Crosse, Wisconsin; all home types combined. Figures are not a promise of your price or sale time.
Our purchase policy
Sell It Exactly as It Sits in La Crosse
We buy houses in La Crosse, WI in their present condition. Before paying for cosmetic work, consider the larger scope: the city’s 2024 comprehensive plan identifies roofing, siding, window and electrical repair needs in older houses. A fresh coat of paint may leave those decisions unresolved. Read our guide to selling a house as-is before choosing a preparation budget.
We still coordinate access for property review. Put leave-behind arrangements in writing and share known defects and reports. Most covered pre-1978 sales retain federal lead-disclosure requirements even when sold as-is.
Housing context that changes the next step
Selling a House in La Crosse’s Neighborhoods
The city’s comprehensive plan reports that 26.7% of housing units were built before 1940 using its 2020 baseline. That dated planning figure helps explain why repair scope matters; it does not establish a defect at your address. The neighborhood plans below describe different housing and upkeep questions.
| Neighborhood / District | Housing Profile | Common Challenges We Resolve | Seller Scenario |
|---|---|---|---|
| Powell-Poage-Hamilton | Small wooden houses, often one story. The 2013 plan, under the former Powell-Hood-Hamilton name, describes a substantial pre-1900 component. | Evaluate a purchase with rehabilitation still needed, using the actual condition rather than assuming the plan proves a structural problem. | An owner could compare rehabilitation with an as-is exit from an older house or occupied rental. |
| Washburn | Older single-family houses, duplexes, triplexes and rental conversions; the 2002 plan documents a pre-1925 component using older Census data. | Assess current maintenance and conversion records. Historical upkeep complaints do not establish today’s condition or lawful unit count. | A landlord could compare completing updates with transferring the property on agreed as-is terms. |
| Grandview Emerson | Single-family and multifamily housing near UW–La Crosse, with historic character addressed in the 2006 plan. | Consider existing-house and rental upkeep alongside alteration records; the plan identifies character and compatibility concerns, not universal structural failure. | A rental owner could compare continued upkeep and turnover with a direct purchase. |
Seller scenarios are examples inferred from the documented housing context, not measured neighborhood cash-sale behavior. For actual approvals or notices, contact La Crosse Building & Inspections.
Look beyond the finishes
Older Paint, Basement Water and Repair Decisions in La Crosse
Pre-1978 painted surfaces: confirm what is present
In houses with remaining lead-based coatings, deterioration and friction at painted windows, doors and trim can produce contaminated chips and dust. Peeling, chipping, chalking and worn painted surfaces are reasons to investigate; appearance alone cannot identify lead. The EPA’s inspection and risk-assessment guidance explains the distinction.
La Crosse’s 2024 Housing Study documents substantial older housing stock. That makes an era-specific records check useful, without assuming every older home has a current hazard. Known findings may change a buyer’s repair allowance or negotiations. For most covered pre-1978 transfers, disclose known information and reports, supply the federal pamphlet and provide the required inspection opportunity under EPA disclosure rules.
Flood-exposed basements: investigate the parcel and the cause
The 2022 Flood Hazard Mitigation Plan documents North Side floodplain exposure and local basement flooding and groundwater observations. This is a localized concern, not a diagnosis for every North Side home. On exposed sites, river flooding or elevated groundwater can push water through existing cracks and put hydrostatic pressure on basement walls and floors, mechanisms explained in FEMA’s residential retrofit guidance.
Water at wall-floor joints, high-water marks or repeatedly damaged basement finishes call for an inspection that establishes the cause and extent. Flood history and mapped status can affect negotiations, rehabilitation feasibility and lender flood-insurance requirements. The city’s floodplain guidance uses a 50% substantial-improvement/damage threshold based on building value excluding land; reaching the applicable threshold can require current floodplain compliance. Check with the city before assuming a cosmetic basement allowance covers the project.
Roof condition, vacancy and insurance belong in the decision
Wisconsin’s Office of the Commissioner of Insurance identifies worn-out or leaky roofs as possible nonrenewal concerns and explains that vacancy beyond 60 days can affect cancellation or coverage. Ask your insurer about your actual policy before leaving an inherited house empty while deciding how to sell.
The state homeowners-insurance guide explains that ordinary homeowners coverage generally excludes flood and identifies the Wisconsin Insurance Plan as a last-resort option when ordinary coverage cannot be obtained. These issues can complicate a buyer’s insurance or mortgage review; they do not automatically make a house uninsurable or a sale impossible. Compare a specialist repair plan with an offer based on the documented condition. Our water-damage selling guide offers a broader starting point.
Interactive planning tool
AS-IS Repair Cost Estimator
Use a broad planning range to compare preparation with an as-is offer. These are disclosed illustrative assumptions, not measured La Crosse contractor prices, an inspection, appraisal, contractor quote or guarantee. Interior rates cover finishes only; add other work only when it falls outside that scope.
U.S. dollars. Enter 0–20,000 square feet. Optional allowances below are additional planning assumptions.
Actual scope, materials, labor, permitting, access and concealed damage can change costs substantially. Permits, structural rehabilitation, lead-safe work, floodplain compliance and major groundwater remediation are excluded and need separate review. La Crosse’s substantial-improvement rules can change a floodplain project beyond these allowances. The result is not an automatic deduction from an MHIC offer.
Compare the amount you keep and the terms
Cash Sale vs. Traditional Listing in La Crosse
A traditional sale may produce a higher gross price, but commissions, seller closing costs, repairs, concessions and ongoing holding expenses reduce the amount you ultimately keep. A direct cash sale generally prioritizes speed, certainty and convenience rather than the highest possible gross price.
La Crosse’s reported 9-day median market time is a reason to consider a listing when the house is ready; it does not include every title or closing step. Compare cash buyers for houses in La Crosse, WI using the same known condition, projected payoffs and available dates.
| Dimension | Traditional listing | Direct cash sale |
|---|---|---|
| Gross Price | Potentially higher gross price | Usually lower than full retail value |
| Commissions | Agent commission may apply | No agent commission |
| Closing Costs | Seller closing costs may apply | MHIC pays normal closing costs |
| Property Condition | Repairs or buyer credits may be requested | Property sold as-is |
| Contingencies | Financing and appraisal contingencies | No buyer-financing contingency |
| Timeline | Longer and less predictable timeline | Seller selects an available closing date |
Compare Your Estimated Selling Options
Use our adjustable calculator to compare a traditional listing with a direct cash sale using your property’s estimated value and expenses.
Use the Net-Proceeds Calculator →The listing column describes common terms; an individual offer can differ. A cash purchase can still involve condition and title review. MHIC’s cost commitment belongs in the signed contract; mortgages, taxes, recorded claims and negotiated exceptions can reduce seller proceeds. Learn how cash offers are calculated.
Resolve authority and deadlines early
Probate, Foreclosure Deadlines, and Complicated Title Situations in La Crosse
Inherited property: a $50,000 limit is a gross-estate test
The La Crosse County Circuit Court handles probate matters through the Register in Probate. Its Register in Probate contact page lists La Crosse County Courthouse, Room 1201, 333 Vine Street, La Crosse, Wisconsin. Confirm the appropriate procedure and documents before committing to a closing date.
Wisconsin’s transfer by affidavit under § 867.03 can apply when all of the decedent’s property subject to administration in Wisconsin at death totals no more than $50,000 gross. This is not a per-house or mortgage-equity limit. Qualifying real property can be included by recording in every Wisconsin county containing the affected property. This affidavit procedure is distinct from court-based summary settlement or summary assignment.
- Capacity matters. An heir, qualifying trustee of the decedent’s revocable trust or guardian serving at death may qualify. Being named personal representative in a will, by itself, does not permit that person to take real property through this affidavit.
- Real-property notice matters. Heirs generally receive the affidavit and recording notice at least 30 days before recording. The State Bar instructions recognize earlier recording if all heirs waive notice. There is no universal § 867.03 wait measured from the date of death; a separate 30-day custodian-receipt wait applies to certain non-real-property transfers by a will-nominated representative.
- The paperwork is substantive. This is generally an out-of-court sworn affidavit, with real-property recording, notice proofs and applicable Department of Health Services notice documentation. Payment priorities and estate-recovery obligations remain relevant. Specified competing affidavits can require a court order, and later estate administration remains possible.
The statute does not set a separate Wisconsin-residency requirement for the decedent or affiant; it addresses property subject to administration here. Meeting the dollar threshold alone does not establish authority to sell. Ask the Register in Probate and a Wisconsin estate attorney which route fits the estate. Our inherited-house guide explains general sale considerations.
Mortgage foreclosure: use the case documents to establish timing
Wisconsin uses judicial mortgage foreclosure in circuit court, followed by a court-authorized sheriff or referee sale. A summons and complaint starts the action, and a lis pendens records notice of the property lawsuit. A direct purchase may be one option if the owner has authority and enough time to complete the sale and required payoffs before the scheduled foreclosure sale.
Which notice periods and postjudgment waits can apply?
- For covered residential servicing, federal pre-foreclosure rules generally require more than 120 days of delinquency before the first notice or filing. Due-on-sale and lienholder-joinder exceptions apply, and loss-mitigation restrictions may add time.
- The ordinary Wisconsin answer deadline is 20 days after service; exceptions and publication service can change it. Under § 846.01(2), judgment cannot be entered until at least 20 days after filing the lis pendens.
- For covered owner-occupied one-to-four-family mortgages executed on or after April 27, 2016, the general judgment-to-sale waits are six months under § 846.10 or three months in qualifying deficiency-waiver cases under § 846.101. A qualifying pre-judgment motion based on a good-faith broker listing can extend those to eight or five months. For older mortgages, corresponding general waits are twelve or six months.
- Judicially determined abandoned premises can be sold after five weeks under § 846.102; stipulated earlier-sale and other exceptions exist. These are postjudgment rules, not a single default-to-sale countdown. See Wisconsin Chapter 846.
- For an in-person sale, § 815.31 requires public/website posting at least three weeks beforehand and newspaper publication weekly for three successive weeks, subject to the court’s authorized directions under § 846.16. Parties who appeared must receive at least five days’ notice of confirmation under § 846.165.
For installment-default cases within § 846.05, paying due principal, interest and costs before judgment requires dismissal; after judgment it stays proceedings subject to later default. Full redemption under § 846.13 requires the judgment amount, interest, costs and qualifying tax advances. An arrears-only cure of an accelerated loan requires review of the loan and applicable law.
Wisconsin’s redemption right can continue after auction until judicial confirmation; the § 846.13 annotations cite State Bank v. Sechen. Full payoff is required. There is no fixed additional borrower redemption period after confirmation, when § 846.16(2m)(as) bars the parties’ equity of redemption. A post-auction possibility should be reviewed immediately with counsel; do not assume it creates time for an ordinary voluntary sale.
The La Crosse County Sheriff’s sale page identifies the center hallway of the Courthouse and Law Enforcement Center, 333 Vine Street, with sales published for Tuesdays, Wednesdays and Thursdays at 10:00 a.m. The individual sale notice controls.
Back taxes, ownership questions and recorded claims
The City Treasurer’s tax schedule permits full payment by January 31 or installments on January 31, March 31, May 31 and July 31. From August 1, delinquent real-estate payments go to the County Treasurer at 212 6th Street North, La Crosse, WI 54601.
Wis. Stat. §§ 74.12 and 74.47 explain installment delinquency: insufficient payments can make the whole unpaid annual balance delinquent as of February 1, April 1, June 1 or August 1, with a five-working-day receipt rule. Delinquency charges run from the preceding February 1. County Code § 4.05 adds a 0.5% monthly or partial-month penalty to statutory 1% interest: 1.5% combined per month or fraction. Request an actual payoff rather than multiplying an old bill by elapsed months.
The La Crosse County Register of Deeds records instruments affecting title. A selected local settlement agent reviews recorded ownership, estate documents and payoffs, while the city handles actual code or permit questions. Bring heirship documents, tax statements and any municipal enforcement notice early. A purchase does not itself resolve an ownership dispute, erase a lien or cancel a code notice.
My House Into Cash provides direct purchasing solutions, not legal, tax, probate, foreclosure-defense or financial advice. Consult the court clerk, appropriate tax collector, Wisconsin real estate attorney, tax professional or other qualified adviser about your circumstances. We cannot guarantee foreclosure prevention, court approval, lien removal, tax forgiveness or title clearance.
From accepted offer to seller proceeds
What Happens Between Accepting Your Cash Offer and Getting Paid in La Crosse?
The schedule below illustrates a ready transaction, not a five-day promise. Probate authority, disputed ownership, payoff responses, title requirements and recording availability can extend it. In particular, an applicable estate notice period cannot be skipped to fit a marketing timeline.
-
Day 0: Finalize the purchase agreement
Put the price, property condition, access, items left behind, possession date and available closing date in writing. A direct MHIC purchase has zero MHIC fees and zero agent commissions; MHIC pays normal closing costs under the written terms. Seller debts and negotiated exceptions still affect proceeds.
The Wisconsin WB-11 contract illustrates negotiable cost allocation and seller-selected closing location unless otherwise agreed. The actual signed agreement governs your transaction.
-
Days 1–2: Search title and gather municipal records
The county provides Monarch, Laredo and Tapestry land-record access. The settlement agent establishes the parcel’s search scope and title-commitment requirements. Local provider River Valley Title Group documents tax, judgment, UCC and easement searches and title commitments.
The county’s title-company directory lists Knight Barry Title at 500 2nd Street South, Suite 102, La Crosse, WI 54601 as one local option; an MHIC partnership is not established. Ask the selected agent about its actual search. Send permit or maintenance notices to Building & Inspections for address-specific clarification.
-
Days 2–4: Obtain payoffs and address title requirements
Request current mortgage, tax and other recorded-claim payoffs. Town n’ Country Title’s payoff guidance describes using written payoff instructions for existing mortgages and liens. County tax interest and penalties make the effective payoff date important. Heirship disputes, releases or other curative requirements can require additional documents or legal work; closure is not assured merely because an offer is accepted.
-
Day 5, if ready: Sign, record and receive proceeds
The deed follows the contract and seller’s capacity. WB-11 ordinarily calls for a warranty deed from a private seller, a trustee’s deed from a trust or a personal representative’s deed from an estate, unless another conveyance is agreed.
Under Wisconsin deed-execution law, the grantor signs; both spouses generally must sign a married person’s homestead conveyance, including a spouse absent from title, subject to statutory exceptions. An ordinary deed does not require separate witnesses, but recording requires notarial acknowledgment or another authorized authentication. The DFI notary handbook encourages an ordinary notarial journal and specifies no thumbprint step; remote procedures require separate review.
The deed is submitted to the La Crosse County Register of Deeds. A bank wire is a documented Wisconsin seller-proceeds method; confirm check availability, release timing and banking cutoffs with your selected settlement agent. Signing alone does not establish immediate receipt.
Coordinate utilities separately from title work. Xcel Energy’s Wisconsin guide lists La Crosse for electric service; confirm the provider and account-transfer arrangements for the address.
La Crosse and the surrounding region
Explore the 75-Mile La Crosse Reference Area
The 75-mile circle below uses straight-line distances from La Crosse’s Census representative point, 43.824685, -91.224616. Road travel can be longer. The named municipalities fall within that circle, but geography does not confirm purchasing availability at every address or across state lines. Send the property address to check coverage.
Blue: Wisconsin • Green: Minnesota • Orange: La Crosse. The circle is a geographic reference, not a coverage guarantee.
75-mile overview centered on La Crosse. Select a community to move the Google map and highlight its position in the radius plot.
Coordinates: U.S. Census Bureau 2025 Gazetteer files for Wisconsin places and Minnesota places. The radius plot and Google map are linked views; the circle is not an overlay on Google Maps. The Wisconsin probate, foreclosure and tax information on this page applies to Wisconsin property.
See our Wisconsin home-buying page for the statewide service overview.
Understand the documents before choosing a date
La Crosse Real Estate & Legal Terms Homeowners Should Know
- Register in Probate
- The circuit-court probate office that administers local probate filings; contacting it helps determine the appropriate estate procedure and required documents before selling inherited property. Source ↗
- Transfer by affidavit (§ 867.03)
- A Wisconsin transfer procedure for no more than $50,000 in gross Wisconsin probate property. Qualifying real-property transfers require recording and heir notice; the gross limit prevents treating mortgage equity alone as the eligibility test. Source ↗
- Lis pendens
- Recorded notice that a lawsuit concerns the property. A pending foreclosure notice must be addressed in a sale’s title and payoff work; it is not a completed foreclosure or deed transfer. Source ↗
- Redemption before confirmation
- For a Wisconsin mortgage foreclosure, full redemption can remain available until the court confirms the sheriff’s sale. An owner must distinguish the auction date from the confirmation deadline. Source ↗
- 50% substantial-improvement/damage rule
- La Crosse’s published floodplain guidance uses building value excluding land to evaluate substantial work or damage against its 50% threshold. Reaching the applicable threshold can require bringing the building into current floodplain compliance and materially change a rehabilitation budget. Source ↗
- Delinquent-tax interest and penalty
- County Code § 4.05 adds a 0.5% monthly or partial-month penalty to the statutory 1% interest. Under the city’s installment framework, later delinquency can result in charges running from the preceding February 1. Source ↗
Practical answers for La Crosse sellers
Frequently Asked Questions
Which residential ZIP codes are in La Crosse and the surrounding communities?
La Crosse’s standard residential ZIP codes are 54601 and 54603. The table includes every standard ZIP for the named postal areas, including all 18 municipalities in the regional list above and additional nearby rural postal areas. ZIP boundaries are not municipal boundaries or proof of purchasing coverage. Minnesota addresses require separate coverage confirmation.
| Community / postal area | Residential ZIP codes |
|---|---|
| La Crosse, WI | 54601, 54603 |
| Arcadia, WI | 54612 |
| Bangor, WI | 54614 |
| Black River Falls, WI | 54615 |
| Cashton, WI | 54619 |
| Chaseburg, WI | 54621 |
| Coon Valley, WI | 54623 |
| De Soto, WI | 54624 |
| Ettrick, WI | 54627 |
| Galesville, WI | 54630 |
| Genoa, WI | 54632 |
| Holmen, WI | 54636 |
| La Farge, WI | 54639 |
| Melrose, WI | 54642 |
| Mindoro, WI | 54644 |
| Norwalk, WI | 54648 |
| Onalaska, WI | 54650 |
| Ontario, WI | 54651 |
| Readstown, WI | 54652 |
| Rockland, WI | 54653 |
| Sparta, WI | 54656 |
| Stoddard, WI | 54658 |
| Tomah, WI | 54660 |
| Trempealeau, WI | 54661 |
| Viroqua, WI | 54665 |
| Westby, WI | 54667 |
| West Salem, WI | 54669 |
| Wilton, WI | 54670 |
| Brownsville, MN | 55919 |
| Caledonia, MN | 55921 |
| Eitzen, MN | 55931 |
| Hokah, MN | 55941 |
| Houston, MN | 55943 |
| La Crescent, MN | 55947 |
| Minnesota City, MN | 55959 |
| Rochester, MN | 55901, 55902, 55904, 55906 |
| Spring Grove, MN | 55974 |
| Winona, MN | 55987 |
Source: USPS October 2026 ZIP Locale Detail file, with standard ZIP classes retained. PO-box-only codes, including La Crosse 54602, Sparta 54620 and Rochester 55903, are excluded. This is a comprehensive list for the named postal areas, not an inventory of every postal route touching the 75-mile circle. Check a full address with USPS ZIP Code Lookup; an unlisted mailing address can still be submitted for review.
How do I sell my house for cash in La Crosse, WI?
Call or use the offer form with your address, known condition and preferred timing. Review the written offer and proposed terms, then coordinate an available closing date after ownership and title review. Share flood reports, estate paperwork or city notices early so the proposed plan accounts for the actual property.
How fast can a La Crosse cash sale close?
If you are comparing “sell house fast in La Crosse, WI” options, ask for dates tied to your title and ownership documents. An initial offer may be available in 5–10 minutes when enough information is available. The five-day sequence above is an illustrative ready-file schedule, not a guaranteed completion date. Estate notices, payoffs and unresolved title requirements can take longer.
Can I sell my La Crosse house as-is?
Yes, MHIC can evaluate the present condition without requiring you to complete the preparation checklist above. Share known defects and reports. Covered pre-1978 transfers generally still require known lead information, available reports, the federal pamphlet and an inspection opportunity; an as-is agreement does not eliminate those steps. EPA disclosure guidance explains the requirements.
Can transfer by affidavit be used for an inherited La Crosse house?
Potentially. Wisconsin § 867.03 can include real property when all qualifying Wisconsin probate property is no more than $50,000 gross, with recording, eligible capacity and applicable notice requirements. The threshold is not net equity. A person acting solely as a will-nominated representative cannot use it to take real property. Confirm the route and sale authority with the Register in Probate and an attorney. Read Chapter 867.
Can I sell before a La Crosse sheriff’s sale?
A direct sale may be possible when the owner has authority and enough time to close and satisfy required payoffs before the scheduled sale. A request or purchase agreement does not stop the case. Wisconsin has judicial foreclosure and case-specific waiting and notice rules; ask your servicer and attorney to review the actual documents immediately. The Sheriff’s individual sale notice controls the scheduled sale.
Does basement water prove that my home is in a floodplain?
No. A wet basement alone does not establish mapped floodplain status or the cause of water entry. La Crosse’s flood plan documents localized river and groundwater exposure, including North Side concerns. Check the parcel’s mapped status and have the water mechanism assessed before estimating repairs. The city’s floodplain resources can help with the mapping and substantial-improvement question.
How should I compare cash home buyers in La Crosse, WI?
Compare the named purchaser, written price, condition review, cancellation terms, closing-cost allocation and proposed date. For a floodplain house, ask whether the offer accounts for the city’s substantial-improvement rules. For inherited property, establish who can sign. Use the same repair and payoff assumptions when comparing offers with a listing, and ask what could change the price before committing.
Will the cash offer equal the amount I receive?
Your proceeds can be lower after mortgage balances, property taxes, recorded claims and negotiated adjustments. MHIC pays normal closing costs under the written agreement, but that does not forgive seller debts. La Crosse County’s combined delinquent-tax interest and penalty is 1.5% per month or fraction, so request a current payoff and settlement estimate. County Code § 4.05 explains the county penalty.
Can I request an offer for a rental or a house with unfinished alterations?
Yes. Share the occupancy, access arrangements, work history and any notices. Washburn and Grandview Emerson plans document rental and multifamily housing alongside upkeep concerns, but those plans do not establish a particular unit’s approval status. Contact Building & Inspections about actual permit or code records; an as-is purchase does not itself approve an alteration.
Request a Written Offer for Your La Crosse House
Start with the address, known condition and preferred timing. If basement water, an estate document or a city notice affects the plan, include it early so the offer and proposed date reflect the actual property.
Use the Cash Offer Form ↑ Call (866) 651-6617
No obligation to accept. Final terms follow property review, ownership authority and title requirements.
Primary sources
Official La Crosse Homeowner Resources
Use the appropriate office to confirm your parcel, balance, estate procedure or permit question. The city’s floodplain rules and county recording and tax records can materially change a sale plan.
- La Crosse County Clerk of Circuit Court ↗
- City of La Crosse — Assessor ↗
- La Crosse County Treasurer — Amy L. Twitchell ↗
- City of La Crosse Treasurer — Real Estate Property Tax ↗
- City of La Crosse — Building, Permitting and Code Enforcement ↗
- La Crosse County Register of Deeds ↗
- City of La Crosse — Floodplain Management and Local Flood-Map Resources ↗
- Wisconsin Legislature — Wis. Stat. ch. 846, Real Estate Foreclosure; certified update October 1, 2026 ↗
- Wisconsin Legislature — Wis. Stat. § 867.03, Transfer by Affidavit; certified update October 1, 2026 ↗
- Xcel Energy — Wisconsin Service Guide, Communities Served ↗