
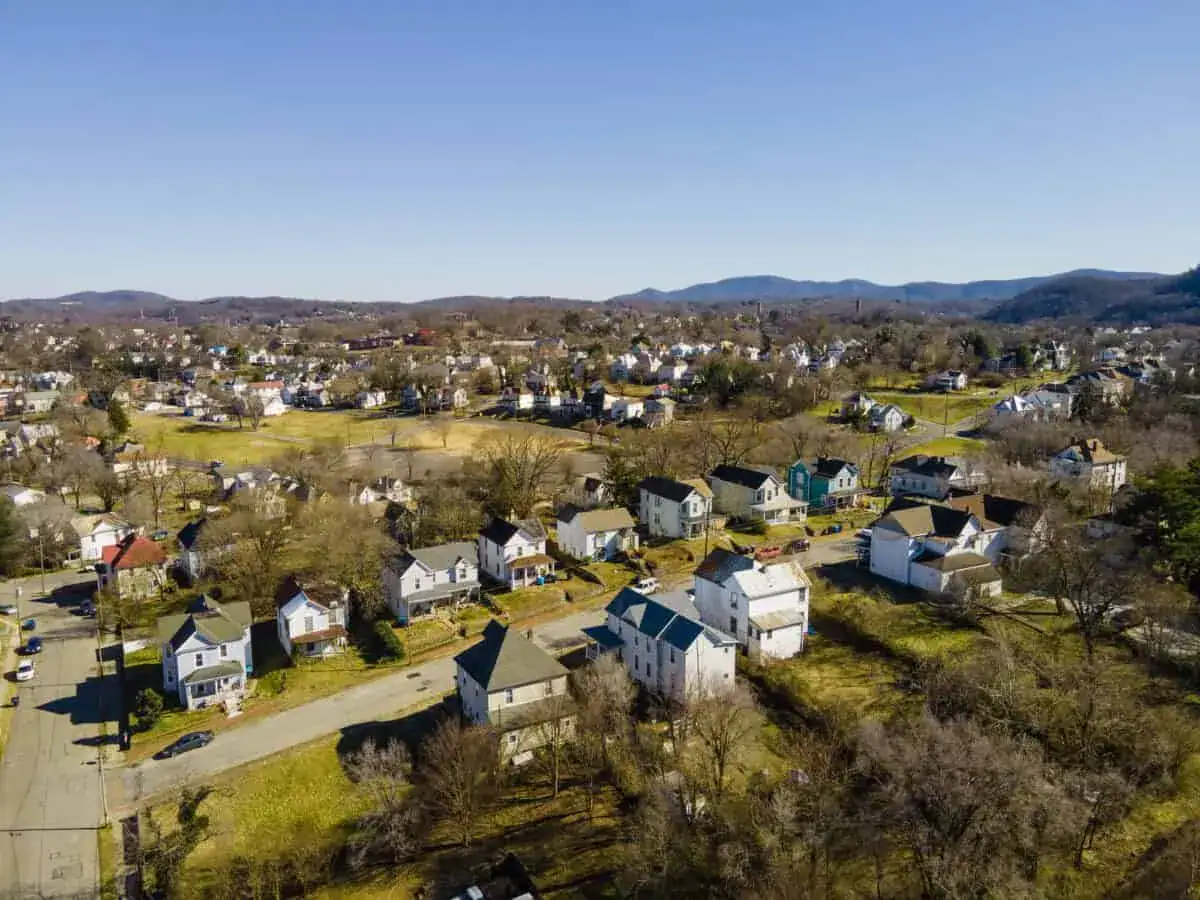
Sell My House Fast in Roanoke, VA — We Buy Houses for Cash
To sell your house fast in Roanoke, VA, call (866) 651-6617 or share your property details today. We buy houses in Roanoke as-is and provide a written cash offer after review. Accept if it fits, then choose an available closing date.
A direct sale without a renovation project, listing preparation or agent commissions.
Get Your Roanoke Cash Offer
Tell us about the house and when you would like to sell.
Initial offer timing depends on the information available. Your written agreement confirms the price, costs and closing conditions.
A practical alternative to listing
Can I Sell My House Fast in Roanoke Without Making Repairs?
Yes. My House Into Cash reviews the house in its current condition and makes a direct cash offer you can compare with a listing. If you want to sell your Roanoke house as-is, start with the address, known repairs and your preferred timing. Our buying process explains what to expect.
First, confirm the parcel’s jurisdiction. Roanoke is an independent city, separate from Roanoke County. A Roanoke mailing address alone does not tell you which land records, tax office or probate office applies. The city-specific guidance below is for City of Roanoke parcels.
Roanoke Market Watch
City of Roanoke, all home types; three months ending September 2026. Retrieved October 23, 2026. Source: Redfin’s Roanoke market report. The score uses a three-month window. Days on market exclude the additional time needed to close and receive proceeds.
A listing may make sense when the house is ready and you can allow time for marketing and closing. For a repair-heavy property, compare the likely work, negotiated credits and carrying expenses with the written cash offer; the citywide median is not an appraisal of your house.
Our as-is purchase policy
Sell It Exactly as It Sits in Roanoke
That choice matters in Roanoke’s older housing. For a parcel in a local H-2 historic district, covered exterior changes can require approval; the city distinguishes alterations from ordinary in-kind repair. Before replacing original features solely to prepare a sale, compare an as-is offer with the work and approval path.
Selling as-is does not waive applicable disclosures or resolve ownership, title or legal obligations. See our as-is selling guide .
Understand the property before choosing a sale route
We Buy Houses in Roanoke, VA, With Older-Home Repair Needs
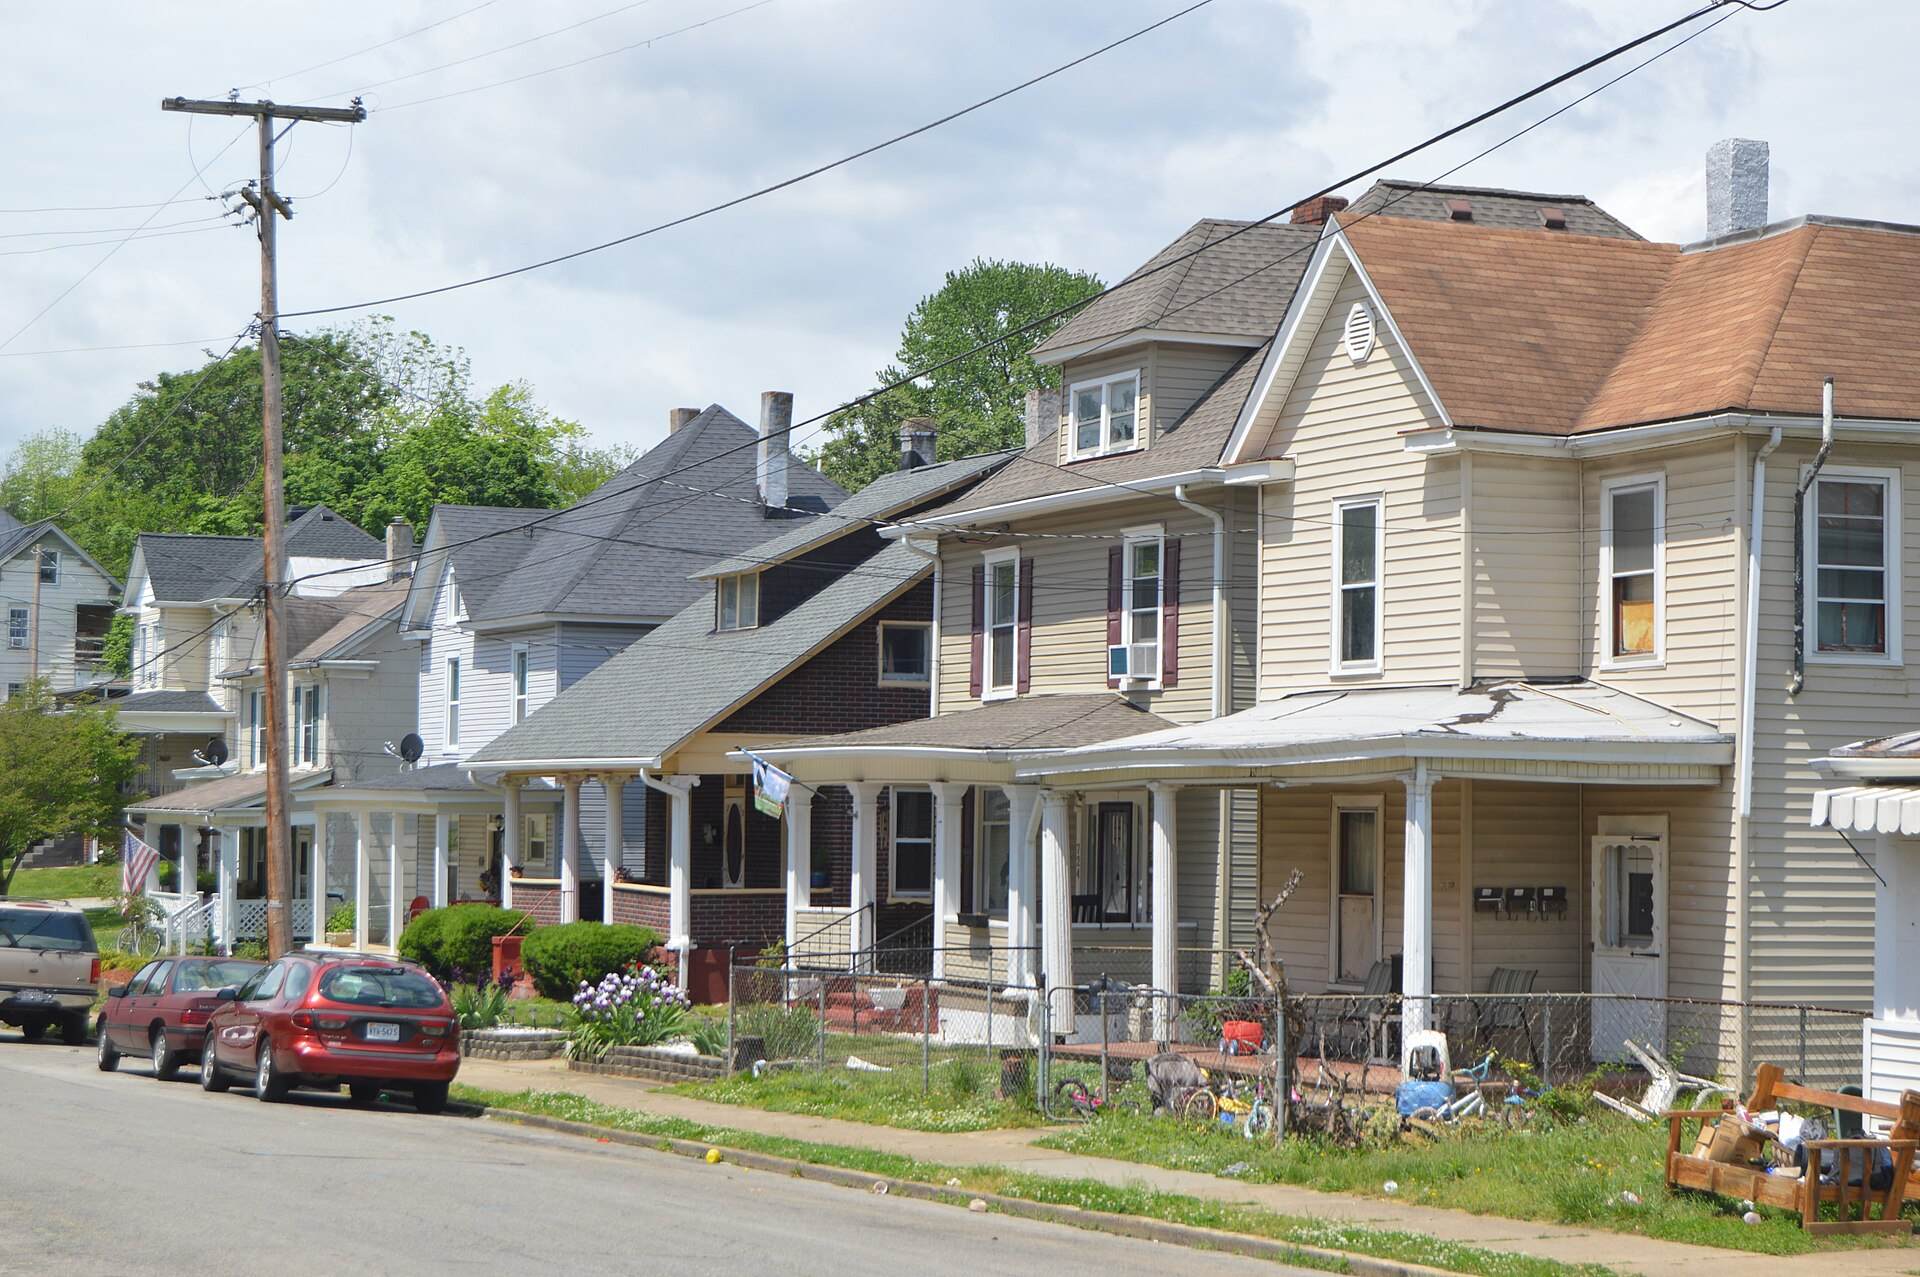
The city’s Residential Pattern Book describes downtown neighborhoods from the 1880s–1920s, traditional neighborhoods from the 1920s–1940s and suburban development from the 1940s onward. Those eras guide what to inspect; they do not establish a defect or a citywide median house age.
Basement moisture: follow the water
In older houses with brick or stone foundation walls, overflowing gutters, short downspouts and grading toward the house can concentrate water beside porous masonry. Capillary action can carry moisture into the wall. Look for wet floors, white mineral deposits, loose mortar, staining or mildew.
The city’s maintenance guidance documents these mechanisms. This is a condition-related regional tendency, not a diagnosis of every Roanoke basement. A practical selling implication is that visible moisture may prompt investigation or a repair allowance. Compare an evaluated repair plan with an offer that accounts for the condition.
Pre-1978 paint: appearance is not a test
Deteriorating painted windows, doors and trim can produce chips and dust; renovation can disturb remaining lead-based coatings. Peeling paint alone cannot establish whether lead is present. Lead Safe Roanoke documents the local relevance without establishing a citywide contamination rate.
For most covered pre-1978 sales, federal rules require known lead information, available reports, the warning and pamphlet, plus a normally ten-day inspection opportunity unless lawfully modified or waived. A cash sale does not remove those requirements.
Flood exposure is parcel-specific
The city documents river and tributary overflow, intense-rain drainage flooding and rapid flooding associated with mountainous terrain. Check the actual parcel near the Roanoke River, Peters Creek, Tinker Creek or Lick Run through the city GIS FEMA layers and Flooding tab.
Roanoke’s flood guidance explains that a Special Flood Hazard Area can trigger insurance requirements for federally backed mortgages. Share known water events and reports so a buyer can evaluate the property accurately.
Check materials, permits and occupancy
Local guidance documents wood framing, wood siding and masonry, including brick-veneer ranch houses with basements or slabs and bungalows with wood, stone or stucco exteriors. Confirm the individual house’s systems rather than assigning a citywide material or foundation type.
For an addition or unfinished project, obtain permit and inspection history from the Permit Center. Code Enforcement can post stop-work orders for unpermitted construction; changing owners does not itself establish compliance.
Roof materials also need individual review. The city’s historic roof guidance addresses asphalt, slate, wood, metal and tile, including preservation of original materials. A visible roof issue may affect negotiations; no universal roof-age cutoff or automatic mortgage rejection is assumed here.
For a vacant house, check the policy before leaving it empty. The Virginia SCC homeowners insurance guide explains that repair needs can affect eligibility, vacancy can suspend portions of coverage and standard homeowners policies generally exclude flood. Carrier rules vary; ask the insurer about the actual condition and occupancy.
Owners considering continued ownership can also review Healthy Homes Roanoke, which addresses home hazards including indoor air quality and lead, with radon testing for funded homes. For rentals in the Rental Inspection District, the city’s code guide describes inspections at least once every four years. Compare the actual repair and compliance work with selling; these programs do not establish that every older home or rental has a problem.
Selling a House in Roanoke’s Neighborhoods
These documented housing patterns help frame a property review. The seller scenarios are examples of choices an owner might make, not measured neighborhood selling behavior.
| Neighborhood / District | Housing Profile | Common Challenges We Resolve | Seller Scenario |
|---|---|---|---|
| Old Southwest | Late-19th- and early-20th-century Queen Anne, Colonial Revival, American Foursquare and bungalow houses in the broader Southwest Historic District. | An as-is purchase can avoid pre-sale exterior work. For parcels in the local H-2 overlay, confirm the applicable approval path; historic designation does not establish a defect. | An inherited-home owner compares specialist restoration work with selling in current condition. |
| Wasena | Traditional neighborhood with Craftsman bungalows and other early-20th-century houses; the city identifies local bungalow examples. | Evaluate porch, roof and drainage components individually using the city’s maintenance checkpoints. No neighborhood defect rate is asserted. | An owner compares deferred-maintenance work with an offer that includes the current condition. |
| Belmont-Fallon | Part of the city’s 1880s–1920s downtown neighborhood cohort, with vernacular frame houses, front porches and narrow lots. | The municipal revitalization program identifies occupied- and vacant-home rehabilitation, minor repairs and enhanced code enforcement as priorities. Conditions vary by parcel. | An owner of a vacant house considers an as-is sale before organizing rehabilitation. |
AS-IS Repair Cost Estimator
Use this tool to organize a broad repair budget before comparing sale options. In Roanoke, the city’s masonry and drainage guidance makes an important distinction: a cosmetic finish allowance cannot diagnose the cause of a wet basement. Obtain a property-specific assessment when the scope is uncertain.
These are editable planning assumptions, not verified Roanoke contractor prices. The result is not an inspection, appraisal, contractor quote, cash offer or guarantee. Actual costs vary substantially with materials, labor, permitting, access, scope and concealed damage.
What is included in these assumptions?
Interior finish rates represent increasing allowances for surface and finish updates. They exclude all separately selected work. Add each separate allowance only once. The contingency applies to the combined low and high subtotal; the displayed range rounds outward to the nearest $500.
The model does not price structural engineering, foundation reconstruction, lead or other hazardous-material remediation, historic restoration premiums, major plumbing replacement, flood remediation, design fees or permit fees. An unchecked category is excluded, not a finding that it needs no work. Replace these assumptions with actual quotes before making a repair decision.
Cash Sale vs. Traditional Listing in Roanoke
A traditional sale may produce a higher gross price, but commissions, seller closing costs, repairs, concessions and ongoing holding expenses reduce the amount you ultimately keep. A direct cash sale generally prioritizes speed, certainty and convenience rather than the highest possible gross price.
Roanoke’s reported 23 days on market excludes closing time. When choosing cash buyers for houses in Roanoke, compare written terms with a realistic listing plan for your house’s condition, rather than treating that market statistic as a payment deadline.
| Selling Dimension | Traditional Listing | Direct Cash Sale With MHIC |
|---|---|---|
| Gross Price | Potentially higher gross price | Usually lower than full retail value |
| Commissions | Agent commission may apply | No agent commission |
| Closing Costs | Seller closing costs may apply | MHIC pays normal closing costs |
| Property Condition | Repairs or buyer credits may be requested | Property sold as-is |
| Contingencies | Financing and appraisal contingencies | No buyer-financing contingency |
| Timeline | Longer and less predictable timeline | Seller selects an available closing date |
Individual listing contracts and contingencies vary. MHIC’s cost allocation is confirmed in the purchase agreement. Existing mortgages, taxes, liens and other seller obligations are separate from normal closing costs; applicable amounts affect net proceeds.
Compare Your Estimated Selling Options
Use our adjustable calculator to compare a traditional listing with a direct cash sale using your property’s estimated value and expenses.
Use the Net-Proceeds Calculator →Probate, Foreclosure Deadlines, and Complicated Title Situations in Roanoke
Inherited houses: establish who can sign
The Circuit Court of the City of Roanoke — Office of the Clerk of Circuit Court, Estates Division is at 315 Church Avenue SW, 3rd Floor, Room 357, Roanoke, VA 24016 . Probate appointments are required. Contact the clerk for procedural questions and a Virginia attorney for legal interpretation and authority to convey the house.
Virginia’s Small Estate Act affidavit procedure applies to an entire personal probate estate worth no more than $75,000 at death, wherever located, after at least 60 days. Real estate is excluded. The threshold is not a house-equity limit, and the affidavit cannot transfer the home or automatically authorize a sale.
What other small-estate conditions matter?
No personal-representative appointment application may be pending, and no appointment may have been granted in any jurisdiction. Any will must already be probated. All known successors make the affidavit and designate the recipient successors, subject to applicable virtual-representation provisions. The asset holder receives the affidavit; § 64.2-601 does not require a separate distribution order.
The statute states no separate Virginia-resident petitioner requirement and no blanket debt-free-estate requirement. These personal-asset rules do not decide inherited real-estate title. Have counsel establish the correct sellers and any required estate proceedings before setting a closing date. See our inherited-house guide for the purchase process.
A trustee’s sale requires an actual deadline review
Virginia predominantly uses nonjudicial foreclosure under a deed-of-trust power of sale; judicial foreclosure is also available. The Western District of Virginia court-hosted guidance explains the framework. An ordinary power-of-sale foreclosure proceeds through a mailed and advertised notice of trustee’s sale, rather than requiring an initiating lawsuit. A substitute trustee’s appointment is recorded when used.
Under § 55.1-321, the sale-notice minimum is generally 60 days for owner-occupied residential deeds of trust and 14 days for other deeds of trust. These are notice periods, not the total time from the first missed payment to a sale. For covered mortgages, federal servicing rules generally restrict the first required foreclosure notice or filing until the loan is more than 120 days delinquent, subject to exceptions and other protections.
A voluntary off-market sale may be an option if the owner has authority to sell and enough time to complete the transaction before the scheduled sale. Send the actual notice to a qualified attorney and the settlement provider promptly. We cannot promise that a purchase will prevent foreclosure, that a trustee will postpone a sale or that a particular debt will be waived.
Notices, reinstatement, sale location and redemption
Owner mailing uses certified or registered mail; eligible recorded lienholders and associations receive statutory notice. Owner-occupied notices include housing-counseling and legal-aid contacts, the required non-eviction warning, payment information, arrears and remaining principal. Certain subordinate mortgage holders must also provide an affidavit/accounting and 60-day notice before requesting a sale, subject to exemptions. Review the complete notice statute with counsel.
Publication rules depend on the deed: minimum weekly publication for two weeks or daily publication on three days; if the deed is silent, weekly publication for four successive weeks, with a city exception allowing five different days. The sale follows final publication, at least eight days after the first advertisement and no more than 30 days after the last. Loan terms and applicable federal protections can add requirements.
No universal Virginia statutory post-acceleration reinstatement deadline is established by the court-hosted guidance. Check the actual loan documents and loan-program protections. Likewise, no verified Roanoke default-to-sale median is supplied here; calculate neither a guaranteed deadline nor a remaining window from these general periods.
A historical trustee notice documented a sale outside the courthouse’s main entrance at 315 Church Avenue SW. That February 27, 2020 example is not an upcoming auction. § 55.1-320 allows other qualifying venues; the current advertisement controls.
There is no general borrower statutory post-sale redemption period following a valid, completed Virginia trustee’s sale. In re Wolfe addressed an equity-of-redemption interest before completion of the sale memorandum. It does not create a fixed extra window after a completed sale. Obtain immediate legal advice about sale completion, bankruptcy or any asserted rights.
Title clouds: identify the recorded issue first
Heirship questions, recorded encumbrances, back taxes and code-related claims require individual review. The Office of the Clerk of Circuit Court of the City of Roanoke — Land Records/Deed Desk, at 315 Church Avenue SW, 3rd Floor, maintains city land records. The settlement provider can identify requirements for conveyance and obtain appropriate payoffs or releases; attorneys address disputed ownership or legal authority. A code notice is not automatically proof of a recorded lien.
MHIC provides direct purchasing solutions, not legal, tax, probate, foreclosure-defense or financial advice. Consult the court clerk about procedure, the City Treasurer about city tax balances, and an appropriate attorney or tax professional about your individual circumstances. A purchase offer does not guarantee court approval, title clearance, lien removal or tax forgiveness.
What Happens Between Accepting Your Cash Offer and Getting Paid in Roanoke?
The sequence below is an illustrative five-business-day workflow for a transaction ready to proceed, not a promised closing time. Ownership questions, payoff responses, estate matters, title requirements and recording readiness can extend it. The written contract establishes the actual date.
-
Day 0 · Mutual agreement and purchase contract
Confirm the purchase price, as-is condition, what may remain, possession date and available closing date. MHIC charges no seller service fee or agent commission and pays normal closing costs as agreed in writing. Existing property debts remain part of the settlement accounting.
Virginia permits a properly qualified attorney or eligible licensed title/settlement provider to act as settlement agent; an attorney is not required for every closing. The provider for your transaction must be confirmed. Virginia Title Center is a documented local provider, not a verified MHIC partner.
-
Days 1–2 · Title search and city due diligence
The settlement provider examines recorded conveyances and encumbrances in the city’s land records and consults probate records where inherited ownership is involved. Public-room searches and subscription remote access are available.
Confirm parcel details through Real Estate Valuation/GIS, tax balances with the Treasurer and permit/inspection history through the Permit Center and eTRAKiT. Agree on any additional code or municipal inquiry with the provider rather than assuming a standard search covers everything.
-
Days 2–4 · Payoffs and title requirements
Obtain mortgage payoffs, reconcile taxes and applicable association dues, and address commitment requirements and necessary releases. The local settlement-provider guide describes those checks. Disputed liens or unresolved heirship may need legal work beyond this example schedule.
Use the City Treasurer’s Office, 215 Church Avenue, Room 254, for a current city tax balance. Do not substitute an old bill for the amount due at closing.
-
Day 5, if ready · Deed signing, recording and payment
The contract determines the deed required. A Virginia general-warranty covenant protects against all persons’ title claims; other deed types may apply. Conveying owners or duly authorized representatives sign and ordinarily acknowledge signatures before a notary. An ordinarily acknowledged deed does not require extra attesting witnesses; statutory proof by two subscribing witnesses is an alternative.
The provider submits the deed and required barcode Virginia Land Records Cover Sheet to the city’s Land Records/Deed Desk. Proceeds may be sent by wire or settlement trust-account check after recording and clearance. Virginia law ordinarily requires recording before disbursement and recordation and disbursement within two business days of settlement, with narrow exceptions. Signing alone does not guarantee immediate bank availability.
Signing arrangements, identification and title coverage
Arrange an absent seller or proposed power of attorney in advance with the provider. The local provider’s closing guide describes scheduled notarized closings. It also distinguishes a lender’s title policy, generally required for a financed purchase, from separately elected owner’s coverage; cost allocation follows the contract.
Under § 47.1-14, the notary checks identity and keeps required records. Paper notarizations performed on or after July 1, 2026 require at least five years’ record retention; electronic-act records also have a five-year minimum. The statute’s record fields do not prescribe a deed thumbprint, although lawful additional procedures can vary. Ask in advance what identification and documents to bring.
Overdue city property taxes change the payoff
The city tax calendar lists October 5 and April 5 installments; follow the actual bill’s operative deadline. The FY2026–2027 fee compendium lists a 2% late penalty after the due date and an additional 8% starting on day 16. The reduced 2% result requires payment in full within the first 15 days; that period is not penalty-free. First-year interest is listed at 10% annually, approximately 0.833% monthly, on the outstanding balance. The source does not establish a separate later-year rate.
Request a current balance from the Treasurer, Tasha L. Burkett’s office. Real Estate Valuation appraises city property annually; the Treasurer collects tax. Keeping those roles separate helps direct payoff questions to the right office.
Appalachian Power, an AEP company, is the city’s identified primary electric utility; verify the individual service address. Coordinate account arrangements separately. No claim is made here that an ordinary electric bill is a title lien.
Roanoke and Nearby Communities Within a 75-Mile Radius
Explore the area around Roanoke, then send the property address to confirm purchase availability. The radius is measured in a straight line from the USGS Roanoke reference point at 37.2709704, −79.9414267; it is not a driving-distance or municipal-boundary limit.
Roanoke is the center of the 75-mile planning radius.
Open the selected community in Google Maps ↗Place reference points: 2025 Census Places Gazetteer. The locator shows relative direction and straight-line distance, with no road routes. Every listed place reference point is within 50 miles of Roanoke; exact property locations vary.
Looking elsewhere? Visit our Virginia home-buying page or the separate Lynchburg city page. City of Roanoke legal and tax details should not be applied automatically to those other jurisdictions.
Roanoke Home-Selling Questions, Answered
How can I sell my house for cash in Roanoke?
Send MHIC the property address, known condition and preferred timing, or call (866) 651-6617. Review the written offer and purchase terms, then agree on an available closing date. A settlement provider checks ownership, title and payoffs before the deed is recorded and proceeds are disbursed.
Can I sell my Roanoke house as-is with a wet basement or old paint?
Yes, MHIC considers houses in their current condition. Explain known water entry, paint reports and previous work so the offer can account for the property. The city documents drainage-related masonry moisture and pre-1978 lead hazards; neither can be diagnosed from a photograph alone. Applicable disclosures still apply to a cash sale.
What should I compare when choosing cash home buyers in Roanoke, VA?
Compare the written price, inspection terms, closing-cost allocation, possession arrangements and available date. Ask who will handle settlement and what title requirements remain. The estimated net amount and conditions matter more than a headline promise to sell a house fast in Roanoke, VA.
Can a small-estate affidavit authorize the sale of an inherited house?
No. Virginia’s small-estate affidavit covers qualifying personal probate assets; real estate is excluded. Its $75,000 limit and 60-day waiting period do not establish authority to sign a house deed. Ask a Virginia attorney to establish the proper sellers, and contact the Roanoke City Estates Division for probate procedures.
Will I receive proceeds as soon as I sign?
Not necessarily. Virginia ordinarily requires recording before disbursement, and recordation and disbursement must occur within two business days of settlement, subject to narrow statutory exceptions. A wire or settlement check follows the provider’s clearance process; signing alone does not guarantee immediate bank availability.
Which residential ZIP codes are included in Roanoke and the surrounding area?
Roanoke’s standard residential-delivery ZIP codes include 24011, 24012, 24013, 24014, 24015, 24016, 24017, 24018 and 24019 . The postal area spans city and county locations. The table also covers nearby rural communities and every surrounding city named above; submit the street address to confirm availability.
| Postal Area / Community | Standard Residential-Delivery ZIP Codes |
|---|---|
| Roanoke postal area | 24011, 24012, 24013, 24014, 24015, 24016, 24017, 24018, 24019 |
| Cave Spring; Hollins | 24018; 24019 |
| Salem; Vinton | 24153; 24179 |
| Bent Mountain; Catawba | 24059; 24070 |
| Blue Ridge; Cloverdale | 24064; 24077 |
| Daleville; Troutville; Fincastle | 24083; 24175; 24090 |
| Buchanan / Lithia; Eagle Rock | 24066; 24085 |
| Boones Mill; Rocky Mount | 24065; 24151 |
| Callaway; Ferrum; Glade Hill; Wirtz / Burnt Chimney | 24067; 24088; 24092; 24184 |
| Goodview; Hardy; Moneta | 24095; 24101; 24121 |
| Montvale; Thaxton; Bedford | 24122; 24174; 24523 |
| New Castle | 24127 |
| Elliston / Ironto / Lafayette; Shawsville | 24087; 24162 |
| Blacksburg; Christiansburg | 24060; 24073 |
| Radford / Fairlawn; Dublin; Pulaski | 24141; 24084; 24301 |
| Lynchburg / Timberlake postal area | 24501, 24502, 24503, 24504 |
| Lexington; Buena Vista; Covington | 24450; 24416; 24426 |
| Martinsville | 24112 |
Source: Virginia ZIP directory, standard-delivery classifications. ZIPs can cross jurisdictional boundaries; names above are postal-area references. PO-box-only and unique institutional ZIPs are not presented as residential street-service areas. Verify a particular address through the USPS ZIP Code Lookup. A ZIP listing does not establish that every property in it falls inside the radius or qualifies for an offer.
Roanoke Real Estate & Legal Terms Homeowners Should Know
- Independent city / county equivalent
- Roanoke city has separate land, probate and tax administration. Confirm the parcel’s jurisdiction before ordering records; a mailing address alone is insufficient. USGS city record ↗
- Trustee’s sale
- The power-of-sale auction used to enforce a Virginia deed of trust after default. Use the actual notice and loan terms to assess time for a voluntary sale. Virginia trustee powers ↗
- Virginia Small Estate Act affidavit
- A way to collect qualifying personal probate assets without personal-representative qualification. It excludes the house and does not authorize signing a sale deed. Small-asset definitions ↗
- H-2 Certificate of Appropriateness
- Historic-design approval for covered exterior work in a local H-2 district. Check the approval path before pre-sale alterations; ordinary in-kind repair follows a different process. Working with the Architectural Review Board ↗
- Virginia Land Records Cover Sheet
- The barcode cover sheet required by the Roanoke City Circuit Court for land instruments. The settlement provider includes it in the recordation package. City recording requirements ↗
- Wet settlement
- Virginia’s recording and disbursement framework: recording ordinarily precedes payment, and the settlement agent must record and disburse within two business days of settlement. Signing does not itself guarantee immediate bank availability. Settlement-agent duties ↗
Get a Written Offer for the House You Have Today
Share the address, condition and your preferred timing. We will explain the proposed purchase terms so you can compare them with your other options.
Request My Roanoke Cash Offer Call (866) 651-6617Official Roanoke Homeowner Resources
Use the city offices for City of Roanoke parcels. Confirm a county or neighboring-city parcel’s jurisdiction before requesting records or payoff information.
Appalachian Power is a utility resource; the other links above are government or court resources. Legal and market reference date: October 23, 2026. Recheck time-sensitive rules and balances before acting.