
Get a cash offer in 5 - 10 minutes • Dauphin County, PA
Sell My House Fast in Harrisburg, PA — We Buy Houses for Cash
Searching for “sell my house fast Harrisburg PA”? We buy houses in Harrisburg, PA as-is. Share your address today, review a written cash offer, then choose an available closing date after ownership, title and payoff checks.
A direct sale for the house you own today.
An older home, an inherited property or a house with previous water damage needs an offer based on its actual condition. Tell us what you know; you can compare the written terms before deciding.
Get Your No-Obligation Offer
Start with the property address and your preferred timing.
Offer timing depends on the property information and review. Closing is a separate step; acceptance is your choice.
Harrisburg market watch • September 2026 report
Compare Harrisburg’s Market With the Cost of Preparing Your House
Redfin’s Harrisburg city report describes a very competitive market, yet median time on market increased from 17 to 22 days. It reports 119 September sales versus 143 a year earlier, a 16.9% decline. The narrative uses a three-month price comparison; the trend chart is labeled September 2026. Figures checked October 23, 2026.
If your question is “How can I sell my house fast Harrisburg PA?”, compare a direct offer with a realistic listing plan. A city median is not an offer for your house. Its condition, required work and actual seller payoffs determine which route fits.
Your current-condition option
Sell It Exactly as It Sits in Harrisburg
We buy houses in Harrisburg PA without requiring a pre-sale renovation. These are MHIC’s direct-purchase terms, with any items you plan to leave included in the written agreement.
- Don’t paint Skip interior touch-ups and exterior repainting.
- Don’t replace flooring Leave stained carpets, worn hardwoods or cracked tile.
- Don’t fix the roof We buy with active leaks, missing shingles or an aged roof.
- Don’t stage the home Avoid professional staging and pre-sale decluttering costs.
- Don’t clean it out Take what you want; agree in writing on unwanted furniture, trash and clutter that will remain.
- Don’t schedule dozens of showings Skip open houses and lockboxes; arrange access for our property review.
As-is terms do not remove applicable disclosure duties. In most pre-1978 sales, federal lead-disclosure rules still require known hazard information and records, the prescribed pamphlet and the buyer’s inspection opportunity. Bring existing reports rather than assuming older paint must be replaced before requesting an offer. Our as-is selling guide explains the broader process.
Street-level context
Selling a House in Harrisburg’s Neighborhoods
A historic-district designation or a floodplain example changes what to check, but it does not establish a defect at your address. The seller scenarios below are examples to help you compare options.
| Neighborhood / District | Housing Profile | Common Challenges We Resolve | Seller Scenario |
|---|---|---|---|
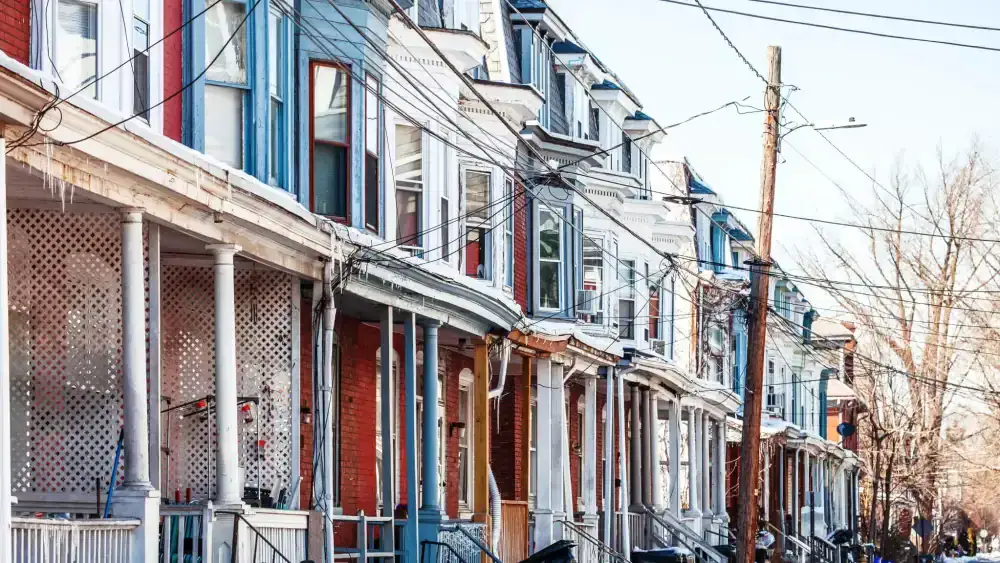
| Old Uptown | Italianate, Queen Anne and Romanesque buildings. A municipal Engleton case documents a brick, semi-detached Queen Anne duplex dating to 1885–1900. | An as-is purchase can address the decision about maintaining historic wood features or an original slate roof. The case report describes one property, not a neighborhood defect rate. | Example: compare a preservation-sensitive repair proposal with selling in current condition. |
| Mount Pleasant | Late Victorian and late-19th/20th-century revival architecture; National Register periods of significance span 1850–1949, not the construction date of every dwelling. | Older painted surfaces may need evaluation. Lead presence requires evidence; an as-is contract does not erase applicable disclosures. | Example: provide existing reports and compare a repair allowance with a direct offer. |
| Shipoke | A municipal report describes a circa-1900 stick-built house at 106 Conoy Street within the Shipoke Municipal and Old Harrisburg National Historic Districts. | That parcel is identified as Zone AE. Review the actual parcel’s flood designation and repair history before pricing; this example does not place every Shipoke home in the same zone. | Example: compare documented water-damage repairs with an offer reflecting the home’s present condition. |
Condition can change the comparison
Harrisburg Property Issues That Deserve a Closer Look
Flood-soaked walls in affected parcels
Harrisburg identifies mapped flood-hazard areas near the Susquehanna River and Paxton Creek, with parcel-specific AE, A, AO and Zone X categories. Risk varies by address.
Pennsylvania DEP explains that floodwater saturates wallboard and insulation, with moisture wicking above the waterline. Wet insulation or soft, fragile, crumbling drywall calls for evaluation; damaged assemblies may require removal. A visible waterline alone may understate the scope.
That scope can change a buyer’s repair allowance or willingness to proceed after inspection. Obtain a qualified assessment or share known damage for an as-is offer. Flood coverage is separate from ordinary homeowners coverage; check the actual policy. See our water-damaged house guide.
Older paint needs evidence, not guesses
The City’s Lead Safe Program targets qualifying pre-1978 property. Lead-containing paint can release hazardous chips and dust when it deteriorates or is disturbed. Peeling, chipping, chalking or cracking paint does not identify its lead content; testing is needed.
This is an age-related concern, not a measured neighborhood defect rate. Known hazards can change a repair plan or buyer negotiations. Preserve inspection records and complete applicable federal lead disclosures even when selling for cash.
Historic exteriors can change the work plan
The Old Uptown case at 1531 North 2nd Street describes original slate roofing, a prominent gable, dormers and historic wood features. Engleton developed mainly in 1880–1910; this is district-specific evidence.
Before changing a publicly visible exterior in an applicable district, check Planning/HARB review and Certificate of Appropriateness requirements. A general replacement allowance may miss the approved scope. Compare a suitable repair proposal with selling as-is.
Leaks, heat and unfinished permit questions
The Harrisburg Bureau of Codes handles permits, construction inspections and compliance; documented subjects include inadequate heat, roof/water leaks and residential lead hazards. The City checks leaks associated with mold but does not handle mold itself.
Bring notices, permits and completed-work records. Ask Codes at 10 North 2nd Street, Suite 205, about unresolved items, and coordinate historic matters with Planning/HARB. A condition issue can prompt inspection negotiations; it does not automatically make every conventional sale impossible. Our code-violation guide outlines sale options.
Radon is a testing question
Pennsylvania DEP recommends home testing and corrective action for confirmed readings of 4 pCi/L or higher. This is statewide guidance, not evidence of an elevated rate in Harrisburg.
Use the home’s test and mitigation records to decide whether to obtain a qualified proposal or include the known condition in your sale discussion.
Roof condition and insurance are specific to the home
Pennsylvania Insurance Department guidance distinguishes confirmed roof deterioration or increased hazard from cosmetic discoloration or streaking alone. There is no verified universal Harrisburg roof-age cutoff here.
Ask the insurer about the actual condition and policy. Pennsylvania generally does not mandate homeowners insurance, although mortgage lenders commonly require it. A documented coverage concern can change a listing plan; it does not establish automatic denial.
Interactive planning tool
AS-IS Repair Cost Estimator
Use a broad allowance to compare listing preparation with an as-is offer. Harrisburg’s historic review and flood-damaged wall assemblies can require scopes that a simple square-foot calculation cannot price. Get property-specific proposals where those conditions apply.
This is not an inspection, appraisal, contractor quote, MHIC offer or guarantee. Actual costs vary substantially with scope, materials, labor, permitting, access and concealed damage. Flood remediation, lead work, structural repairs, historic restoration and code-specific work need separate professional evaluation; they are not included in these allowances.
Compare the whole transaction
Cash Sale vs. Traditional Listing in Harrisburg
A traditional sale may produce a higher gross price, but commissions, seller closing costs, repairs, concessions and ongoing holding expenses reduce the amount you ultimately keep. A direct cash sale generally prioritizes speed, certainty and convenience rather than the highest possible gross price.
Harrisburg’s reported 22 median days on market does not include the contract-to-closing stage. For a house with documented flood damage or a historic exterior project, compare the actual repair proposal and likely selling costs with the written direct offer.
| Decision factor | Traditional listing | Direct cash sale |
|---|---|---|
| Gross price | Potentially higher gross price | Usually lower than full retail value |
| Commissions | Agent commission may apply | No agent commission |
| Closing costs | Seller closing costs may apply | MHIC pays normal closing costs |
| Property condition | Repairs or buyer credits may be requested | Property sold as-is |
| Contingencies | Financing and appraisal contingencies | No buyer-financing contingency |
| Timeline | Longer and less predictable timeline | Seller selects an available closing date |
Listing contingencies depend on the negotiated contract. A direct sale may still have property-review, title or other conditions. Mortgage balances, back taxes, liens and any agreed exceptions affect seller proceeds on either route. Confirm cost allocation in the signed agreement.
Compare Your Estimated Selling Options
Use our adjustable calculator to compare a traditional listing with a direct cash sale using your property’s estimated value and expenses.
Use the Net-Proceeds Calculator →When comparing cash home buyers in Harrisburg PA, ask how the offer accounts for condition and seller payoffs. Our cash-offer guide explains the factors to review.
Ownership and deadlines come first
Probate, Foreclosure Deadlines, and Complicated Title Situations in Harrisburg
An inherited house needs a valid transfer path
Pennsylvania’s settlement of small estates on petition, 20 Pa.C.S. § 3102, applies to qualifying personal property with a gross value no greater than $50,000. Real estate and § 3101-payable property are excluded from that threshold; qualifying family-exemption personal property is included. Owning real estate does not bar relief for qualifying personal property, but this procedure does not convey a house.
Any party in interest may petition in the Orphans’ Court Division of the Pennsylvania decedent’s county of domicile. A court petition and distribution decree are required; relief is discretionary. Section 3102 sets no fixed post-death waiting period, leaves notice and appraisement to the court and imposes no blanket debt-free condition. Meeting the threshold does not automatically authorize a home sale.
The relevant court is the Dauphin County Court of Common Pleas, Orphans’ Court Division. Probate of wills and grants of letters are handled by the Dauphin County Register of Wills, also Clerk of Orphans’ Court, at Dauphin County Courthouse, 101 Market Street, Room 103, Harrisburg, PA 17101. Confirm authority with the clerk and a Pennsylvania probate attorney before signing. Our inherited-property guide can help you organize the sale questions.
Mortgage foreclosure follows a court case
Pennsylvania uses judicial mortgage foreclosure: a court case can proceed to judgment, execution and a sheriff’s sale. The initiating court filing is a Complaint in Mortgage Foreclosure, filed in Dauphin County’s Court of Common Pleas through the Prothonotary. A writ of execution follows an enforceable judgment. This section concerns mortgage foreclosure; tax and municipal-claim sales follow separate rules.
| Stage | Verified requirement | Practical next step |
|---|---|---|
| Act 6 notice | For covered residential mortgages, written notice at least 30 days before acceleration or foreclosure action, by registered/certified mail to the last known address and the residence if different. Abandonment/voluntary-surrender exceptions apply. | Have counsel review coverage and the actual Act 6 notice. |
| Act 91 / HEMAP | When applicable, meet an approved counselor within 30 days plus 3 postal-delivery days, measured from the notice date or later postmark. A timely application creates further protected processing periods. | Use the PHFA fact sheet and the notice’s approved counseling contacts promptly. |
| Complaint response | Responsive pleadings generally are due within 20 days after service with the required notice. Default judgment for failure to plead ordinarily requires another notice at least 10 days before the praecipe. | Review Rule 1026 and Rule 237.1 with an attorney; do not wait for an offer to respond. |
| Sheriff-sale notices | Required handbills and written notices at least 30 days before sale; publication once weekly for 3 successive weeks in the designated newspaper and legal publication, if any, starting at least 21 days before sale. | Read the property’s notices and Rule 3129.2; confirm the scheduled sale directly. |
| Federal servicing restriction | For covered loans/servicers, the first foreclosure notice or filing generally waits until the loan is more than 120 days delinquent, subject to exceptions and loss-mitigation protections. | Regulation X is not a universal Pennsylvania notice-to-sale minimum; ask the servicer and counsel about applicability. |
For Act 6-covered obligations, the right to cure permits tendering arrears without acceleration, performing other required obligations and paying authorized fees/costs at least one hour before bidding begins. It may be exercised up to three times per calendar year. Obtain the servicer’s figures and professional advice early; the last statutory moment is not a workable sale plan.
A direct sale is one possible option only when you have authority and enough time to close and address the necessary payoffs before the scheduled sale. No single notice-to-sale total applies to every loan; requirements can overlap. An offer or signed purchase contract does not itself postpone a sheriff’s sale.
The county’s published schedule places regular sales at 10:00 a.m. in the Dauphin County Administration Building, 2 South 2nd Street, 4th Floor, Commissioners Hearing Room. Continued sales in 2026 are at 10:00 a.m. in the Courthouse lobby, 101 Market Street; starting in 2027 they move to the Administration Building’s 4th-floor hearing room. Verify the property’s current status through the Sheriff’s sale-listing portal and office.
Scheduling example: the published January 14, 2027 regular sale has a November 5, 2026 writ-filing cutoff. That interval is not the total foreclosure duration. There is no post-auction redemption right for the former borrower after a completed mortgage-foreclosure sheriff’s auction, as discussed in In re Pittman, pages 10–11. Pre-sale cure and challenges to an invalid sale are different remedies; tax/municipal-claim redemption rules require separate analysis.
Heirship, recorded claims and unresolved ownership
A title professional can identify the documents and payoffs needed for a valid transfer. Caldwell & Kearns describes local examinations covering deeds, liens, unpaid taxes, municipal claims, seller judgments, legal-description errors and restrictions. It offers title services through Residential-Commercial Abstract Inc.; it is a documented local provider, not a represented MHIC partner.
Ownership and recorded-claim research uses the Dauphin County Recorder of Deeds, James Zugay, at the Courthouse, Room 102, 101 Market Street, Harrisburg, PA 17101, and relevant Prothonotary civil records. Supply estate documents, deeds and notices. A professional must determine how disputed heirship, recorded municipal claims or other clouds can be addressed; a buyer cannot promise their removal.
My House Into Cash provides a purchasing option, not legal, probate, tax, financial or foreclosure-defense advice. Consult the court clerk, county tax collector, a Pennsylvania real estate/probate attorney or a tax professional about your circumstances. We cannot guarantee court approval, foreclosure prevention, lien removal, tax forgiveness or title clearance.
Get the right payoff
Harrisburg Property Taxes: County Bills Are Only Part of the Picture
The Dauphin County Treasurer, Dominic DiFrancesco, collects Harrisburg’s County real estate taxes. The 2026 collector directory assigns City and School taxes to the Harrisburg City Treasurer’s Office. Request the appropriate figures from each collector rather than applying one bill’s dates to all taxes.
| Payment period | County bill treatment |
|---|---|
| Through March 31 | 2% discount |
| April 1–May 31 | Face amount |
| June 1–July 31 | 5% penalty |
| August 1–December 31 | 10% penalty |
The Treasurer’s FAQ explains that unpaid taxes are turned over after December 31 to the Tax Claim Bureau, which supplies delinquent payoff figures. Real Estate Tax Sale Law § 306 sets 9% annual interest on returned taxes under its applicable timetable; do not assume interest automatically starts January 1.
Contact the Dauphin County Tax Claim Bureau, 2 South Second Street, Harrisburg, PA 17101; published contact Holly Martz, (717) 780-6125. Have the settlement provider obtain current amounts and assess what can be addressed from sale proceeds. Back taxes are not automatically forgiven in an as-is sale. Our liens and back-tax selling guide explains what to gather.
From agreement to seller proceeds
What Happens Between Accepting Your Cash Offer and Getting Paid in Harrisburg?
Here is a possible five-day sequence for a straightforward transaction, subject to an available settlement appointment, completed disclosures and satisfactory title/payoff work. These are planning stages, not a guaranteed closing deadline. An estate, disputed ownership or unresolved claim can take longer.
-
Day 0 • Written agreement
Finalize the purchase contract
Confirm price, as-is terms, the closing date, access, items left behind and inspection/cancellation rights. There are no MHIC fees or agent commissions in our direct purchase, and MHIC pays normal closing costs as agreed in writing. Seller debts and payoffs are separate.
For covered older houses, complete the federal lead-disclosure process before the buyer signs, including the prescribed inspection opportunity or a valid written modification/waiver.
-
Days 1–2 • Title and municipal due diligence
Check ownership, records and known compliance matters
The selected title/settlement provider examines deeds, mortgage records and recorded encumbrances in Recorder of Deeds records, along with relevant civil judgments in Prothonotary records. Local counsel’s published examination scope includes unpaid taxes, municipal claims, restrictions and legal-description errors. Confirm the actual provider and any title-insurance selection/costs in the agreement and settlement quote.
Share open code notices and permit records with the closer and Bureau of Codes. Historic exterior questions may also need Planning/HARB review.
-
Days 2–4 • Payoffs and title requirements
Get current figures and resolve what the transfer requires
The provider requests mortgage payoffs, County tax certification through the Treasurer’s published request process, and delinquent amounts from the Tax Claim Bureau. City and School taxes need the proper collector’s figures. Recorded clouds or estate authority must be addressed sufficiently for the agreed transfer; some require more time or professional action.
Review the settlement estimate to see the amount remaining after seller obligations. For a move, separately coordinate electric service with PPL Electric Utilities, Harrisburg’s distribution utility; the generation supplier can differ. This is a service-transfer task, not an assertion that ordinary electric bills are title liens.
-
Day 5, if ready • Signing, recording and payment
Complete the transfer and confirm disbursement timing
PAR Legal describes a fee-simple deed with special warranty as the standard Agreement of Sale default, not a universal statutory requirement. The warranty generally concerns defects arising during the seller’s ownership. The seller/grantor signs using the deed’s legal name; acknowledgment, usually before a notary, is required for recording. Have the preparer confirm the deed and signing requirements for your transaction.
The closing professional arranges recording with the Dauphin County Recorder of Deeds, James Zugay, Courthouse Room 102, 101 Market Street, Harrisburg, PA 17101. A Harrisburg settlement provider documents bank-wire coordination for seller proceeds; confirm your provider’s available payment method and timing. Signing alone does not guarantee immediate receipt.
Local seller-closing guidance includes arranging mail-away documents when needed; ask in advance. Pennsylvania notaries keep a contemporaneous journal under 57 Pa.C.S. § 319; its mandatory-entry list does not include a thumbprint.
Harrisburg and the surrounding region
Explore the 75-Mile Harrisburg Area
Ask whether we can evaluate your address in Harrisburg or a nearby community below. The list uses Census municipal centers within 75 straight-line miles of Harrisburg’s geographic center, not driving distances. It is a geographic reference; availability must be confirmed for the property.
- Camp Hill
- Lemoyne
- New Cumberland
- Mechanicsburg
- Marysville
- Dillsburg
- Steelton
- Highspire
- Middletown
- Hummelstown
- Palmyra
- Carlisle
- Elizabethtown
- Mount Joy
- Lebanon
- York
- Lancaster
- Shippensburg
Harrisburg is the center of this 75-mile geographic reference area.
75-mile radius reference. Select a community to see its direction and straight-line distance from Harrisburg. The outer circle marks 75 miles; the inner circle marks 37.5 miles. Use the Google map below to explore streets and locations.
Pan or zoom the Google map, or select a community to check its approximate distance. The map is a location reference, not a property-eligibility boundary. Open this location in Google Maps.
For statewide information, visit our Pennsylvania home-selling page. A Harrisburg mailing address alone does not establish the municipality responsible for a particular property’s taxes or permits.
Understand the documents
Harrisburg Real Estate & Legal Terms Homeowners Should Know
- Act 91 Notice
- A Pennsylvania pre-foreclosure notice explaining HEMAP and counseling rights. If it applies to your loan, act on its counseling deadline so a timely assistance application can receive the applicable processing protections. PHFA guidance.
- Act 6 right to cure
- For covered residential mortgages, a route to reinstate by paying required arrears and authorized charges and meeting other obligations before the pre-auction deadline. Ask for the cure amount when comparing keeping the home with selling. Act 6, §§ 403–404.
- Settlement of small estates on petition
- A court-directed personal-property procedure. It does not transfer an inherited house, so verify the estate’s separate authority to convey real estate before agreeing to a sale. 20 Pa.C.S. § 3102.
- Certificate of Appropriateness (COA)
- Historic-district approval within Harrisburg’s overlay review process. Visible exterior alterations may need review before permits and work can proceed; check this before relying on a replacement quote. Historic Overlay District rules.
- Tax Claim Bureau
- Dauphin County’s delinquent real-property tax collection office. Its current payoff, rather than an old bill balance, helps the settlement provider account for arrears in your proceeds. County office.
- Special warranty deed
- The PAR standard sale-contract default limits the seller’s warranty to defects arising during the seller’s ownership. Review the deed promised by your actual agreement and discuss unfamiliar warranties with counsel. PAR Legal explanation.
Straight answers for sellers
Harrisburg Cash Home Sale FAQs
Which ZIP codes can I ask about in Harrisburg and nearby residential areas?
Send the property’s complete street address for confirmation. The table covers standard delivery ZIPs associated with Harrisburg and the named surrounding postal communities, including the nearby places in our area list. Postal areas and municipal boundaries differ, so these labels do not determine taxes, permits or service eligibility.
| Postal community / area | Standard street-address ZIP codes to check |
|---|---|
| Harrisburg postal areas | 17101, 17102, 17103, 17104, 17109, 17110, 17111, 17112, 17129 |
| Steelton and adjoining postal areas | 17113 |
| Camp Hill | 17011 |
| Lemoyne | 17043 |
| New Cumberland | 17070 |
| Mechanicsburg | 17050, 17055 |
| Marysville | 17053 |
| Dillsburg | 17019 |
| Highspire | 17034 |
| Middletown | 17057 |
| Hummelstown | 17036 |
| Palmyra | 17078 |
| Carlisle postal areas | 17013, 17015 |
| Elizabethtown | 17022 |
| Mount Joy | 17552 |
| Lebanon postal areas | 17042, 17046 |
| York postal areas | 17401, 17402, 17403, 17404, 17406, 17407, 17408 |
| Lancaster postal areas | 17601, 17602, 17603 |
| Shippensburg | 17257 |
| Enola | 17025 |
| Dauphin | 17018 |
| Duncannon | 17020 |
| Grantville | 17028 |
| Hershey | 17033 |
| Boiling Springs | 17007 |
| Etters | 17319 |
| Lewisberry | 17339 |
| York Haven | 17370 |
Delivery classifications were checked against the USPS October 2026 ZIP Locale Detail file. A standard classification does not prove residential use at every address; 17129 is included for address-level checking. PO Box-only and agency/organization-only mail codes are not treated as residential neighborhoods. This is a list for the named communities, not every ZIP touching a 75-mile circle. Use USPS ZIP Code Lookup for the property’s exact mailing address.
How do I sell my house for cash in Harrisburg PA?
Share the address, known condition, ownership information and preferred timing. Review a written offer with the price, cost allocation, inspection/cancellation rights and available closing date. A local settlement provider checks title and seller payoffs; the amount you keep can differ from the gross offer. Start with our cash-purchase process.
Can I sell house fast in Harrisburg PA without fixing an older property?
Yes, MHIC can evaluate a house in its present condition. Supply known condition reports, open code notices and estate information where relevant. An as-is sale does not remove applicable disclosures; most pre-1978 transactions still have federal lead-disclosure requirements. Put agreed leave-behind items and access arrangements in the contract.
Can Pennsylvania’s small-estate procedure transfer an inherited Harrisburg house?
No. Section 3102 concerns qualifying personal property worth no more than $50,000, excluding real estate and § 3101-payable property from that threshold. It requires a court petition and decree and does not convey a house. Confirm the estate’s authority to sell with Dauphin County’s Register of Wills/Clerk of Orphans’ Court and a Pennsylvania probate attorney.
Can a cash sale stop a Dauphin County sheriff’s sale?
A completed sale may be one option if the owner has legal authority, sufficient time and a workable payoff/title path before the auction. Requesting an offer or signing a contract does not itself stop foreclosure. Pennsylvania uses judicial mortgage foreclosure, and loan-specific notices, cure rights and court deadlines must be reviewed with the servicer and qualified counsel.
Does every Shipoke house have the same flood risk?
No. The municipal case for 106 Conoy Street identifies that parcel as Zone AE; it does not classify the whole neighborhood. Review your address with Harrisburg Planning and the FEMA Flood Map Service Center, along with known water history and repair records. Flood-damaged walls require a property-specific evaluation.
What should I compare when choosing cash buyers for houses in Harrisburg PA?
Compare the legal buyer named in the contract, written price, seller payoffs, closing-cost allocation, inspection/cancellation rights, assignment terms and any price-change provisions. Ask who will handle the Dauphin County title and tax checks. A higher headline offer is not necessarily a higher final payment.
Is a five-day Harrisburg closing guaranteed?
No. The five-day sequence above is an illustrative plan for a straightforward transaction. Ownership authority, title examination, tax and mortgage payoffs, disclosures, signing arrangements and settlement availability determine the actual date. Put the available date and contract conditions in writing.
Get a Written Offer for Your Harrisburg House
Start with the address and what you know about the property. Include any estate paperwork, code notices or previous water-damage reports so the condition and title review can begin with useful information.
Prefer to talk? Call (866) 651-6617.
Primary sources for your next step
Official Harrisburg Homeowner Resources
Use the office responsible for your parcel, tax bill or court matter. Verify current requirements before taking action.
General homeowner information, not individualized legal, tax, probate, financial or foreclosure-defense advice. Consult the relevant public office and your qualified adviser about your transaction.