
⚡ Get a cash offer in 5 - 10 minutes • Buncombe County, NC
Sell My House Fast in Asheville, NC — We Buy Houses in Asheville for Cash
To sell your house fast in Asheville, send your address and condition or call today. We buy houses in Asheville as-is and explain a written cash offer. Accept when ready, then choose an available closing date with the closing attorney.
A clear offer for the house you have today.
- Sell As-Is
- No Agent Commission
- Normal Closing Costs Paid
- Flexible Closing Date
Average Call-back in 60 seconds or less 24/7/365
Talk with trusted real estate professionals from MyHouseIntoCash to buy your house fast. We handle all the paperwork and tailor a hassle free closing process to fit your moving plans.
Strictly Confidential & No Obligation
Receive a clear offer, ask your questions, and decide without pressure.
Get Your Asheville Cash Offer
Tell us about the property and your preferred timing.
Calling our main toll-free number? Ask about your Asheville property. There is no obligation to accept an offer.
Asheville market watch • Research dated October 22, 2026
What Does a Faster Sale Mean in Asheville’s Market?
Redfin’s Asheville report, displaying September 2026, describes the three months ending September 2026 as somewhat competitive, with a Compete Score of 39. Its separate competition panel shows approximately 76 days to pending; that is a different measure from the displayed 74-day median days on market.
For a seller, the useful question is how much preparation and carrying time a listing could require at this address. A ready-to-list home may benefit from retail exposure. An older house with unresolved moisture or repair work deserves a comparison between renovation costs and a written as-is offer.
These are city retail-market observations, not an appraisal, a cash-offer estimate or a closing guarantee. See our North Carolina home-selling overview for statewide coverage.
Keep the preparation off your calendar
Sell It Exactly as It Sits in Asheville
We buy houses in Asheville in their current condition. Request an offer before ordering materials or starting a cleanout. Our direct-purchase policy lets you skip the following preparation; agree on access and anything left behind in the written contract.
An as-is sale does not supply a missing permit approval. For an Asheville addition or unfinished project, gather the available records from Development Services so the offer reflects what is actually there. Our guide to selling a house as-is explains the broader comparison.
Older houses need property-specific decisions
Selling a House in Asheville’s Neighborhoods
Historic inventories describe different building materials and forms across these areas. They do not establish a defect rate or the condition of your house. The seller scenarios below are examples of decisions an owner might face, not customer stories or measured neighborhood trends.
| Neighborhood / District | Housing Profile | Common Challenges We Resolve | Seller Scenario |
|---|---|---|---|
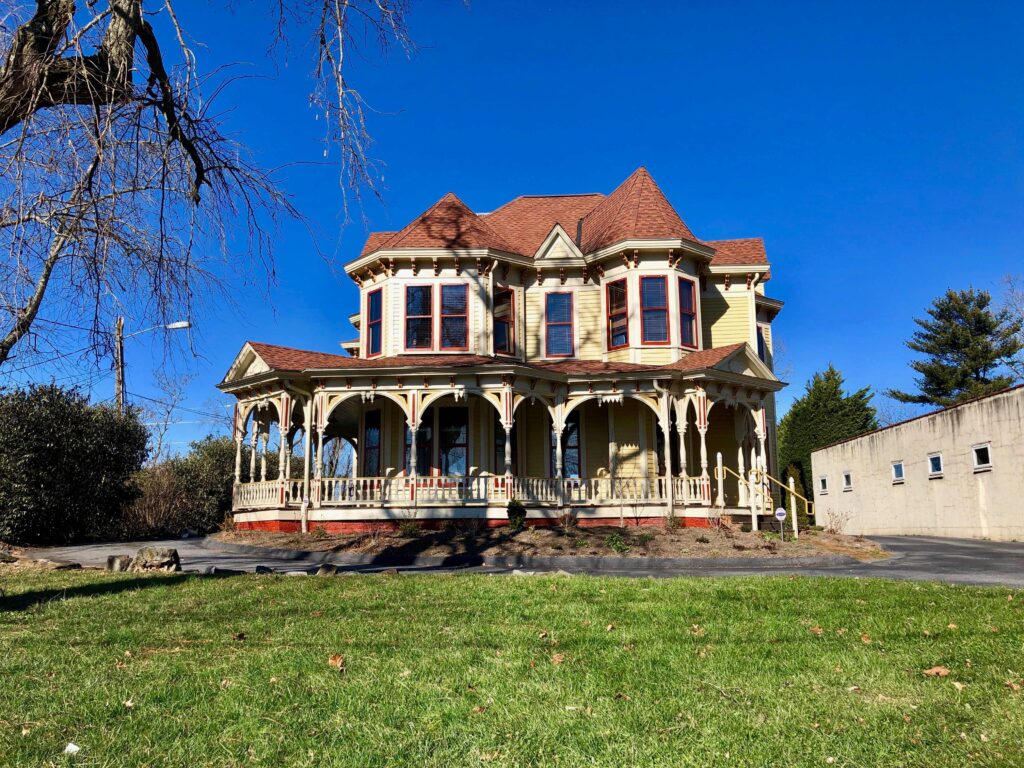
| Montford | Late-19th- and early-20th-century Queen Anne, Shingle-style and vernacular houses; weatherboard, shingles and stucco over documented brick or stone foundations. | Where drainage is poor or lower levels are wet, review masonry and wood floor framing for moisture and decay. NC State’s inspection guide supports this condition-based check. | Compare the scope of an older or inherited home’s rehabilitation with an offer that accounts for its current condition. |
| Grove Park / Sunset Mountain | Early-20th-century Colonial Revival, Tudor Revival and Craftsman houses; the Kimberly expansion includes 1920s stucco, brick and stone detailing with raised basements. | On a sloping parcel, check drainage, retaining structures and actual signs of movement using NC Geological Survey guidance. Slope risk varies by site. | Price basement or retaining-wall work before deciding whether to repair, list or request an as-is offer. |
| Biltmore Village | Historic late-19th- and early-20th-century cottages, including one-and-a-half- to two-story pebbledash and half-timbered buildings with steep roofs and brick foundations. Some buildings have changed use. | For affected parcels in the Swannanoa River lowlands, review flood history, repair records and permits. The City documents continuing post-Helene recovery. | Compare restoration and permitting costs with selling in current condition; confirm the actual building’s residential use and zoning. |
What can change an Asheville repair budget?
Look Below the Finishes: Water, Wood and Hillside Conditions
Asheville’s historic inventories document wood-frame construction, masonry foundation walls and raised basements. They also record gable and hip roofs with asphalt shingles, plus some Montford slate and pressed-metal examples. Those are documented older-house examples, supported by the Grove Park inventory, rather than citywide material shares. Identify the actual roof and structure before comparing bids.
Flood-affected river and stream parcels
In inundated French Broad or Swannanoa river corridors and tributary floodplains, water can saturate wall cavities, insulation and framing. Water lines, silt, damp insulation, stained wall bottoms and musty odors warrant investigation; a dry-looking surface does not establish that concealed materials have dried. NC State explains the moisture mechanism.
For an affected property, keep repair and drying records. A buyer may ask for them or adjust a repair allowance. FEMA defines substantial damage as restoration costs reaching or exceeding 50% of the structure’s pre-damage market value; an applicable determination can require floodplain-compliant reconstruction. Check the parcel’s FEMA map and local requirements before committing to a renovation budget.
Localized floodplain risk. Biltmore Village recovery documents a real affected area; it does not establish flood damage at every Asheville home.
Persistently wet crawlspaces and basements
In wood-framed houses of any age, ground moisture, leaks and poor drainage can keep floor framing wet. Sustained moisture can support fungal decay and wood-destroying pests. Standing water, damp insulation, soft joists and uneven floors need investigation; visible mold alone does not prove structural decay. See NC State’s moisture guidance.
The practical question is what keeps the area wet and how much material is affected. Painting over stains does not correct the source. If an inspection identifies damage, conventional buyers may seek drainage or structural work, a credit or further evaluation. Compare that documented scope with an as-is offer.
A regional, condition-based concern; no Asheville-specific prevalence percentage was verified.
Slopes, retaining structures and changing drainage
On susceptible slopes, cut-and-fill sites or embankments, intense rainfall and infiltrating water can destabilize soil or weathered rock. NC Geological Survey warning signs include expanding ground cracks, bulging soil, leaning trees, displaced masonry, tilted chimneys, sticking doors and drainage changes.
Those observations may call for a geotechnical assessment before pricing repairs; findings can affect a buyer’s price or ability to obtain a mortgage. A mountain address alone is not proof of instability. An as-is offer is one option to compare after the known condition and access are understood.
Regional tendency on susceptible sites. NC DEQ documents French Broad basin recovery and resilience work; assess the individual parcel.
Insurance is part of the carrying-cost comparison
Buncombe County is in homeowners rating territory 360. The NC Department of Insurance settlement table lists approved base-rate increases of 4.4% for 2025 and 4.5% for 2026, effective June 1 of each year under the settlement. Your renewal premium can differ.
The Department’s homeowners insurance guide explains condition, maintenance and claim-history considerations. Standard homeowners coverage excludes flood and landslide losses; do not assume ordinary flood coverage protects against slope failure. Ask your insurer about the actual policy and repair requirements while weighing a longer holding period.
These findings do not establish a universal roof-age cutoff, mandatory four-point inspection or automatic insurance denial.
The possible buyer responses above are practical inferences from the documented conditions, not measured Asheville cancellation rates or automatic consequences for every sale.
Keep the property record with the property
Unfinished Work, Code Notices and Service Accounts
Asheville’s Development Services Compliance Division handles minimum housing, unsafe buildings, development and zoning, nuisance and short-term-rental compliance. If you have a notice, share the actual document so the condition review and closing attorney can address the issue shown in the record.
For unpermitted work, the Permit Application Center is at 161 South Charlotte Street; call (828) 259-5846 for permit-history and department guidance, with Building Safety Inspections or Compliance involved as applicable. Selling as-is does not create an approval for existing work.
Duke Energy Progress serves the Asheville region; verify the utility for your parcel and coordinate the service account separately. Do not treat an ordinary electric bill as a recorded property lien.
Interactive planning tool
AS-IS Repair Cost Estimator
Build a broad planning range to compare renovation with selling in current condition. This is not an inspection, appraisal, contractor quote, cash offer or guarantee. The dollar assumptions below are illustrative inputs, not measured Asheville contractor prices.
Finish rates cover cosmetic interior work only. Add a system allowance only when it is outside that finish scope, and select each once to avoid double counting.
Actual costs can vary substantially with scope, materials, labor, permitting, site access and concealed damage. Permit fees, structural reconstruction, geotechnical work, major retaining structures and floodplain-compliant rebuilding are excluded. Asheville’s documented water and slope concerns can exceed a basic allowance; get specialist bids where applicable. This estimate is not an automatic deduction from an MHIC offer.
Compare the price, proceeds and terms
Cash Sale vs. Traditional Listing in Asheville
A traditional sale may produce a higher gross price, but commissions, seller closing costs, repairs, concessions and ongoing holding expenses reduce the amount you ultimately keep. A direct cash sale generally prioritizes speed, certainty and convenience rather than the highest possible gross price.
Asheville’s reported retail marketing period makes holding costs worth including. For a flood-affected home, compare a documented restoration scope rather than a cosmetic renovation estimate. Read how cash buyers calculate offers before comparing the numbers.
| Decision Point | Traditional Listing | Direct Cash Sale with MHIC |
|---|---|---|
| Gross Price | Potentially higher gross price | Usually lower than full retail value |
| Commissions | Agent commission may apply | No agent commission |
| Closing Costs | Seller closing costs may apply | MHIC pays normal closing costs |
| Property Condition | Repairs or buyer credits may be requested | Property sold as-is |
| Contingencies | Financing and appraisal contingencies | No buyer-financing contingency |
| Timeline | Longer and less predictable timeline | Seller selects an available closing date |
Individual listing contracts vary. Review all inspection, title and cancellation terms in either offer. Mortgage balances, back taxes, recorded claims and any negotiated exceptions still affect seller net proceeds; normal closing-cost coverage does not erase those obligations.
Compare Your Estimated Selling Options
Use our adjustable calculator to compare a traditional listing with a direct cash sale using your property’s estimated value and expenses.
Use the Net-Proceeds Calculator →Check authority and the actual deadline first
Probate, Foreclosure Deadlines, and Complicated Title Situations in Asheville
Inherited property: the small-estate affidavit does not transfer a house
North Carolina’s collection-by-affidavit procedure concerns qualifying personal property. The limit is $20,000 after liens and encumbrances, or $30,000 for a qualifying surviving-spouse affiant entitled to all the property, after reduction for any spousal allowance paid. At least 30 days must have passed after death. Those limits are not house-value exemptions and do not authorize a home sale.
The affidavit is filed with the clerk in the county where the deceased person was domiciled. No application for a personal representative may be pending or granted in any jurisdiction. Under the intestate procedure, a qualified public administrator, heir or creditor may act; the testate procedure also includes a named executor or devisee, subject to statutory qualifications. In a testate case, the will must be admitted to probate and a certified will recorded in each county containing the deceased person’s real property.
If land must be sold, leased or mortgaged to pay estate claims, the affiant must seek appointment of a personal representative under G.S. 28A-25-3. Debts retain their statutory payment priority; the distribution affidavit is due within 90 days unless the clerk extends the period. The simplified process still involves a clerk filing even when full personal-representative administration is unnecessary for routine personal-property collection.
For a Buncombe estate, contact the Buncombe County Clerk of Superior Court — Estates Division, serving as the probate court, at Buncombe County Courthouse, 60 Court Plaza, Asheville, NC 28801. Have an attorney confirm ownership, signing authority and any required court approval before accepting a sale contract. Our inherited-house guide provides a broader starting point.
Foreclosure: work from the filed notices, not a generic countdown
North Carolina permits judicial foreclosure by civil action and deed-of-trust power-of-sale foreclosure through a special proceeding. The latter still requires a clerk’s hearing and court authorization. The trustee or substitute trustee files the Notice of Hearing with the Buncombe County Clerk of Superior Court; the later Notice of Sale announces the authorized auction. The Judicial Branch’s foreclosure explanation distinguishes these procedures.
A direct sale is one possible option when the owner has legal authority, the required payoffs can be addressed and there is enough time to complete the transaction before a scheduled sale. Request the actual case documents and ask a North Carolina real estate attorney about the deadline. An offer or signed purchase agreement does not itself pause foreclosure.
Notice periods and payoff rights that can affect the available time
- For covered primary-residence home loans, the statutory pre-foreclosure notice must be mailed at least 45 days before filing the Notice of Hearing. See G.S. 45-102.
- The hearing notice must be served at least 10 days before the hearing; authorized sheriff’s posting requires at least 20 days. It describes the default, applicable acceleration and any permitted cure right. See G.S. 45-21.16.
- The sale notice is posted in the clerk-designated public-notice area at least 20 days before sale. Publication is once weekly for two successive weeks, with at least seven days between the first and last publication, inclusive, and the last publication no more than 10 days before sale. Required sale notices are mailed at least 20 days before sale; residential-occupant notice also applies. See G.S. 45-21.17.
- For covered servicing, federal Regulation X generally restricts the first foreclosure notice or filing until a loan is more than 120 days delinquent, subject to exceptions and other loss-mitigation protections. See 12 CFR 1024.41(f).
These periods are separate requirements, not numbers to add into a reliable default-to-auction total. Applicability, service, overlapping notices and continuances change the actual calendar.
G.S. 45-21.20 permits satisfaction of the secured obligation plus sale expenses before sale or before the upset-bid deadline expires. This is full satisfaction; it does not create an unconditional right to reinstate by paying only arrears. Verify any reinstatement option in the loan documents or with the servicer.
The initial upset-bid period runs through the tenth day after the Report of Sale is filed, subject to statutory office-closure rules; each qualifying upset bid restarts it. The post-auction opportunity to satisfy the debt ends when that period expires. There is no separate additional redemption window after rights become fixed.
The County lists mortgage foreclosure auctions on the courthouse first floor in front of the stairs, with notices on the first-floor bulletin board. Its separate tax-foreclosure program specifies the courthouse front steps. Both refer to 60 Court Plaza; confirm the exact time and venue in the individual Notice of Sale. See our foreclosure selling guide for general sale considerations.
Back taxes, heirship questions and recorded claims
The closing attorney reviews the deed chain, recorded claims, relevant estate or court records and required payoffs using the Buncombe County Register of Deeds and applicable county records. If heirship, a code-enforcement charge or another claimed lien is involved, counsel determines its legal effect and what documents or releases are needed. A code notice is not proof that every listed charge is a title lien.
Buncombe County Tax Collections supplies the parcel’s tax balance. Under G.S. 105-360, taxes are due September 1 and payable without interest through the following January 5. Interest starts January 6 at 2%, followed by an additional 0.75% for each month or fraction beginning February 1; collection costs can apply separately.
For 2026 Buncombe tax bills, the due date was September 1, 2026; January 5, 2027 is the last interest-free payment day, and delinquency begins January 6, 2027. The County says its 2021 Schedule of Values applies to 2026 bills with applicable improvements and Helene adjustments; pending 2026 reappraisal appeals carry toward the 2027 reappraisal. Use an actual payoff and do not substitute assessed value for a market-price estimate.
My House Into Cash provides a direct purchasing option, not legal, tax, probate, foreclosure-defense or financial advice. Consult the court clerk, county tax collector, a North Carolina real estate attorney or a tax professional about your circumstances. No offer guarantees foreclosure prevention, court approval, lien removal, tax forgiveness or title clearance.
From signed agreement to seller proceeds
What Happens Between Accepting Your Cash Offer and Getting Paid in Asheville?
North Carolina residential closings use attorney-led legal work for title opinions, document preparation and title-defect resolution. The North Carolina State Bar explains the licensed legal role. Signing may be arranged through supervised assistants or a separate appointment; all parties need not sit at one table. The Real Estate Commission’s closing guide also distinguishes owner’s and lender’s title-insurance protection.
The schedule below is an illustrative accelerated workflow, not a verified Asheville average or a five-day closing promise. Counsel must confirm the available date. Estate authority, disputed title, payoffs, recording requirements and document readiness can extend any stage.
-
Day 0: Mutual agreement and purchase contract
Put the price, current-condition purchase, review rights, occupancy, items left behind and available closing date in writing. MHIC charges no service fee or agent commission and pays normal closing costs under the agreement. Existing mortgage, tax and claim payoffs remain part of the seller’s proceeds calculation. See how our purchase process works.
-
Days 1–2: Title search and property-record review
The closing attorney examines the deed chain, deeds of trust and satisfactions, easements, restrictions and other encumbrances; identifies taxes and relevant court or estate matters; and determines what is needed to close. Sources include Buncombe land records, tax records and applicable judicial records. Recent construction may require contractor information and lien waivers. Provide actual code notices and permit records when relevant.
-
Days 2–4: Payoff figures and required title work
Counsel requests mortgage and tax payoffs, checks the authority of each conveying owner or representative, and addresses required releases or corrections. Request a date-specific tax balance from Tax Collections rather than estimating interest. An unresolved ownership dispute or missing release can require more time; the attorney updates title before recordation.
-
Day 5, if ready: Deed signing, recording and disbursement
The standard North Carolina Form 2-T contract contemplates a General Warranty Deed, but private and estate transactions can use an instrument selected by counsel. Owners or authorized representatives execute it with a legally sufficient acknowledgment, ordinarily a notarial certificate. Spousal joinder or a valid waiver may be needed, subject to exceptions; the ordinary acknowledgment route does not require two attesting witnesses. Counsel should confirm any transaction-specific signing requirements.
The Buncombe County Register of Deeds — Real Estate Recording is at 205 College Street, Asheville, NC 28801; recording telephone (828) 250-4302. The same-business-day submission cutoff is 4:45 p.m. for recordable documents, with extra time needed for tax approval.
Signing does not itself release the seller’s proceeds. Under G.S. 45A-4, counsel must satisfy settlement-account requirements and record the required instruments before disbursement. Arrange a bank wire or attorney trust check with counsel; the State Bar trust-account handbook documents these methods. Recording and bank processing affect when you can use the proceeds.
If you need independent local counsel, The Van Winkle Law Firm lists residential and commercial real-estate services at 11 North Market Street, Asheville, (828) 258-2991. This is one local practice to consider; an MHIC partnership or endorsement has not been verified. You may choose your own North Carolina attorney.
Asheville and the surrounding North Carolina region
Asheville and Nearby Communities
We buy houses in Asheville and surrounding communities. The locations below are local references, not a service boundary. If your property is elsewhere, send us the address and tell us about your selling plans.
- Woodfin
- Biltmore Forest
- Weaverville
- Fletcher
- Black Mountain
- Mills River
- Marshall
- Mars Hill
- Canton
- Hendersonville
- Laurel Park
- Clyde
- Flat Rock
- Brevard
- Waynesville
- Burnsville
- Marion
- Morganton
Explore Asheville and nearby communities. Select a community to update the map.
Google street map: pan or zoom to explore. Open the selected location in Google Maps ↗
Explore nearby communities
Select a point or choose a community above to update Google Maps. This locator uses representative town locations and does not show street or parcel boundaries.
Center: 35.595, −82.55167, the NOAA downtown reference point near Patton Avenue and Pack Place. Community locations use Census incorporated-place centroids. These communities are examples of nearby locations. Share the actual property address for an individual review.
Terms you may encounter in local paperwork
Asheville Real Estate & Legal Terms Homeowners Should Know
- Clerk of Superior Court
- In Buncombe County, this office administers estates and serves as the probate court; it also hears deed-of-trust power-of-sale proceedings. Confirm the representative’s authority in the estate records before an inherited-property sale.
- Notice of Hearing
- The filed document initiating a North Carolina power-of-sale special proceeding. It sets the clerk’s hearing and differs from the later auction Notice of Sale. Read the actual notice and hearing requirements when checking your deadline.
- Upset bid
- A qualifying higher bid filed with the clerk after auction. Each bid restarts the ten-day period; the initial deadline is measured from filing the Report of Sale. That affects finality and the remaining payoff opportunity under G.S. 45-21.27 and G.S. 45-21.20.
- Collection by affidavit
- The simplified personal-property estate procedure with qualifying $20,000/$30,000 limits. It does not transfer a house; selling land to pay claims requires additional authority. See Chapter 28A, Article 25.
- Substantial damage
- Restoration cost equaling or exceeding 50% of the structure’s pre-damage market value. An applicable determination can change floodplain rebuilding requirements, so obtain the local determination before pricing repairs. See FEMA’s definition and Asheville flood information.
- Good Funds Settlement Act
- North Carolina’s settlement-account rules. Signing alone does not release seller proceeds; required instruments must be recorded and account requirements met before disbursement. See G.S. 45A-4.
Straight answers for local sellers
Asheville Cash House Buyers: Frequently Asked Questions
Searching “sell house fast Asheville NC”? Start with the actual address, condition and available closing date. These answers help you compare a direct sale with preparing the house for the retail market.
Which residential ZIP codes do you cover in Asheville and the surrounding area?
We evaluate Asheville properties and nearby North Carolina addresses individually. This expanded residential-delivery reference covers the communities listed above and additional surrounding postal areas. ZIPs can cross municipal boundaries, and this list does not limit where you can request an offer. Send the street address for an individual review.
| Community / Postal Area | Residential Delivery ZIP Codes |
|---|---|
| Asheville area, including Woodfin and Biltmore Forest postal areas | 28801, 28803, 28804, 28805, 28806 |
| Alexander | 28701 |
| Arden | 28704 |
| Barnardsville | 28709 |
| Black Mountain | 28711 |
| Candler | 28715 |
| Fairview | 28730 |
| Leicester | 28748 |
| Swannanoa | 28778 |
| Weaverville | 28787 |
| Fletcher | 28732 |
| Mills River | 28759 |
| Hendersonville / Laurel Park area | 28739, 28791, 28792 |
| Flat Rock | 28731 |
| East Flat Rock, Etowah, Gerton, Horse Shoe, Zirconia | 28726, 28729, 28735, 28742, 28790 |
| Canton | 28716 |
| Clyde | 28721 |
| Waynesville | 28785, 28786 |
| Lake Junaluska / Maggie Valley | 28745, 28751 |
| Marshall / Mars Hill / Hot Springs | 28753, 28754, 28743 |
| Brevard | 28712 |
| Other surrounding Transylvania postal areas | 28708, 28718, 28747, 28766, 28768, 28772, 28774 |
| Burnsville / Green Mountain | 28714, 28740 |
| Marion / Nebo / Old Fort | 28752, 28761, 28762 |
| Morganton | 28655 |
| Spruce Pine | 28777 |
| Columbus / Mill Spring / Saluda / Tryon | 28722, 28756, 28773, 28782 |
| Surrounding Rutherford postal areas | 28018, 28040, 28043, 28139, 28160, 28167, 28746 |
Local references: Buncombe County ZIP map, Henderson County ZIP layer, the regional postal directory and Morganton postal reference. Confirm a complete mailing address with USPS ZIP Code Lookup.
P.O.-box mailing ZIPs such as Asheville 28802, Enka 28728, Montreat 28757, Ridgecrest 28770 and Skyland 28776 are not listed as residential street-delivery areas. A mailing box does not rule out a property purchase: provide the physical address and its verified delivery ZIP.
How can I sell my house for cash in Asheville?
Send the property address, known condition, ownership details and preferred timing, or call (866) 651-6617. My House Into Cash reviews the property and explains a written offer. If you accept, a North Carolina closing attorney handles the legal title work and confirms an available closing date.
How should I compare cash home buyers in Asheville?
Compare written price, inspection and cancellation rights, normal closing-cost coverage, the proposed closing date and estimated net proceeds. Ask how known flood repairs, drainage or slope concerns affect the offer. Choose among Asheville cash house buyers using the actual contract and property record, rather than a headline price alone.
Can I sell my Asheville house as-is after flooding?
You can request an offer in the property’s current condition. Share flood history, repair records and any permit or substantial-damage determination. For an affected floodplain property, reconstruction requirements can change the repair budget; an as-is agreement does not supply missing permits or establish that concealed materials are dry.
Can a small-estate affidavit authorize the sale of an inherited Asheville house?
No. North Carolina’s collection-by-affidavit procedure concerns qualifying personal property, with $20,000 or qualifying $30,000 limits and a 30-day waiting period. It does not itself convey a house. Ask the Buncombe Estates Division and a North Carolina attorney to confirm ownership, authority and any required court involvement before a sale.
Can I sell before a scheduled Buncombe County foreclosure?
A direct sale may be possible when the owner has legal authority, required payoffs can be addressed and there is enough time to complete the transaction before the scheduled sale. An offer does not pause foreclosure. Have a North Carolina attorney review the filed notices, the exact deadline and any available servicer options promptly.
Does a cash offer equal the amount I receive?
Not necessarily. Mortgage balances, back taxes, recorded claims and negotiated exceptions can reduce the amount disbursed. MHIC pays normal closing costs under the written agreement and charges no agent commission. Request the attorney’s settlement estimate to compare your expected net proceeds.
Will I get paid immediately when I sign the deed?
Signing alone does not release North Carolina seller proceeds. The closing attorney must satisfy settlement-account requirements and record the required instruments before disbursement. Arrange the wire or trust-check method with counsel and ask about recording and bank-processing times.
How quickly can an Asheville cash sale close?
The available date depends on title, ownership authority, payoff responses and document readiness. The day-by-day workflow on this page is an illustration, not a guaranteed five-day closing. Buncombe’s same-business-day recording cutoff is 4:45 p.m. for recordable documents; tax approval may require additional time.
Start with the house as it is
Request a Cash Offer for Your Asheville House
Share the address, what you know about the condition and when you would like to move. For an inherited home or a property with a recorded notice, include that information early so the ownership and timing questions can be reviewed.
Request My Asheville Cash Offer →Prefer to talk? Call (866) 651-6617.
Primary sources for your next step
Official Asheville Homeowner Resources
Check the applicable record and office for your parcel. Permit status, tax balances, estate authority and flood exposure need property-specific answers.
Local research dated October 22, 2026. Market observations use the reporting periods stated above. Consult qualified professionals for legal, tax, insurance and property-condition decisions.