
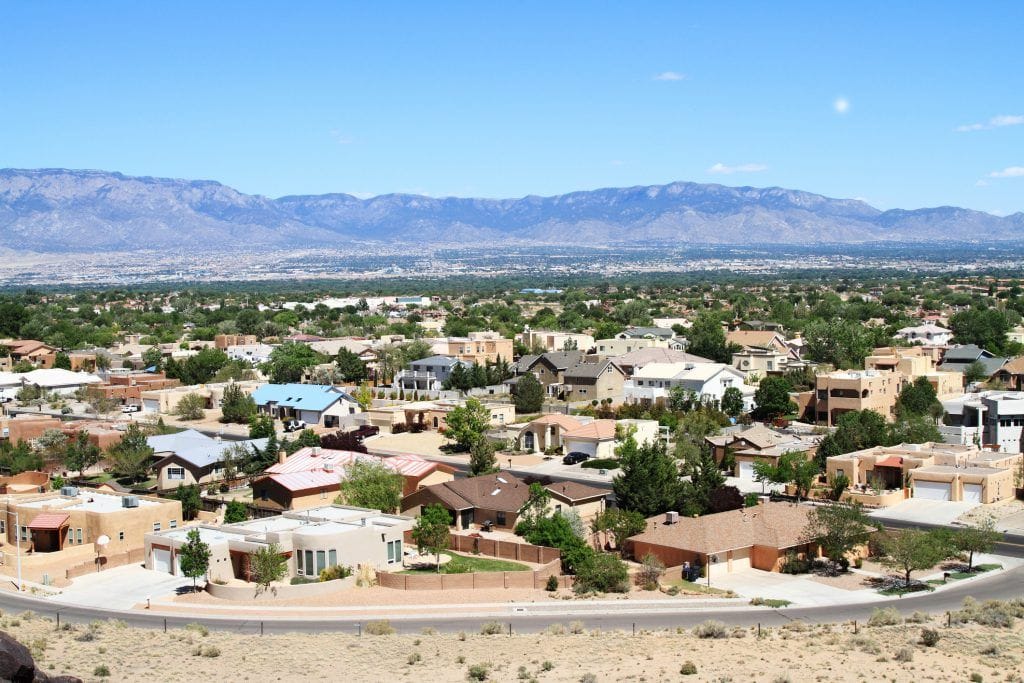
Sell My House Fast in Albuquerque, NM — We Buy Houses As-Is
We buy houses in Albuquerque, NM as-is. Call (866) 651-6617 or send your address today for a written cash offer. Share known property issues, compare the terms, and choose an available closing date after ownership, title, and payoff review.
A Direct Cash Offer Without Preparing Your House for a Listing
(866) 651-6617CLICK TO CALL NOW FOR A FAST, NO OBLIGATION CASH OFFERGet Your No-Obligation Offer
Sell your Albuquerque, NM house as-is, for cash.
Use our fast response form to receive a fair all cash offer today.
🔒 Strictly Confidential: No obligation to accept.
Average Call-back in 60 seconds or less 24/7/365
Talk with trusted real estate professionals from MyHouseIntoCash to buy your house fast. We handle all the paperwork and tailor a hassle free closing process to fit your moving plans.
Strictly Confidential & No Obligation
Receive a clear offer, ask your questions, and decide without pressure.
ALBUQUERQUE, NEW MEXICO · THREE MONTHS ENDING AUGUST 2026
Albuquerque Market Watch: What Does a Fast Sale Mean?
Redfin’s Albuquerque city report covers the three months ending August 2026, all home types. Median marketing time fell from 34 to 32 days. The report describes the market as somewhat competitive, with a 67/100 Compete Score; the separate demand widget’s approximately 35 days to pending is a different measure.
The report also shows a 99% sale-to-list price ratio, 37.3% of homes with price drops and 22.7% selling above list price. Those results support comparing a condition-specific listing estimate with an as-is cash offer, rather than assuming every house sells at the original asking price.
For cash buyers for houses in Albuquerque, a workable date depends on more than marketing time. Historic exterior approvals, an adobe repair scope or a title requirement can change preparation and closing readiness. Compare the written price and terms with the work, carrying expenses and likely listing proceeds for your actual house.
Dated city snapshot, rather than the entire Albuquerque metro area. These retail figures are not cash-offer prices, individual valuations or guaranteed sale-to-payment timelines.
OUR AS-IS PURCHASE POLICY
Sell It Exactly as It Sits in Albuquerque
We buy houses in Albuquerque in their current condition. You can compare an as-is offer before paying for cosmetic preparation, roofing or a cleanout. For a historic property, Albuquerque’s Historic Protection Overlay rules can require design approval for covered exterior work, so a repair plan needs more than a generic materials allowance.
Selling as-is still calls for accurate information. Share known conditions, available reports, permits and actual notices. For an adobe house, distinguish the structural wall from a stucco finish and bring any specialist findings. Our as-is selling guide explains the purchase choices. The agreement defines condition, access, inspection rights, possession and belongings left behind.
ADOBE, RAILROAD-ERA HOUSES AND POSTWAR EXPANSION
Selling a House in Albuquerque’s Neighborhoods
Building era and construction change the work behind a sale. The city’s historic guidelines and Hoffmantown history document distinct local housing examples. An early adobe building and a postwar subdivision house should not receive the same repair assumptions.
| Neighborhood / District | Housing Profile | Common Challenges We Resolve | Seller Scenario |
|---|---|---|---|
| Old Town | Historic adobe and stucco buildings reflecting Pueblo/Spanish Colonial and Territorial traditions. | Determine whether the actual walls are unfired adobe; moisture erosion and incompatible patches need a compatible specialist repair scope. | An owner compares the cost and scope of compatible restoration with selling the property in its present condition. |
| Huning Highland | Railroad-era houses developed from the 1880s through the 1920s, including Queen Anne, Italianate and Craftsman forms. | Review the building’s actual masonry, foundation, roof drainage and covered exterior-design requirements; the district alone does not prove a defect. | A seller weighs deferred maintenance and preservation work against a direct purchase. |
| Hoffmantown | Planned single-family subdivision developed near Wyoming and Menaul in the early 1950s during Albuquerque’s postwar expansion. | Identify which roofing, electrical and plumbing systems remain original or have been updated; age alone does not establish a particular material problem. | An owner compares an older-home update project with a written as-is offer. |
The city’s historic guidelines document adobe, brick, wood and stone. Exterior stucco does not identify the structural walls. They also describe brick or stone piers and masonry foundation walls, alongside modern slab or continuous-footing examples; inspect the actual property instead of assuming one citywide foundation system.
Historic roof guidance includes pitched gable and hip roofs and flat/parapet forms, with shingles, metal, tile and slate appropriate to particular buildings. Match drainage and covering to the house before pricing work. These examples do not establish dominant citywide material shares or a current median construction year.
Profiles describe documented local history. Inspection priorities and seller scenarios are practical inferences, not measured neighborhood defect rates or off-market seller motives.
REGIONAL ADOBE AND ROOF GUIDANCE · LOCALIZED SOIL AND FLOOD EXPOSURE
Adobe Moisture, Expansive Clay and Roof Drainage: What Matters Before an Albuquerque Sale
Actual adobe walls need compatible repairs
National Park Service adobe guidance explains how rain and rising ground moisture erode unfired adobe and weaken its clay bond. Cement patches or impermeable stucco can retain moisture behind the coating. Hollowing at a wall base, crumbling plaster, eroded parapets, bulging walls and significant cracks warrant professional review.
This concerns actual adobe construction in historic stock such as Old Town, rather than every stucco house. An adobe specialist can identify the material and compatible repair scope. That scope may affect price or credits; this is a practical inference, not an automatic insurance denial or a citywide defect count.
Expansive clay is a parcel-specific concern
The New Mexico geology publication from August 1992 identifies foundation-design concerns from expansive clay, including Armijo-series Rio Grande floodplain soils with high shrink-swell potential. Smectitic clay changes volume with moisture and can create differential foundation movement.
Recurring wall cracks, uneven floors or sticking doors can prompt investigation, but those signs alone do not diagnose the soil. Obtain the parcel’s soil evidence and a geotechnical or structural assessment where appropriate. The findings may change a repair allowance; the dated geologic account does not establish current citywide incidence or a blanket lender decision.
Roof form and drainage determine the review
National Park Service roof guidance explains why blocked drains or inadequate slope can create ponding and water backup; deteriorated flashing allows moisture into sheathing and roof framing. Look for standing roof water, clogged drains, ceiling stains, damp attic surfaces or decayed sheathing.
Review low-slope roofs with parapets and drains and pitched roofs with gutters and flashings on their own terms. Albuquerque’s flood resources address locally documented storm runoff. A roofing specialist can define the scope before you compare a repair project with selling as-is; neither roof form nor age alone establishes failure.
Flood and wildfire exposure follow the location
The city’s flood information identifies summer and early-autumn storm risk. Review the property’s mapping and drainage; a city address alone does not establish a flood-zone designation. New Mexico insurance guidance says runoff, groundwater and snowmelt flood damage need separate coverage from a standard homeowners policy.
The city’s emergency-preparedness guidance identifies wildfire concerns in the bosque and East Mountains. Exposure is location-specific. Ask the carrier about the actual property, access to fire protection and current coverage before assuming a retail buyer can insure it on the same terms.
Insurance eligibility requires a carrier-specific answer
The New Mexico Office of Superintendent of Insurance explains that older homes may fall outside preferred programs and that carriers may require heating, plumbing, wiring or roofing updates. Hydrant distance and fire-department quality affect protection class. OSI also identifies unpaid premiums, material misrepresentation, increased hazards and hazard-increasing code violations among cancellation grounds.
OSI’s July 14, 2025 FAIR Plan announcement describes a statewide availability backstop amid wildfire-related insurance concerns. It does not establish an Albuquerque market share or that every local property needs that program. No universal 15-year roof cutoff, mandatory four-point inspection or guaranteed adobe rejection is established by these sources.
If you are asking “Can I sell my house as is in Albuquerque?”, start with the actual construction and available findings. A buyer can review the work in the written offer and agreement. A visible condition alone does not prove that every conventional buyer will withdraw or that financing will fail.
PERMITS, EXTERIOR-DESIGN REVIEW AND ACTUAL NOTICES
Albuquerque Permits, Historic Approval and Municipal Records
Match alterations with the permit file
The Building Safety Division handles building and trade permits and construction inspections. Reconcile additions and alterations with their permits and inspection records; a search alone does not establish compliance. Code Enforcement separately handles zoning and property-maintenance violations.
Check covered historic exterior work first
Historic Protection Overlay requirements can call for a Certificate of Appropriateness for covered exterior work, with a limited ordinary-maintenance exception. Read the property’s actual overlay and proposed scope before committing to replacement materials or exterior changes.
The city’s information and records-request guidance identifies records channels and Code Enforcement lien-payoff information. Bring relevant notices and any actual municipal claim to the purchase review. An as-is sale does not certify earlier work or remove a recorded claim automatically.
To sell a house fast in Albuquerque, start with condition, occupancy and the records you already have. Our cash-offer calculation guide explains how known work enters the review. Explore New Mexico coverage, Rio Rancho and Santa Fe for another address.
EXPLORE A BUDGET BEFORE COMMITTING TO REPAIRS
AS-IS Repair Cost Estimator
Explore a budget before choosing repairs. These ranges are broad planning assumptions, not Albuquerque contractor quotes, an inspection, appraisal, cash offer or guarantee. Scope, labor, materials, permitting, access and concealed damage change the actual cost. Keep interior finish work separate from system allowances to reduce double counting.
Illustrative planning assumptions, not measured local prices. Interior rates cover finishes such as paint, flooring, and surfaces; the system add-ons below are outside that scope. Count a selected system only once.
Estimated planning range
$31,050–$51,750Interior: $27,000–$45,000; additional work: $0–$0; 15% contingency: $4,050–$6,750.
Specialty work needs a separate scope. Compatible adobe repairs and expansive-soil investigation require property-specific expertise. Adobe stabilization, foundation or structural work, geotechnical testing, drainage redesign, historic tile/slate/metal restoration, major moisture-damage remediation and work subject to unresolved permits or historic approval are outside these illustrative allowances.
COMPARE PROCEEDS, PROPERTY WORK AND THE WRITTEN TERMS
Cash Sale vs. Traditional Listing in Albuquerque
A traditional sale may produce a higher gross price. Commissions, seller closing costs, repairs, concessions and carrying expenses reduce the amount you keep. A direct cash sale generally prioritizes speed, certainty and convenience; compare actual net proceeds before deciding.
Cash home buyers in Albuquerque should explain price and terms in writing. The city’s 32-day median marketing period excludes closing, while compatible adobe work or a covered historic exterior project can change the preparation budget. A cash buyer still reviews condition and title; the agreement defines inspection, access and cancellation rights.
| Selling Dimension | Traditional Listing | Direct Cash Sale to MHIC |
|---|---|---|
| Gross Price | Potentially higher gross price | Usually lower than full retail value |
| Commissions | Agent commission may apply | No agent commission |
| Closing Costs | Seller closing costs may apply | MHIC pays normal closing costs |
| Property Condition | Repairs or buyer credits may be requested | Property sold as-is |
| Contingencies | Financing and appraisal contingencies | No buyer-financing contingency |
| Timeline | Longer and less predictable timeline | Seller selects an available closing date |
Compare Your Estimated Selling Options
Use our adjustable calculator to compare a traditional listing with a direct cash sale using your property’s estimated value and expenses.
Use the Net-Proceeds Calculator →MHIC pays normal closing costs and charges no purchase service fee or agent commission as stated in the written agreement. Seller mortgages, property taxes and other documented obligations still affect proceeds. Compare proof of funds, contingencies, assignment terms and the settlement statement. The actual agreement controls the purchase terms.
ACTUAL COURT PAPERS, SIGNING AUTHORITY AND TITLE REQUIREMENTS
Probate, Foreclosure Deadlines, and Complicated Title Situations in Albuquerque
Home-loan foreclosure: act on the served papers
The New Mexico Court of Appeals’ Lucas opinion explains that judicial foreclosure is required for home loans covered by the Home Loan Protection Act, Section 58-21A-6(E). New Mexico also has a Deed of Trust Act for eligible instruments; do not assume every possible loan or property follows the same route.
For the residential judicial route, the lender files a Complaint for Foreclosure in district court, followed by service of the Summons and Complaint. Albuquerque cases are ordinarily in the Second Judicial District Court for Bernalillo County. The state courts’ instructions specify 30 days after service to file an Answer. An offer discussion does not replace the response.
Cure, publication, confirmation and redemption are different stages
For an applicable Home Loan Protection Act loan, the right-to-cure notice must allow at least 30 days after delivery to cure before foreclosure or collection action. Under Section 58-21A-6(B), discussed in Lucas, the borrower may cure and reinstate before foreclosure transfers title; cure reverses default-based acceleration. The opinion associates transfer with the order approving the Special Master’s sale. Ask for the case-specific cure amount and confirmation status promptly.
Section 39-5-1, discussed in the Toland opinion, requires advance publication for four weeks of the sale’s time, place and property description. The actual Notice of Special Master’s Sale and court order identify the location or portal. No single fixed Bernalillo County residential mortgage-auction venue is established here.
Under the Legislature’s Section 39-5-18 amendment, the default judicial redemption period is nine months. The statutory sale date is the filing of the district-court order confirming the Special Master’s report. The district court’s foreclosure guidebook explains that the written mortgage can shorten redemption to at least one month under Section 39-5-19. Verify the instrument, decree, confirmation order and required payment with an attorney. These judicial mortgage rules do not describe a property-tax sale.
The state courts describe judicial foreclosure as taking several months; no current Bernalillo County median is established. Cure, service, publication and court-order requirements are separate. Loan terms, applicable federal servicing protections and case orders can affect timing; adding every interval does not create a universal deadline.
A cash offer or purchase contract does not pause foreclosure. A sale may be an option with lawful authority, enough time and sufficient proceeds or an approved resolution of claims. Bring the actual papers to the servicer and a New Mexico attorney immediately. Our foreclosure guide can help organize the purchase questions.
The $50,000 personal-property affidavit does not transfer a house
The court-published Affidavit of Successor in Interest under Section 45-3-1201 uses a limit of no more than $50,000 for the estate wherever located, less liens and encumbrances. The form uses an inclusive limit; the courts’ general FAQ describes it as under $50,000. Confirm eligibility against the current law and form rather than relying on that shorthand.
At least 30 days must have passed after death, and no personal-representative application or petition may be pending or granted in any jurisdiction. The entitled successor signs the sworn, notarized affidavit and presents it to the asset holder. It is an out-of-court collection process for money and qualifying personal property, rather than a probate hearing or judicial transfer order. Debt alone does not establish ineligibility; liens and encumbrances matter to valuation.
This affidavit does not convey land or an inherited house. Real estate requires another valid transfer route, potentially informal probate and an appointed personal representative. Have a probate attorney and the chosen title provider establish ownership and signing authority before relying on a sale date.
A surviving spouse has a separate homestead route
The courts’ surviving-spouse guidance describes an Affidavit of Transfer of Homestead to Surviving Spouse under Section 45-3-1205. For a qualifying primary residence, the full property-tax assessed value cannot exceed $500,000, and at least six months must have passed after death. This is separate from the $50,000 personal-property procedure.
The FAQ also requires no probate filed, the primary residence to be the only estate item requiring transfer, and the spouse to receive it as community property or through the decedent’s disposition. The surviving spouse signs a notarized affidavit and records it with the county clerk where the home lies. The court’s published sample adds certifications about competing rights, estate taxes and paid funeral, last-illness and unsecured debts. Obtain current instructions and complete every required certification; the dollar limit alone is not eligibility or immediate sale authority.
The Bernalillo County Court of Wills, Estates and Probate is at 415 Silver Ave. SW, 2nd Floor, Albuquerque, NM 87102. Check the appropriate court and jurisdiction for the estate. Our inherited-house guide explains the purchasing decisions after authority is established.
Title commitments identify the transaction’s requirements
New Mexico’s title-commitment rule requires the proposed exceptions and conditions to be delivered before completion with reasonable review time. Examine vesting and the actual requirements for mortgages, judgments, estate authority or other claims. A purchase contract does not remove them.
Relevant records include the Bernalillo County Clerk’s recorded-document portal, Treasurer’s parcel account, city records and municipal-lien payoff information and New Mexico court case access. An online index search is not a professional title opinion. The selected closer determines the transaction’s actual searches and releases; no universal HOA-estoppel form is established here.
Qualified advice remains separate from purchasing. MHIC provides direct purchasing solutions, not legal, tax, probate, financial or foreclosure-defense advice. Consult a New Mexico attorney, court clerk, the property’s county treasurer, a tax professional or another qualified adviser. A purchase does not guarantee foreclosure prevention, court approval, lien removal, tax forgiveness or title clearance.
THE PARCEL, THE ACTUAL BILL AND THE DATED CLOSING BALANCE
Albuquerque Property Taxes: Payment Windows and Separate Late Charges
The Bernalillo County Treasurer’s Office handles property taxes for Bernalillo County parcels. The ordinary payment calendar begins the first-half window November 10, with a December 10 deadline to avoid late charges. The second-half window begins April 10, with an ordinary May 10 deadline the following year. Read the actual bill and announced tax-year dates for adjustments.
Interest and penalty are separate. The county FAQ identifies 1% monthly interest and a 1% monthly penalty, with the penalty capped at 5% of unpaid tax and a statutory $5 minimum. The state’s property-tax rules address months or fractions of a month and permit a county to suspend the minimum-penalty requirement for a particular year by the specified resolution. Ask the Treasurer for the actual dated balance.
A changed closing date can change the payoff. The chosen closer checks the parcel account and agreed proration; the purchase itself does not forgive tax, penalty or interest. Surrounding communities may use another county’s office, so a mailing city alone is not enough to identify the account.
FROM THE AGREEMENT TO A REVIEWED, FUNDED SETTLEMENT
What Happens Between Accepting Your Cash Offer and Getting Paid in Albuquerque?
This is an illustrative expedited sequence, not a guaranteed five-day closing or immediate payout. New Mexico’s title-commitment requirements, down-date review and community-property signing rules change the work behind a proposed date. The closer must confirm authority, title requirements, payoffs, execution, recording readiness and funded disbursement.
Day 0 — Agreement and purchase contract
Agree on price, present condition, access, inspection rights, occupancy, possession, contingencies, cost allocation and an available closing date. MHIC charges no purchase service fee or agent commission and pays normal closing costs as stated in the agreement; seller debts remain separate. Share known issues, available specialist findings, approvals and notices. Confirm lawful signers, including estate authority and any community-real-property spousal joinder that applies.
Days 1–2 — Open title and review the commitment
Confirm the chosen title/escrow provider. Old Republic Title’s New Mexico directory identifies 6707 Academy Road NE, Suite C, Albuquerque, NM 87109; it is a local provider example, not a verified MHIC partner or endorsement. Review the title commitment’s vesting, exceptions and requirements. Check relevant recorded interests, court or estate records, taxes and municipal claims. Bring available permits and specialist reports for the actual building.
Days 2–4 — Payoffs, releases and a closing update
The closer obtains dated mortgage payoffs and required release documents, checks the parcel tax account and resolves actual commitment requirements. Bernalillo County’s separate monthly interest and penalty can change the balance. Follow up on any city lien-payoff requirement. New Mexico’s down-date definition concerns a later public-record search and examination to identify intervening title matters. Unresolved estate authority, a disputed claim or a missing release can extend the schedule.
Day 5, if ready — Authorized deed, recording and funded disbursement
New Mexico recognizes a statutory warranty-deed form; the agreement, authority and title insurer determine the actual conveyance instrument. The grantor signs, and an ordinary deed requires notarial acknowledgment for recording. For community real property, confirm the required spousal joinder and any valid exception or representative authority. Bring government-issued photo identification and arrange spouse participation with the escrow officer.
For Bernalillo County land, record qualifying instruments with the County Clerk. The closer follows the escrow instructions and confirms collected funds and disbursement conditions. Old Republic’s New Mexico checklist documents seller wire instructions. State rules define collected funds and the availability of received Federal Reserve wires; other deposits have their own collection timing. Confirm when proceeds can be released and when your bank makes them usable.
Signing, title coverage, funding and utilities
Old Republic’s New Mexico checklist documents scheduled signing with photo identification and final documents, with spouse attendance or prior arrangements discussed with escrow. Confirm lawful signing arrangements and whether an attorney’s involvement is needed for your circumstances. The checklist does not establish an attorney exemption or one mandatory physical-closing practice for every transaction.
New Mexico regulates owner and loan title policies. The commitment identifies exceptions and requirements for review before completion. Premium and cost allocation follow the agreement and settlement statement; no universal Albuquerque seller-pays allocation is established here.
The New Mexico Secretary of State’s journal guidance requires notarial journal entries and ten-year retention after the last act, subject to stated exceptions. Its required-entry list does not include a thumbprint. Let the notary and title provider confirm execution and identification for the actual instrument rather than assuming an extra witness or thumbprint rule.
The provider’s checklist describes a financed transaction in which seller proceeds wait for lender funding approval. A cash purchase uses its own escrow and funding instructions. Signing alone does not guarantee immediately usable funds; confirm the actual release conditions.
PNM’s service information identifies the primary electricity provider for greater Albuquerque. Coordinate the actual account and possession date separately from title. Ordinary utility-account handling is not identified here as a title lien or a substitute for tax and recorded-claim review.
TERMS YOU MAY ENCOUNTER IN THE LOCAL PROPERTY FILE
Albuquerque Real Estate & Legal Terms Homeowners Should Know
- Affidavit of Successor in Interest
- New Mexico's sworn personal-property collection procedure for a qualifying small estate; it does not by itself convey the deceased owner's house.
- Affidavit of Transfer of Homestead to Surviving Spouse
- A separate New Mexico affidavit route for an eligible surviving spouse to record title to the homestead after satisfying §45-3-1205; do not apply the personal-property affidavit's limit.
- Redemption period
- New Mexico's post-foreclosure opportunity to recover the property by the required payment. The mortgage may shorten nine months to at least one month; check the instrument and confirmation order.
- Historic Protection Overlay / Certificate of Appropriateness
- Albuquerque's historic-design review for covered exterior work. Check approval requirements before pricing an exterior renovation; ordinary maintenance has a limited exception.
- Down date
- The New Mexico title-rule term for the effective date of a later public-record search and examination, helping identify intervening title matters before closing.
CITY, SUBURBAN AND SURROUNDING RESIDENTIAL ADDRESS REVIEW
Albuquerque and Nearby Communities Within Our 75-Mile Review Area
We review residential submissions in Albuquerque and the listed surrounding New Mexico communities. The radius starts at the Census Bureau’s January 1, 2026 Albuquerque city-boundary centroid, 35.1053263, −106.6464417. This defined municipal centroid is different from a downtown landmark or the Census internal point. Distances are straight-line reference distances, rather than driving distance.
Regional overview centered on Albuquerque’s Census city centroid. Select a community for its Google map and approximate straight-line reference distance.
Nearby communities include Rio Rancho, Los Ranchos de Albuquerque, Corrales, Bernalillo, Placitas in Sandoval County, Los Lunas, Bosque Farms, Peralta, Belen, Rio Communities, Tijeras, Edgewood, Moriarty, Estancia and Santa Fe. The broader list also includes nearby residential submarkets and Census-designated places.
All 195 surrounding geographic centroids are within 75 miles using the 2026 Census files for incorporated places and Census-designated places. Names shared by different places are distinguished by county. Municipal boundaries and postal areas can extend beyond their centroids. The map does not draw an exact service boundary; submit the physical address to confirm distance, county, land status, ownership and purchase eligibility.
Browse all 195 nearby communities
A community name or ZIP code does not establish saleable title or transfer authority. Albuquerque permit and overlay rules concern city parcels; surrounding jurisdictions have their own offices. See our New Mexico coverage, Rio Rancho page and Santa Fe page for another address.
ALBUQUERQUE HOMEOWNER QUESTIONS
Frequently Asked Questions
Which residential ZIP codes do you cover in Albuquerque and nearby communities?
Albuquerque’s listed residential ZIP and boundary-overlap coverage includes 87102, 87104, 87105, 87106, 87107, 87108, 87109, 87110, 87111, 87112, 87113, 87114, 87116, 87120, 87121, 87122, 87123. The table covers residential delivery codes in the source lists or geographic overlaps for all 196 shown communities. PO-box-only, unique institutional and zero-residential-delivery codes are excluded.
Excluded Albuquerque mailing codes include 87101, 87103, 87115, 87119, 87125, 87131, 87151, 87153, 87154, 87158, 87176, 87181, 87184, 87185, 87187, 87190, 87191, 87192, 87193, 87194, 87195, 87196, 87197, 87198, 87199. An excluded mailing code does not itself exclude a house from consideration. Where a listed community has only a PO-box or institutional mailing code, submit the physical property address.
Community names link to published boundary/ZIP lists or, where needed, the Census ZIP Code Tabulation Area layer. Census ZCTA overlaps approximate postal geography; they are not USPS delivery-route boundaries. Delivery was checked against ZIP-Codes.com’s USPS delivery profiles. Codes can cross communities and counties and extend beyond the radius. These lists describe the shown community and overlap areas, rather than every route in an exact circle. Confirm the physical address, land status and ownership before relying on coverage.
How can I sell my house for cash in Albuquerque?
Call (866) 651-6617 or send your address, known condition, occupancy and timing. Compare the written price and terms with likely listing proceeds after work and expenses. Share any adobe or foundation findings, roof-drainage history, available permits, historic approvals, tax bills and ownership or estate papers. Title requirements, lawful signers, payoffs and funding determine whether the proposed closing date works.
Can I sell my house as is in Albuquerque without repairs?
Yes. MHIC reviews houses in their current condition, including deferred maintenance, roof leaks and unfinished work. Share known conditions and available reports. Actual adobe walls, suspected soil movement and covered historic exterior work may need specialist or permit review. An as-is purchase does not certify earlier alterations or automatically remove a municipal or recorded-title claim.
What is the hardest month to sell a house?
The Albuquerque snapshot does not compare a complete year of monthly results, so it cannot establish a hardest month. Its 32-day median marketing period covers the three months ending August 2026. Compare demand for your house’s location and condition with preparation costs, carrying expenses and moving plans rather than choosing a month from an unsupported ranking.
Are home prices dropping in Albuquerque?
The three-month city snapshot ending August 2026 shows a $359,762 median sale price for all home types, up 1.3% year over year. It does not show a year-over-year decline in that median. The same report shows 37.3% of homes with asking-price drops; a listing price reduction is different from a falling citywide median. These figures do not establish the value or future price of your individual house.
How do I compare cash home buyers in Albuquerque?
Request written offers from buyers who can identify who will purchase and fund the property. Compare proof of funds, price, inspection and cancellation rights, assignment terms, cost allocation and timing. Check customer reviews and identify the title/escrow provider. Compare net proceeds after mortgages, county taxes and other documented obligations rather than relying on a promised percentage of market value.
Can a cash offer stop an Albuquerque foreclosure?
No. An offer or purchase contract does not pause foreclosure. A sale may be an option with lawful authority, enough time and sufficient proceeds or an approved resolution of claims. Covered Home Loan Protection Act home loans use judicial foreclosure; the served Complaint, cure requirements and confirmation order matter. The courts specify 30 days after service to answer. Have the servicer and a New Mexico attorney review the actual papers promptly.
Can the $50,000 Affidavit of Successor in Interest transfer an inherited house?
No. New Mexico’s personal-property collection affidavit does not convey land or a house. The court-published form uses a limit of no more than $50,000 for the estate wherever located, less liens and encumbrances, with at least 30 days after death and no pending or granted representative appointment in any jurisdiction. An inherited house needs another valid transfer route and verified signing authority.
Can a surviving spouse transfer an Albuquerque homestead by affidavit?
A separate Section 45-3-1205 procedure may apply to a qualifying primary residence. The courts’ guidance uses a full property-tax assessed value no greater than $500,000 and a wait of at least six months after death. No probate may be filed; the residence must be the only estate item requiring transfer, and the spouse must receive it as community property or through the decedent’s disposition. Complete all required certifications, notarization and county recording. The dollar limit alone is not eligibility or sale authority.
Do adobe walls, foundation cracks or an old roof prevent an as-is sale?
They do not establish an automatic sale failure. Determine the actual wall construction, document moisture and roof drainage, and obtain soil or structural findings where appropriate. Stucco does not prove adobe construction; cracks do not diagnose expansive clay. Ask the insurer about the actual house and required updates. The property-specific scope and agreement determine how the buyer addresses the condition.
How soon can I sell my Albuquerque house fast and receive payment?
Request written terms and have the chosen closer confirm authority, title requirements, applicable disclosures, payoffs, lawful signing, recording readiness and funded disbursement. The Day 0–5 sequence is illustrative rather than guaranteed. An estate issue or missing release can take longer. Confirm the wire or other agreed disbursement method, collected funds, release conditions and bank availability before relying on usable proceeds.
Who pays closing costs when MHIC buys my Albuquerque house?
MHIC pays normal closing costs and charges no purchase service fee or agent commission as stated in the written agreement. Seller mortgages, county taxes and other actual obligations still affect proceeds. Title-policy premium allocation follows the agreement and settlement statement; no universal Albuquerque allocation is established here. Confirm tax payoffs, any municipal claim and the actual funding conditions with the selected closer.
YOUR PROPERTY, YOUR DECISION
Request a Cash Offer for Your Albuquerque House
Start with the address, known condition, occupancy and moving plans. Include available adobe or foundation findings, roof and drainage records, permits, historic approvals and ownership or estate papers. The property-specific work and New Mexico title and signing requirements help determine the price and a workable closing date.
Request Your No-Obligation Cash Offer →
Prefer to talk? Call (866) 651-6617, our toll-free number. Learn about our direct buying process and New Mexico coverage. Compare the written terms and decide whether the purchase fits your plans.
PRIMARY OFFICES AND RECORDS FOR YOUR PROPERTY
Official Albuquerque Homeowner Resources
Use the physical property’s county and municipality when contacting these offices. A postal city alone does not identify the permit, tax, recording or court jurisdiction.