
A Higher Sale Price Can Still Come With a Longer Wait
Redfin’s Tupelo city report, retrieved October 15, 2026, gives these price and days-on-market figures for the three months ending September 2026. A higher city median does not establish the value of your house, and marketing time is not the same as the full time to receive sale proceeds.
The report calls the market somewhat competitive. Its Compete Score of 62 uses a trailing 12-month period; the separate roughly 26-day time-to-pending measure is not the 40-day median DOM series. Compare the price your home could support with the repairs and carrying expenses needed to reach that price.
Start with our guide to how cash offers are calculated, then compare the actual written terms.
Sell It Exactly as It Sits in Tupelo
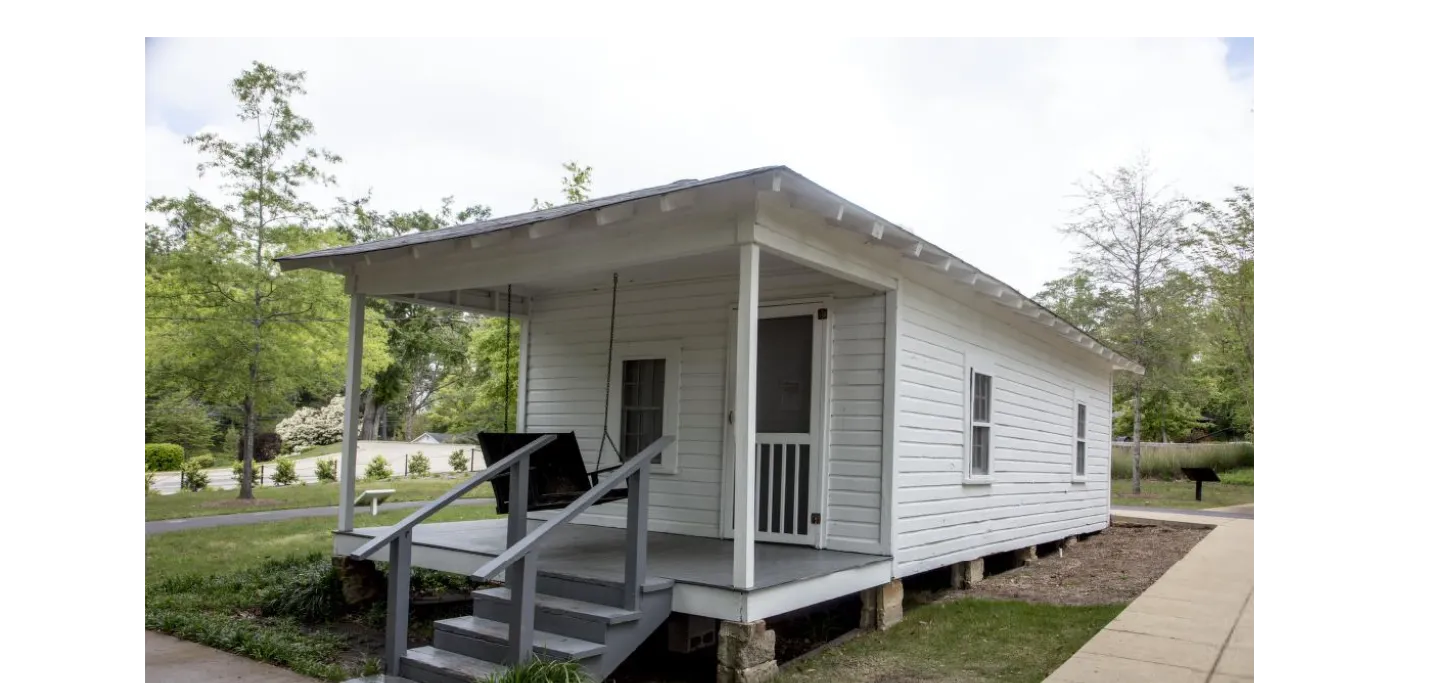
We buy houses in Tupelo, MS in their current condition. You can sell a house as-is in Tupelo without completing a cosmetic refresh first. For an older Mill Village cottage, that can mean comparing an offer before taking on the roofing, porch and pier maintenance described in the city’s preservation guidelines.
Skip interior touch-ups and exterior repainting.
Leave stained carpet, worn hardwoods or cracked tile.
We buy with active leaks, missing shingles or an aged roof.
Avoid professional staging and pre-sale decluttering costs.
Take what you want; leave unwanted furniture, trash and clutter behind.
Skip open houses, lockboxes and repeated buyer walk-throughs.
We still need enough information and agreed access to evaluate the property. Put the as-is condition and any items being left behind into the purchase agreement. Read our as-is selling guide before comparing offers.
Selling a House in Tupelo’s Neighborhoods
Historic inventories document very different homes within Tupelo. They support a closer look at the actual roof, framing and foundation; they do not establish a citywide median construction year or prove that a particular home has defects.
| Neighborhood / District | Housing Profile | Common Challenges We Resolve | Seller Scenario |
|---|---|---|---|
| Mill Village Historic District | Circa 1900–1940 mill-worker housing: chiefly one-story wood-frame shotgun and L-shaped cottages, with some 1920s bungalows. | Evaluate roof deterioration, porch wood rot and moisture or movement at piers. An as-is purchase can let the seller leave the agreed repair work to the buyer. | If you are weighing restoration against selling, compare the complete repair scope with the cash offer before starting work. |
| South Church Street Historic District | 1900–1929 district, with substantial construction in 1911–1923; vernacular/Craftsman bungalows, foursquares and Colonial Revival houses. | Review original siding, porches and weatherproofing using the city’s maintenance guidance. These are screening priorities, not evidence of unusual defect frequency. | If exterior work is already on your list, obtain a defined scope before assuming fresh paint will address the underlying condition. |
| Highland Circle Historic District | Circa 1900–1955 homes, including Craftsman, Tudor Revival and Colonial Revival designs; wood siding, brick/brick veneer and some stucco/stone. | The inventory documents older asphalt-shingle roofs, wood windows and brick-pier foundations. Reviewing their condition is an inspection inference, not a measured defect rate. | If a retail sale depends on repairs, compare that work and its timing with an offer for the current condition. |
These inventories document wood framing, weatherboard/shingle siding, brick exteriors, raised brick-pier foundations and crawlspaces in older stock. Gable and hip roofs include asphalt shingles and selected tile/slate roofs. They do not establish current citywide material or foundation shares. No neighborhood-specific pattern of seller motivations has been verified.
What Needs a Closer Look Before You Spend on Repairs?
Termite evidence in wood framing
Mississippi State University Extension documents eastern subterranean termites statewide. They forage from moist soil, build mud tubes across exposed masonry, and consume structural wood. Wood-frame cottages over crawlspaces and slab homes with concealed wood entry points can both warrant review.
Look for mud tubes, indoor swarmers, pinholes or soil-lined galleries in damaged wood. Treatment and repair records can help a buyer understand the scope. A lender may request a wood-destroying-insect report; that is not a universal legal requirement for every cash sale. This is a regional tendency, not proof of infestation at your address. Isolated Formosan detections near Tupelo do not establish persistent citywide prevalence.
Floodwater and concealed moisture
Flood exposure is parcel-specific. EPA flood-cleanup guidance explains how wet porous materials retain moisture and support mold; drywall, insulation and other materials that cannot be dried may require removal. Water marks, mud, lifted flooring and damp finishes justify a defined remediation scope.
Use Tupelo’s flood-zone and floodway maps before planning work. The city states that designated flood-zone development must be two feet above the designated flood elevation. Ask what applies to your project; a mapped zone does not describe every home in a neighborhood.
Mapped suspect soils
Tupelo also maps suspect-soil areas and requires a geotechnical report plus three feet of fresh buildable fill where applicable. A map designation is a development constraint, not proof that every existing foundation is defective.
Confirm the parcel and proposed scope with the city before pricing structural work. A conventional buyer may seek specialist findings or a repair allowance when a condition remains unresolved; an as-is offer is another way to compare the expense. Citywide Yazoo-clay conditions and coastal storm surge have not been established for Tupelo.
Roofs, storm history and coverage
The National Weather Service documents Tupelo’s April 28, 2014 tornado. That establishes local exposure, not present damage at your house. Existing roof inspections, claim documents and repair records can make a condition discussion more useful.
Mississippi Insurance Department Bulletin 2024-2 limits roof-age-only issuance/renewal refusals: under 15 years, age alone cannot be the basis; at 15 years or older, an authorized inspection finding at least five useful years remaining can protect against age-only refusal. Exceptions and poor-quality or unrepaired-damage provisions still matter. The bulletin also limits certain roof-type restrictions, subject to the law’s exceptions. Coverage is not guaranteed.
Condition findings can lead a conventional buyer to request documentation, renegotiate repair allowances, or reconsider the purchase. Depending on the lender or insurer, unresolved issues may also affect financing or coverage; a defect does not automatically cause either to fail. The Mississippi Insurance Department describes a competitive homeowners market with property- and insurer-specific eligibility. Standard homeowners policies exclude flood; coverage for that peril is separate. The Mississippi Residential Property Insurance Underwriting Association is a listed last-resort option when conventional coverage cannot be obtained.
Rental or unfinished work?
Tupelo’s rental checklist addresses water-tight roofs/foundations, rotten or buckling materials, exposed or makeshift wiring, GFCI protection, leaks, mold, pests, detectors and heating. These are rental-compliance checkpoints, not mandatory inspection requirements for every owner-occupied sale. These checkpoints do not establish the frequency of inspection failures in the city.
For unfinished or undocumented work, ask the Department of Development Services: Building Division, 662-841-6411; Permitting, 662-841-6510; and Code Enforcement. Confirm what applies before spending money or assuming an as-is sale settles a permit or enforcement question.
AS-IS Repair Cost Estimator
Older brick-pier homes and flood-affected materials require different investigations, as the Highland Circle inventory and EPA guidance illustrate. Use this tool to explore a budget range before deciding whether to repair or request an as-is offer.
These are editable planning assumptions, not measured Tupelo contractor prices. This is not an inspection, appraisal, contractor quote or guarantee. Actual costs can vary substantially with scope, materials, labor, permitting, access and concealed damage.
When comparing cash buyers for houses in Tupelo, ask how the actual condition affects the offer. This estimator is not a deduction schedule and does not calculate an MHIC offer.
Cash Sale vs. Traditional Listing in Tupelo
A traditional sale may produce a higher gross price, but commissions, seller closing costs, repairs, concessions and ongoing holding expenses reduce the amount you ultimately keep. A direct cash sale generally prioritizes speed, certainty and convenience rather than the highest possible gross price.
For Tupelo, the 40-day median marketing period in the report for the three months ending September 2026 is one useful planning reference, not a prediction for your address. Compare cash home buyers in Tupelo using the written purchase price, remaining conditions and seller obligations.
| What to compare | Traditional listing | Direct cash sale with MHIC |
|---|---|---|
| Gross price | Potentially higher gross price | Usually lower than full retail value |
| Commissions | Agent commission may apply | No agent commission |
| Closing costs | Seller closing costs may apply | MHIC pays normal closing costs |
| Property condition | Repairs or buyer credits may be requested | Property sold as-is |
| Contingencies | Financing and appraisal contingencies | No buyer-financing contingency |
| Timeline | Longer and less predictable timeline | Seller selects an available closing date |
Individual listing contracts vary, including cash offers received through an agent. A direct purchase still requires agreed due diligence and acceptable title. Your mortgage, tax balances and other seller obligations remain part of the settlement calculation.
Compare Your Estimated Selling Options
Use our adjustable calculator to compare a traditional listing with a direct cash sale using your property’s estimated value and expenses.
Use the Net-Proceeds Calculator →Probate, Foreclosure Deadlines, and Complicated Title Situations in Tupelo
A cash buyer cannot replace the legal authority needed to sign a deed. For an inherited Lee County property, the local court resource is Lee County Chancery Court, First Chancery Court District, at 200 West Jefferson Street, Tupelo, MS 38804. The Lee County Chancery Clerk handles land recording; recording a document and establishing marketable title are different tasks.
Inherited property: the simplified procedure that can involve a house
Mississippi Code § 91-5-35 allows a qualifying will to be admitted as muniment of title only, establishing title to Mississippi real estate devised by the will without full estate administration. The Mississippi probate estate, excluding real property and § 91-7-117 exempt property, must not exceed $75,000, and all known decedent/estate debts, including estate and income taxes, must be paid.
- A will devising the Mississippi real property is required. This is not an automatic route for an intestate estate.
- A sworn petition and court admission of the will are required; appointment of an executor or administrator is not necessary for this procedure.
- A serving personal representative may petition, including one serving in a foreign jurisdiction. Otherwise, the surviving spouse and Mississippi-realty devisees sign, excluding mere contingent remaindermen; representative signing is permitted under § 91-8-303.
- Section 91-5-35 states no fixed post-death waiting period. That does not establish an immediate closing date.
The separate § 91-7-322 affidavit procedure concerns personal property only: a net probate estate of no more than $75,000, at least 30 days after death, with no representative pending or appointed. That affidavit does not transfer the house. Ask a Mississippi real estate or probate attorney which procedure and signatures fit the estate before committing to a sale. Our inherited-house guide can help you organize the property discussion.
Mortgage foreclosure: work from the actual sale notice
Mississippi permits power-of-sale nonjudicial foreclosure and also recognizes judicial enforcement. For the nonjudicial route, a Trustee’s Notice of Sale or Substituted Trustee’s Notice of Sale uses newspaper publication and courthouse posting rather than a foreclosure complaint. As explained in Snell v. 21st Mortgage Corp., discussing §§ 89-1-55 and 89-1-59, the state notice stage requires three consecutive weeks of advertisement before sale and courthouse posting for that period, identifying the original mortgagor(s).
That three-week period is not the full default-to-sale timeline. Federal Regulation X generally bars the first required foreclosure notice or filing on a covered mortgage until the loan is more than 120 days delinquent, with exceptions and loss-mitigation protections. Additional notice and cure terms in the deed of trust also matter under the Mississippi Title Examination Standards. No authoritative Tupelo median elapsed foreclosure timeline has been verified.
Before sale, § 89-1-59 permits reinstatement by paying installments actually past due plus applicable costs, attorney/trustee fees and advanced taxes or insurance with interest; insufficient partial payments need not be accepted. Obtain an exact reinstatement or payoff figure from the responsible party. The court’s discussion of reinstatement explains why sending an arbitrary partial payment is not the same as curing the default.
An auction-provider listing advertises Lee County trustee sales at the front door of the Lee County Justice Center, 200 West Jefferson Street. It is not a universal county venue rule: confirm the particular door, date and time in the controlling notice. The title standards identify no borrower redemption period after a valid mortgage foreclosure sale; separate federal lienholder rights may apply.
An off-market cash sale is one possible option only if the owner has authority to sell and there is enough time to complete closing before the scheduled sale. Contact the trustee, servicer and a qualified attorney promptly about your actual deadline. An offer or signed purchase contract does not itself postpone an auction or guarantee foreclosure prevention. Our foreclosure selling guide explains the purchasing discussion.
Back taxes: a different sale and redemption process
The Lee County Tax Collector’s Office, Crystal Heatherly, 662-432-2200, is the collecting authority. The Mississippi Department of Revenue states that prior-year property taxes are payable by February 1, subject to applicable weekend/legal-holiday extensions; unpaid taxes become delinquent after the deadline. Under § 27-41-9, late interest is 0.5% per month or fractional month, calculated from February 1 when paid late.
Lee County’s tax sale is conducted online through GovEase on the last Monday in August. The county page gives conflicting starting times, so use the annual notice. Tax-sale redemption generally runs for two years and is handled through the Chancery Clerk. This is separate from mortgage foreclosure.
The Mississippi delinquent-tax manual describes redemption amounts including taxes and costs, 5% damages on the taxes, and 1.5% interest per month or fractional month on the statutory amounts. Ask the clerk for the exact dated redemption payoff rather than estimating it from an old tax bill.
Heirship questions, recorded claims and code matters
A closing professional can examine ownership and relevant recorded claims through Lee County’s land-record system, then identify the documents or payoffs needed for the transaction. Missing heirship documentation, back taxes or a possible municipal enforcement claim require individual review. Ask Tupelo Code Enforcement about an actual notice; do not assume every violation is a recorded lien or that a sale automatically removes it.
My House Into Cash provides direct purchasing solutions, not legal, tax, probate, foreclosure-defense or financial advice. Consult the court clerk, tax collector, a Mississippi real estate attorney or a tax professional about your circumstances. We do not guarantee court approval, lien removal, tax forgiveness or title clearance.
What Happens Between Accepting Your Cash Offer and Getting Paid in Tupelo?
The schedule below is illustrative, not a verified local turnaround or a five-day guarantee. The calendar depends on title, signing authority, payoffs, document readiness and funding. A probate issue or unresolved recorded claim can move closing beyond these labels.
- Day 0 — mutual agreement
Finalize the purchase contract
Agree on price, as-is condition, included items and the available closing date. MHIC charges no seller service fee or agent commission and pays normal closing costs under the agreement. Existing mortgages, taxes and other seller obligations still affect proceeds. A documented Tupelo purchase agreement includes current-year tax proration; allocations should be written into your own contract.
- Days 1–2 — target for starting due diligence
Examine title and identify property-specific questions
The closing professional reviews ownership, legal descriptions, deeds of trust, releases, easements and relevant claims. The Lee County portal warns that its online index is not the official record. Mississippi title standards generally use at least 32 years for one-to-four-family residential title, extending earlier for referenced defects, with relevant tax, judgment and lis-pendens records also examined.
Local attorney-led settlement is demonstrated by the independent firm B. Bronson Tabler, P.A., which offers detailed title searches, title certification/curative services, closing documents and owner’s/lender’s title insurance. Its Tupelo office is at 322 W Jefferson Street, Tupelo, MS 38804; 662-840-8400. It is a local resource, not a verified MHIC partner. Your transaction’s provider, coverage and payment terms are confirmed separately; this example does not establish a universal attorney-only closing rule.
Ask the settlement agent which municipal, association or utility inquiries apply. No universal Tupelo municipal-lien certificate, HOA-estoppel or utility-lien procedure has been verified. Tupelo Water & Light is the municipal electricity/water utility; verify the provider at the service address. An ordinary electric balance is not being represented here as a title lien.
- Days 2–4 — conditional on responses and documents
Obtain payoffs and address title requirements
Get dated mortgage payoffs and the Tax Collector’s current tax balance; after a tax sale, obtain redemption figures through the Chancery Clerk. The professional handling settlement identifies releases, heirship documentation or other curative work needed for the actual recorded issue. The title standards guide that review, but documents and approvals may take longer than this example.
- Day 5 — possible target only when everything is ready
Sign, record and receive cleared proceeds
A warranty deed is documented in the Tupelo purchase-agreement example; general/special warranty and quitclaim deeds also appear in Mississippi title practice. The contract and title review determine the correct instrument. The Lee County Chancery Clerk’s checklist requires notarized seller signatures, legal description/indexing instructions and seller, buyer and preparer contact details. Its ordinary notarized-deed checklist specifies no separate subscribing-witness signatures; special execution circumstances need individual review.
For an owner-occupied exempt homestead, a married owner living with a spouse generally needs that spouse’s joinder even if the spouse is not on title, subject to exceptions reviewed under the homestead-spouse title standards. Mississippi’s notarial law, § 25-34-37, requires a contemporaneous journal; the specified entries do not include a mandatory real-estate thumbprint.
The deed is recorded with the Lee County Chancery Clerk. Documented regional settlement practice allows proceeds by bank wire or settlement-company check after funds and closing conditions clear. Confirm the actual release time and any remote/mail-away signing options with your closing provider. Signing is not a guarantee of immediate or same-day payout.
Explore Our 75-Mile Tupelo Service Area
Our service-area reference uses a 75-mile straight-line radius from Tupelo’s Census city centroid at 34.269142, −88.7318167. It is not a driving-distance boundary. The January 1, 2026 Census place file places all 18 communities below within that radius using city-centroid distances. Submit the physical address to confirm buying availability and the appropriate closing arrangements.
Use the Google map to explore Tupelo and the surrounding region. The 75-mile service-area reference is measured separately; this embedded map does not display a radius overlay.
Open Tupelo in Google Maps →. The map identifies the city for geographic reference; it does not mark an MHIC office.
For broader coverage, see our Mississippi home-selling page. Confirm buying availability by physical address, including for properties near a state line.
Tupelo Cash Home Sale FAQs
Which residential ZIP codes do you cover in Tupelo and the surrounding area?
Tupelo’s principal residential postal areas are 38801 and 38804; nearby homes may use Belden 38826 or Saltillo 38866 mailing addresses. We review the physical property address rather than treating a postal name as a city boundary. The Mississippi Secretary of State ZIP directory identifies Tupelo’s 38802 and 38803 as PO-box codes, so they are not listed as separate residential neighborhoods.
| City / postal area | Residential ZIP reference |
|---|---|
| Tupelo | 38801, 38804 |
| Belden | 38826 |
| Saltillo | 38866 |
| Verona | 38879 |
| Plantersville | 38862 |
| Shannon | 38868 |
| Guntown | 38849 |
| Mooreville | 38857 |
| Mantachie | 38855 |
| Nettleton | 38858 |
| Pontotoc | 38863 |
| Baldwyn | 38824 |
| Fulton | 38843 |
| Blue Springs | 38828 |
| Sherman | 38869 |
| Ecru | 38841 |
| New Albany | 38652 |
| Amory | 38821 |
| Booneville | 38829 |
| Houston | 38851 |
| Aberdeen | 39730 |
| Ripley | 38663 |
| Oxford | 38655 |
| Corinth | 38834 |
| Houlka | 38850 |
| Marietta | 38856 |
| New Site | 38859 |
| Okolona | 38860 |
| Randolph / Sarepta postal area | 38864 |
| Rienzi | 38865 |
| Smithville | 38870 |
| Thaxton | 38871 |
| Tishomingo | 38873 |
| Tremont | 38876 |
| Vardaman | 38878 |
For a rural route or a different mailing name, send the street address. A missing name in this table does not mean the property is excluded. Check the current address and ZIP with USPS.
What other postal areas fall within the broader 75-mile service-area reference?
This expanded reference includes all 178 Census ZIP Code Tabulation Areas whose 2025 Gazetteer internal reference points fall within 75 straight-line miles of the Tupelo center used on this page. It supplements the residential community table above; it is not an assertion that every listed ZIP is exclusively residential or that every property is eligible.
Method: great-circle distances from 34.269142, −88.7318167 to the internal coordinates in the 2025 Census national ZCTA Gazetteer. ZCTAs are statistical areas, not USPS delivery boundaries; a boundary ZIP can extend inside and outside the circle, and a ZIP absent from this point-based list can still touch it. Confirm coverage by physical address. See the Census Gazetteer documentation.
Mississippi — 113 reference areas
38601, 38603, 38606, 38610, 38611, 38619, 38620, 38625, 38627, 38629, 38633, 38635, 38642, 38647, 38650, 38652, 38655, 38658, 38659, 38661, 38663, 38666, 38668, 38673, 38674, 38677, 38683, 38685, 38801, 38804, 38821, 38824, 38826, 38827, 38828, 38829, 38833, 38834, 38838, 38839, 38841, 38843, 38844, 38846, 38847, 38848, 38849, 38850, 38851, 38852, 38855, 38856, 38857, 38858, 38859, 38860, 38862, 38863, 38864, 38865, 38866, 38868, 38869, 38870, 38871, 38873, 38876, 38878, 38879, 38901, 38913, 38914, 38915, 38916, 38922, 38925, 38927, 38929, 38948, 38949, 38951, 38953, 38961, 38965, 39701, 39702, 39705, 39730, 39735, 39736, 39737, 39739, 39740, 39741, 39743, 39744, 39746, 39747, 39750, 39751, 39752, 39753, 39755, 39756, 39759, 39762, 39766, 39767, 39769, 39771, 39772, 39773, 39776
Alabama — 41 reference areas
35461, 35481, 35542, 35543, 35544, 35545, 35548, 35549, 35552, 35554, 35555, 35559, 35563, 35564, 35565, 35570, 35571, 35573, 35574, 35575, 35576, 35577, 35581, 35582, 35585, 35586, 35592, 35593, 35594, 35616, 35630, 35632, 35633, 35646, 35651, 35653, 35654, 35660, 35661, 35674, 35677
Tennessee — 24 reference areas
38008, 38039, 38042, 38044, 38046, 38052, 38057, 38061, 38066, 38067, 38076, 38310, 38315, 38326, 38327, 38339, 38357, 38365, 38367, 38372, 38375, 38376, 38379, 38471
How do I sell my house for cash in Tupelo?
Call My House Into Cash or send the property address, condition and preferred timing through our contact page. Review the written offer and seller obligations, then choose an available closing date after the closing professional confirms title and signing authority.
How quickly can a Tupelo cash sale close?
A cash purchase avoids buyer mortgage underwriting, but title work, payoffs, required signatures and cleared funds still control the closing date. The five-day schedule on this page is an illustration, not a promised or measured Tupelo closing time.
Does Mississippi’s small-estate affidavit let me sell an inherited house?
No. The § 91-7-322 affidavit covers personal property, not the house. A qualifying will may instead be admitted as muniment of title under § 91-5-35, with a sworn petition and court involvement. A Mississippi attorney should confirm the authority and signatures needed for your estate.
Does accepting a cash offer stop foreclosure in Lee County?
No. An offer or purchase contract does not itself postpone a foreclosure sale. A purchase is only a possible option if the owner has authority and sufficient time to complete closing before the scheduled sale. Confirm the deadline and available options with the trustee, servicer and a qualified attorney.
What should I compare when I search “sell my house fast Tupelo”?
Compare the written purchase price, estimated net proceeds, remaining conditions, buyer funding and the available closing date. Tupelo’s reported 40-day median marketing period is a citywide reference, not a promise for your house; the price and days-on-market figures cover the three months ending September 2026.
Do I need to replace an older roof before requesting an offer?
No roof replacement is required simply to request an MHIC as-is offer. Mississippi’s roof-age insurance rules limit certain age-only refusals, but condition, exceptions and the insurer’s requirements still matter. Compare the actual roof scope and written purchase terms before deciding to repair.
Compare an Offer for Your Actual House
Share the address, known condition and your preferred timing. We will explain the written purchase terms so you can decide whether the offer fits.
Request My Tupelo Cash Offer → Call (866) 651-6617Tupelo Real Estate & Legal Terms Homeowners Should Know
- Chancery Clerk land records
- Lee County’s recording system for deeds, deeds of trust and other instruments; recording and title examination are separate tasks. Have the closing professional examine ownership and recorded interests; finding an indexed deed is not the same as obtaining a title opinion. Source
- Muniment of title only
- Court probate of a qualifying will to establish title to devised Mississippi realty without full estate administration. Ask whether the estate qualifies and which court documents and signatures are needed before agreeing to convey the house. Source
- Tax-sale redemption
- Generally a two-year opportunity after Lee County’s tax sale to redeem through the Chancery Clerk; distinct from mortgage foreclosure. Request an exact redemption payoff and deadline from the Chancery Clerk before planning how a sale will address the balance. Source
- Homestead exemption
- An eligible homeowner’s property-tax reduction; applications go to the county assessor between January 1 and April 1. Confirm eligibility and the filing window with the assessor; do not assume the seller’s exemption determines the buyer’s future tax bill. Source
- Suspect soil area
- A mapped Tupelo development constraint requiring geotechnical review and the city’s specified fill treatment where applicable. Check the parcel and proposed project with the city before assuming a construction or foundation budget. Source
- Substituted Trustee’s Notice of Sale
- The notice used by a replacement trustee to advertise a deed-of-trust foreclosure sale after default. Use the controlling notice to confirm the actual sale date, time and location, then discuss the deadline with an attorney. Source
Official Tupelo Homeowner Resources
Use the county for the actual deed or tax account, the city for parcel-specific development questions, and the court or an attorney for probate and other legal requirements. These resources support an informed selling decision.
Market figures are dated to the period shown above. This page provides general information, not individual legal, tax, probate, foreclosure-defense, insurance or financial advice. Verify current requirements and deadlines with the responsible office or qualified professional.