
⚡ Get a cash offer in 5–10 minutes • Middlesex County, MA
Sell My House Fast in Cambridge, MA — We Buy Houses for Cash
Get a Fair As-Is Cash Offer Without Listings, Repairs, or Commissions
To sell your house fast in Cambridge, MA, share the address, condition and preferred closing date. We buy houses in Cambridge, MA as-is: review a written cash offer today, then close through the selected attorney when title, inspection rights and required documents are addressed.
Get Your No-Obligation Offer
Start with the property details. We’ll explain the price and terms so you can decide.
Receiving an offer does not obligate you to sell.
Cambridge Market Watch • September 2026 report
A Competitive Market Still Leaves Room to Compare Your Options
The Redfin Cambridge report retrieved October 16, 2026 UTC describes the three months ending September 2026. Its citywide MLS/public-record calculations describe sold properties, not October-only results, a forecast or an as-is cash valuation.
A market-ready property may benefit from retail exposure. If yours needs work, compare the likely listing proceeds with an actual written offer. Those 28 days on market do not include every step between accepting an offer and receiving sale proceeds.
Leave the renovation decision to the buyer
Sell It Exactly as It Sits in Cambridge
We buy houses in Cambridge, MA in their current condition. Our direct-purchase policy lets you request an offer without preparing the property for a retail launch.
As-is describes the agreed condition. Massachusetts’ home-inspection rules, effective October 15, 2025, protect buyers of covered 1–4-unit buildings, condos and co-ops. The signed disclosure is due by the first purchase contract; sellers cannot require or accept advance inspection waivers. Cash payment does not create an exemption. A buyer may later decline voluntarily without seller inducement; limited statutory exceptions apply.
Read our guide to selling a house as-is and review the actual inspection and cancellation terms before signing.
Building history changes the repair discussion
Selling a House in Cambridge’s Neighborhoods
City studies describe different building eras and localized conditions. Use them to decide what to investigate at your address; they do not establish a defect or seller motivation for an entire neighborhood.
| Neighborhood / District | Housing Profile | Common Challenges We Resolve | Seller Scenario |
|---|---|---|---|
| East Cambridge | One- to three-family houses, apartments and condominium buildings. | The 2006 study recorded ponding and catch-basin problems near Fulkerson Street. Current drainage and actual water damage need confirmation. | If water damage is verified, compare building and drainage bids with an offer in current condition. |
| Mid-Cambridge | Mid-19th-century through early-1930s houses, three-deckers and apartments with brick, clapboard or shingle exteriors. | Painted masonry can hold moisture and develop freeze-thaw cracking or flaking; repointing needs compatible mortar. No failure rate is established. | If masonry work is needed, compare specialist bids and applicable preservation review with selling as-is. |
| The Port | Small two- and three-unit buildings; the plan’s Columbia–Harvard–Pine–Washington demonstration block is mostly pre-1900. | The 2019 plan models localized basement flooding and exposure of heating/electrical equipment. It recommends raising vulnerable utilities above design flood elevations. | If the parcel is exposed, compare resilience work and carrying costs with an as-is offer. |
Historical East Cambridge records document wood-frame houses and low hip roofs, Greek Revival gables and historic slate coverings. These are building examples, not a citywide construction ranking; check the actual roof and structure.
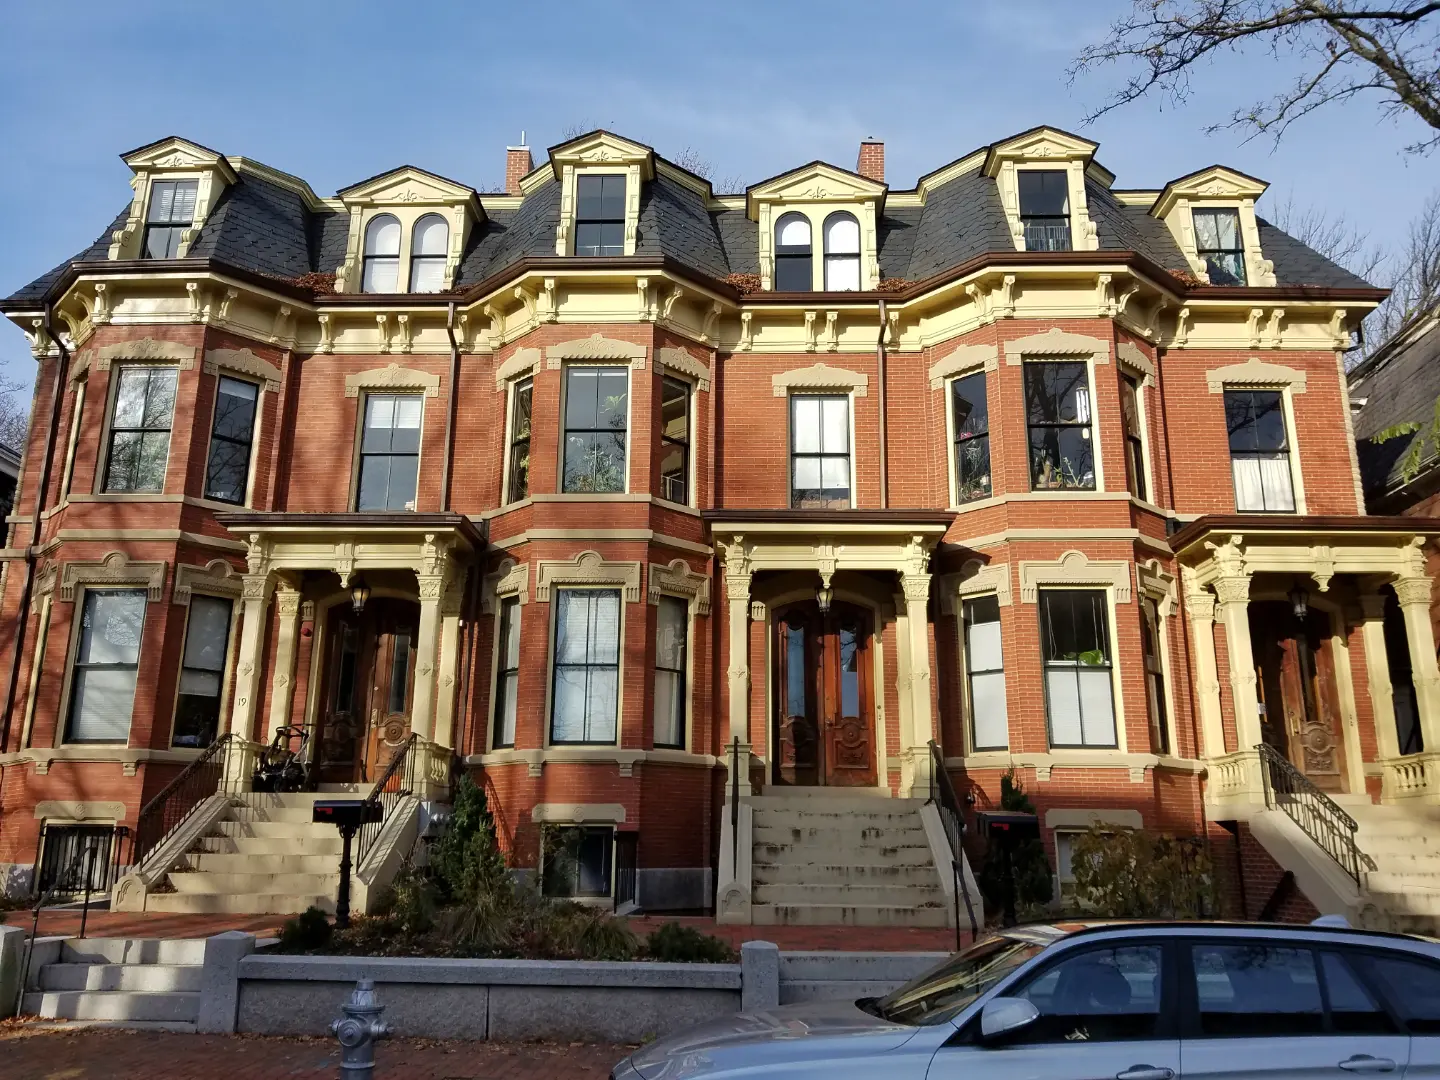
Condos, rentals and small multifamily homes
Match the Sale Plan to Your Cambridge Property
The City’s housing statistics report 32,897 renter-occupied units out of 49,444 occupied units (66.5%) in the 2020–2024 ACS. Condominiums were 27.6% of dwelling units on December 31, 2025; the June 30, 2025 inventory put 11.9% of units in two-unit buildings and 10.5% in three-unit buildings. These figures describe housing, not a trend in distressed sales.
For a rental, assemble the occupancy and lease records so a buyer can evaluate what is being purchased. For a condo, obtain association balance information early: Massachusetts’ 6(d) statement has a ten-business-day furnishing requirement after written request and payment of a reasonable fee. Missing documents can outlast a proposed five-day closing.
Check the cause before pricing the repair
Cambridge Property Conditions That Can Change Your Selling Budget
Older paint and window friction
In pre-1978 housing, deteriorating coatings and friction at painted doors or windows can release lead chips and dust. Peeling trim is a reason to investigate; invisible dust means appearance cannot prove compliance.
Massachusetts transfer rules require lead notification and known reports. If a child under six will live or continue living there, the new owner must achieve deleading or Interim Control within 90 days of taking title. Selling does not universally require pre-sale deleading. Compare a qualified scope with the buyer’s written terms.
Ice dams and winter leaks
Heat escaping into a snow-covered roof can melt snow that refreezes at colder eaves. The ridge can trap water and push it beneath roofing. Look for winter ceiling stains, damp attic insulation or ice at eaves and valleys.
The state’s ice-dam guidance makes the roof/attic relationship relevant: new shingles alone may not address heat leakage. DOI guidance says ice-dam damage is generally insured subject to the policy; wear, neglect and a particular loss need separate review.
Basement flooding and backflow
Intense rain can overwhelm drainage, enter low openings or back up through basement fixtures. Alewife riverine exposure adds a location-specific issue. Water at window wells, low entrances or basement fixtures warrants parcel-level investigation.
The City’s flooding guide supports checking below-grade systems. Review both current FEMA mapping and FloodViewer. Ordinary homeowners coverage generally excludes flood; federally backed mortgages in a FEMA Special Flood Hazard Area require flood coverage. Floodplain review may affect mitigation work.
Condition and insurance review
Actual unrepaired damage can affect underwriting. Massachusetts’ FAIR Plan is a last-resort market and requires inspection. Its inspection guidance addresses heating, wiring, unrepaired damage, walls, roofs, gutters, walkways and handrails; failure to allow inspection can lead to rejection or cancellation.
DOI Bulletin 2025-02 says roof discoloration or streaking alone should not justify adverse underwriting action; ambiguous aerial images need further review. Obtain a property-specific answer before assuming coverage is unavailable.
Documented damage may change a conventional buyer’s repair allowance, insurance review or financing assessment; it does not automatically make a sale fail. Cambridge’s resilience planning also addresses extreme heat, heavy rain and storm-surge/sea-level-rise hazards. Exposure varies by address.
Permits and service accounts: Cambridge ISD requires permits before construction, alteration or demolition, subject to ordinary-repair exemptions. Ask ISD about unfinished work before budgeting. The City electricity program lists Direct Energy as its selected supplier; Eversource remains the distribution utility handling bills and outages. Keep service-account questions separate from the attorney’s municipal-lien review.
Interactive planning tool • USD
AS-IS Repair Cost Estimator
This calculator provides a broad planning estimate—not an inspection, appraisal, contractor quote, offer or guarantee. Actual costs vary with labor, materials, scope, permitting, access and concealed damage. The rates below are illustrative assumptions, not measured Cambridge prices.
Enter the area receiving interior finish work. That allowance covers paint, flooring and minor drywall only; system allowances are separate. Lead-safe work, masonry rehabilitation, structural work, full kitchen/bath remodeling and major flood-resilience projects require separate scopes and bids.
Compare the amount you keep and the terms you accept
Cash Sale vs. Traditional Listing in Cambridge
A traditional sale may produce a higher gross price, but commissions, seller closing costs, repairs, concessions and ongoing holding expenses reduce the amount you ultimately keep. A direct cash sale generally prioritizes speed, certainty and convenience rather than the highest possible gross price.
Cambridge’s reported 28 median days on market is useful context, but it does not price your repairs or settle a condo association balance. Compare actual written net proceeds and obligations for the property you own.
| Decision point | Traditional listing | Direct cash sale with MHIC |
|---|---|---|
| Gross Price | Potentially higher gross price | Usually lower than full retail value |
| Commissions | Agent commission may apply | No agent commission |
| Closing Costs | Seller closing costs may apply | MHIC pays normal closing costs |
| Property Condition | Repairs or buyer credits may be requested | Property sold as-is |
| Contingencies | Financing and appraisal contingencies | No buyer-financing contingency |
| Timeline | Longer and less predictable timeline | Seller selects an available closing date |
Actual listing contingencies vary by offer. Review all written inspection, title and cancellation provisions in either route. Mortgage balances, taxes, association debts and other valid claims remain part of the settlement calculation; paying normal closing costs does not forgive those debts.
Compare Your Estimated Selling Options
Use our adjustable calculator to compare a traditional listing with a direct cash sale using your property’s estimated value and expenses.
Use the Net-Proceeds Calculator →Authority and actual deadlines come first
Probate, Foreclosure Deadlines, and Complicated Title Situations in Cambridge
Inherited property: a small-estate threshold does not transfer a house
Massachusetts voluntary administration covers personal property up to $25,000, excluding one motor vehicle, after 30 days have passed since death. The decedent must have been domiciled in Massachusetts; filing is in the county of residence. Real estate, excess personal-property value or a filed personal-representative appointment petition preclude this route.
An interested person or an eligible agency-designated representative files a sworn statement, death certificate and any original will. The register dockets the filing and issues an attested statement if eligible; a judicial hearing is not universally required. Debts remain payable in statutory order and MassHealth notice is required. This personal-property procedure cannot convey a Cambridge house.
The Middlesex Probate and Family Court South - Woburn serves Cambridge at 10-U Commerce Way, Woburn, MA 01801. Ask the court clerk and your attorney which probate or other lawful title route applies before promising a closing. Our inherited-house guide can help you organize the sale questions.
Mortgage foreclosure: work from the notices in your file
Massachusetts generally uses nonjudicial foreclosure under a mortgage’s power of sale; entry or action is also authorized. The usual sale notice may be captioned “Mortgagee’s Sale of Real Estate.” A foreclosure complaint is not the universal starting instrument.
- Cure: §35A gives qualifying payment defaults a 90-day cure period without acceleration, once in five years. It covers an owner’s principal residence accommodating four or fewer households, occupied or to be occupied at least in part by that owner; other residences, investment property and commercial-loan collateral are excluded. Notice is hand-delivered or sent by first-class and certified mail, or similar private-carrier service, to the last known address. Enforcement must await expiration. Permitted late fees and per-diem interest remain payable; statutory fee limits apply. Reinstatement afterward may be offered but is not an unconditional right through auction.
- Sale notice: §14 requires publication once in each of three successive weeks, first publication at least 21 days before sale. Registered-mail notice must go at least 14 days before sale to record equity owners and junior-interest holders identified as of 30 days before sale. The mortgage may require more notice.
- Federal overlay: for covered loans, Regulation X generally bars the first required foreclosure notice or filing until more than 120 days delinquent, subject to due-on-sale and joining-another-lienholder exceptions. Loss-mitigation protections may delay later steps.
- Auction and redemption: the statutory power permits auction on or near the property, near one parcel of a multi-parcel mortgage, or at a place designated in the mortgage. Read the actual sale notice. §18 provides no ordinary post-sale redemption after a valid power-of-sale mortgage foreclosure; the entry/possession route has a separate three-year provision. Tax-title foreclosure is different.
These are separate legal requirements, not a verified total Cambridge foreclosure timeline. A Land Court Servicemembers case determines military-service protections; it is not itself the foreclosure. An off-market sale is one possible option only if the seller has authority and enough time to complete payoffs and closing before the scheduled sale. An offer does not pause an auction. See our foreclosure selling guide.
Back taxes, municipal issues and ownership questions
The City of Cambridge Finance Department / Tax Collector, rather than a county collector, handles property taxes. Ordinary overdue installments bear 14% annual interest. Tax-title accounts entered before November 1, 2024 retain 16%; accounts entered on or after that date use 8%, as explained by DLS. Collection charges, including a demand fee of up to $30 and specified taking, search and recording costs, can also apply.
The City’s announcement reviewed October 16, 2026 listed October 19 issuance and November 18, 2026 payment due dates for FY2027 first-half bills. Check your actual bill; payments count when received. Request the account-specific payoff from Finance at 795 Massachusetts Avenue, Cambridge, MA 02139, or 617-349-4220.
For heirship questions, recorded claims or municipal correction orders, the selected attorney checks ownership and the Middlesex South Registry of Deeds records, obtains payoffs and asks Cambridge ISD about building and sanitary-code issues. Some matters need additional authority, releases or another agreed solution before a sale can proceed.
My House Into Cash provides a direct purchasing option, not legal, tax, financial, probate or foreclosure-defense advice. Consult a Massachusetts real estate attorney, the court clerk, the City Tax Collector or a qualified tax professional for your circumstances. A purchase offer cannot guarantee court approval, title clearance, lien removal, tax forgiveness or foreclosure prevention.
From signed agreement to net proceeds
What Happens Between Accepting Your Cash Offer and Getting Paid in Cambridge?
The schedule below illustrates an expedited transaction when the required work can be completed. It is not a five-day guarantee. Title questions, probate authority, inspection opportunities, association documents and payoff responses can move the date. Massachusetts conveyancing guidance explains attorney involvement; the lender-attorney rule in REBA v. NREIS concerns the mortgage settlements addressed in that case.
-
Day 0: Finalize the purchase contract
Put the price, as-is scope, items left behind, occupancy, available closing date and cancellation terms in writing. A direct MHIC purchase has no agent commission or MHIC service fee; normal closing costs follow the written agreement. Complete the required Massachusetts inspection-right disclosure by the first purchase contract and the applicable pre-1978 lead paperwork.
-
Days 1–2: Examine title and request local records
A trained examiner or attorney reviews Middlesex South ownership and encumbrance records. Recorded land uses book/page references; registered land uses certificates of title and document numbers. The closing attorney generally requests and records a Cambridge Municipal Lien Certificate covering taxes, assessments and applicable municipal water/utility liens. Recording within 150 days gives specified protection against omitted liens, subject to statutory exceptions.
For a condo, request the 6(d) association statement immediately; its ten-business-day furnishing window may extend this schedule. Arrange the Cambridge smoke/CO sale-transfer certificate process for covered properties.
-
Days 2–4: Confirm payoffs and address title obstacles
The attorney obtains mortgage, tax and applicable association payoff figures, reviews recorded claims and confirms who can sign. Cambridge tax-title balances require the actual redemption amount and the necessary release, rather than payment of only the original tax bill. An heirship or authority issue may require more time; an as-is contract does not clear it automatically.
-
Day 5, or the agreed later date: Sign, record and release funds
The usual Massachusetts form is a statutory quitclaim deed, with limited covenants covering the seller’s acts and claims through the seller. The contract and title review determine the deed for your transaction. The owner or authorized attorney-in-fact executes and delivers it, normally with notarial acknowledgment for recording; ordinary deeds do not require separate subscribing witnesses.
Paper submissions must meet the Registry’s signature and notary requirements, including original signatures, printed names and the notary’s expiration date. Recording goes to Middlesex South, 208 Cambridge Street, Cambridge, MA 02141, using the appropriate recorded- or registered-land department.
Arrange the agreed wire or check disbursement with the closing attorney and confirm when funds will be released. The Good Funds Law concerns mortgage-loan funds before recording; it does not require all seller proceeds to be wired or guarantee instant receipt.
For independent representation, Pressman & Kruskal, 678 Massachusetts Avenue, Suite 600, Cambridge, lists seller closings, deed preparation and title examination among its services. Select and verify your own counsel. Owner’s title insurance is optional; a lender’s policy protects a different interest and is usually required by a lender. The Registry also permits in-person closings; the format and provider are transaction-specific.
Cambridge and surrounding communities
Cambridge and Nearby Communities We Serve
We buy houses in Cambridge and surrounding Massachusetts communities. For local geographic context, the Census representative point for Cambridge is 42.376043, -71.118680. The communities below are examples of nearby locations, and we welcome inquiries from other areas too. Send us your property address to discuss your selling options.
These 18 nearby municipalities are drawn from the supplied Census municipality/internal-point data. You can also explore our Massachusetts coverage and Boston home-selling page.
Google Maps shows Cambridge and the surrounding region. The map and community list provide local context; they do not define a service boundary. Contact us about your property wherever it is located.
Know what the closing paperwork means
Cambridge Real Estate & Legal Terms Homeowners Should Know
- Municipal Lien Certificate (MLC)
- The collector’s statement of taxes, assessments and applicable municipal utility liens. Have the closing attorney obtain it so the settlement uses documented balances; recording within 150 days gives specified protection against certain omitted liens. Source ↗
- Registered Land / Certificate of Title
- A Land Court registration record requiring certificate and document-number review. Tell the closing attorney if your Cambridge property is registered land so the deed goes through the correct records and filing rules. Source ↗
- Statutory Quitclaim Covenants
- Limited Massachusetts deed promises concerning encumbrances created by the seller and claims through the seller. Review the promised deed form; this does not warrant every earlier owner’s title history. Source ↗
- 6(d) Certificate
- The condominium association’s statement of unpaid assessments and other sums. Request it early; recording provides the statutory discharge for other sums then unpaid, making the document important to the closing balance and timing. Source ↗
- Tax Title Redemption
- Clearing a municipal tax taking by paying the actual tax-title account, lawful charges and applicable interest through the statutory redemption process. Ask for the current figure and required release before treating a tax balance as settled. Source ↗
- Good Funds Law
- Massachusetts rules for the form and pre-recording delivery of mortgage-loan proceeds. They do not establish how your seller proceeds must be paid; agree on the payment method and release timing with the closing attorney. Source ↗
Direct answers for Cambridge sellers
Cambridge Home-Selling Questions
Which residential ZIP codes do you cover in Cambridge and nearby communities?
Cambridge’s residential ZIP areas are 02138, 02139, 02140, 02141 and 02142. The table includes residential street-delivery codes for every nearby municipality listed on this page; shared postal areas can cross municipal boundaries.
| Community | Residential ZIP codes |
|---|---|
| Cambridge | 02138, 02139, 02140, 02141, 02142 |
| Somerville | 02143, 02144, 02145 |
| Arlington | 02474, 02476 |
| Belmont | 02478 |
| Watertown | 02472 |
| Medford | 02155 |
| Brookline / Chestnut Hill | 02445, 02446, 02467; Brookline portions of 02135 and 02215 |
| Newton and its villages | 02458, 02459, 02460, 02461, 02462, 02464, 02465, 02466, 02467, 02468 |
| Waltham | 02451, 02452, 02453 |
| Lexington | 02420, 02421 |
| Winchester | 01890 |
| Woburn | 01801 |
| Melrose | 02176 |
| Burlington | 01803 |
| Needham | 02492, 02494 |
| Wellesley / Wellesley Hills | 02481, 02482 |
| Concord | 01742 |
| Weston | 02493 |
| Natick | 01760 |
Check the Cambridge ZIP map, Brookline’s cross-boundary ZIP guidance and the Massachusetts ZIP/type directory. PO-box-only and organization-specific codes are excluded. Use USPS address lookup to confirm the property’s delivery code. Ask about an address outside this list; these ZIP codes are local references and do not limit where we consider buying houses.
How do I sell my house for cash in Cambridge, MA?
Share the address, condition, occupancy and preferred timing with MHIC. Review a written offer, then have the selected attorney address Middlesex South title records, municipal balances, required disclosures and closing documents. You receive the agreed net proceeds when the attorney completes the transaction and releases funds.
Can I sell my Cambridge house as is?
Yes. You can negotiate a sale in current condition instead of completing a retail renovation. Covered Massachusetts sales still carry inspection-right and applicable lead-notification requirements. Put the repair scope, inspection terms, items left behind and any cancellation rights in writing.
Does a Cambridge cash buyer have to waive a home inspection?
No. Cash payment and an as-is label do not exempt a covered sale from 760 CMR 74.00. Sellers cannot require or accept advance inspection waivers; the required disclosure is due by the first purchase contract. A buyer can later choose to decline voluntarily without seller inducement, subject to the rule’s limited exceptions.
Can voluntary administration let me sell an inherited Cambridge house?
No. Massachusetts voluntary administration applies to qualifying personal property, up to $25,000 excluding one motor vehicle, after 30 days from death. It does not transfer real estate. Ask the Middlesex Probate and Family Court South clerk and a Massachusetts attorney which authority and title documents your house sale requires.
Can a cash sale stop a scheduled Cambridge foreclosure?
A completed sale before the auction may be an option when the owner has authority, adequate proceeds or agreed payoffs, and enough time to close. Requesting or accepting an offer does not pause foreclosure. Have an attorney review the actual sale notice, cure deadline and applicable state/federal protections immediately.
Who collects Cambridge property taxes, and what happens if they are overdue?
The City of Cambridge Finance Department / Tax Collector collects them. Ordinary overdue real estate taxes bear 14% annual interest. Tax-title accounts entered before November 1, 2024 retain 16%; those entered on or after that date use 8%, with applicable collection charges. Obtain a current account-specific payoff rather than estimating the balance.
How fast can a Cambridge cash sale close?
The date depends on completed title work, legal authority, payoffs, inspection rights and required certificates. A clean, ready file may support an expedited date, but five days is not guaranteed. A condo’s 6(d) statement alone has a ten-business-day statutory furnishing window after written request and a reasonable fee.
Does basement water mean my Cambridge property is in a FEMA flood zone?
No. A property outside a FEMA Special Flood Hazard Area can still experience precipitation flooding or drain backflow. Review the address on current FEMA maps and Cambridge FloodViewer, along with actual water history and the location of heating/electrical equipment. Ordinary homeowners coverage generally excludes flood.
How should I compare cash home buyers in Cambridge, MA?
Compare cash buyers for houses in Cambridge, MA using the written price, proof of funds, buyer identity, inspection and cancellation terms, normal closing-cost allocation and your estimated net proceeds. Check who will handle Middlesex South title records and Cambridge municipal balances. Our cash-offer guide explains the pricing questions to ask.
Request a Cash Offer for Your Cambridge Property
If your goal is to sell a house fast in Cambridge, Massachusetts, start with the address and what you know about the home. Compare the written price, inspection terms, payoffs and available date with your listing option.
Request My Cambridge Cash Offer →Prefer to talk? Call (866) 651-6617.
Primary sources for your property and paperwork
Official Cambridge Homeowner Resources
Use the record, bill, notice or department that applies to your address before making a sale or repair decision.