
Sell My House Fast in Portland, Maine — We Buy Houses As-Is
We buy houses in Portland, Maine as-is. Call (866) 651-6617 or send your address today for a written cash offer. Share known property issues, compare the terms, and choose an available closing date after ownership, title, and payoff review.
A Direct Cash Offer Without Preparing Your House for a Listing
(866) 651-6617CLICK TO CALL NOW FOR A FAST, NO OBLIGATION CASH OFFERGet Your No-Obligation Offer
Sell your Portland, ME house as-is, for cash.
Use our fast response form to receive a fair all cash offer today.
🔒 Strictly Confidential: No obligation to accept.
Average Call-back in 60 seconds or less 24/7/365
Talk with trusted real estate professionals from MyHouseIntoCash to buy your house fast. We handle all the paperwork and tailor a hassle free closing process to fit your moving plans.
Strictly Confidential & No Obligation
Receive a clear offer, ask your questions, and decide without pressure.
PORTLAND, MAINE · AUGUST 2026 CITY SNAPSHOT
Portland Market Watch: Lower Median Prices, Faster Marketing
Redfin’s Portland, Maine housing report shows median prices down 5.9% year over year, median marketing time of 29 days versus 35 a year earlier, and a price-drop share up 8.1 percentage points. The sale-to-list ratio was 100.3%; the competition panel rated Portland Somewhat Competitive at 66/100.
This citywide snapshot covers all home types in the three months ending August 2026 and was retrieved October 2, 2026. The report’s approximately 38-day average time to pending is a separate measure. Neither figure sets a cash-closing deadline or values your home.
Retail buyer demand still gives you a listing option to compare. A lower citywide median does not mean every Portland house lost the same value. Ask cash buyers for houses in Portland, Maine for written terms, then compare the expected proceeds with condition-matched local sales, repair scope and holding expenses.
OUR AS-IS PURCHASE POLICY
Sell It Exactly as It Sits in Portland
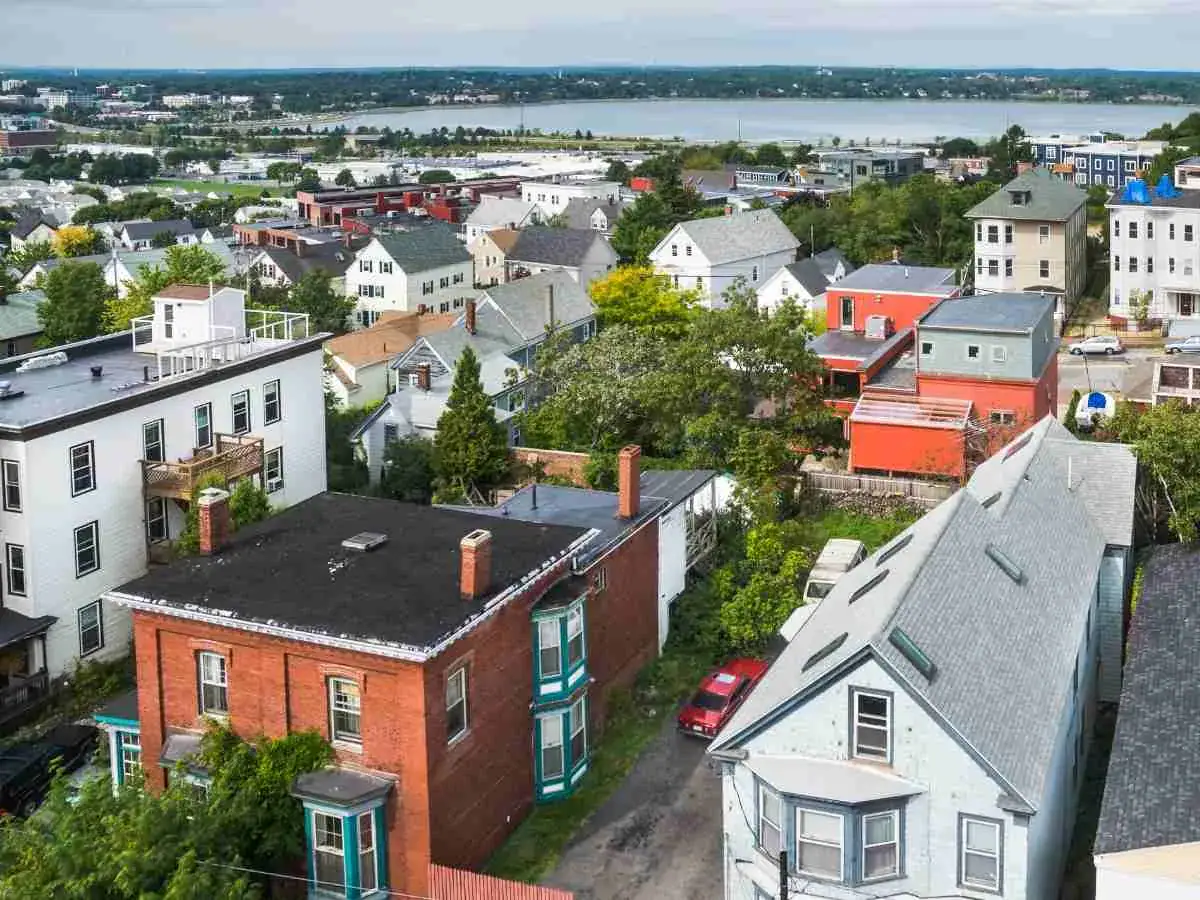
We buy houses in Portland, Maine without requiring listing preparation. Bring the property’s actual condition to the offer conversation. For the older brick and wood-frame homes documented in the Deering Street inventory, a fresh surface finish may leave substantial work underneath; compare that scope before funding cosmetic upgrades.
An as-is purchase still includes applicable disclosures. Most pre-1978 sales require known lead information and records, a federal pamphlet, contract warning language and a buyer inspection opportunity. Cash payment alone does not create an exemption. Document access, occupancy, possession and belongings left behind in the agreement. Our guide to selling a house as-is explains the preparation tradeoff.
BUILDING AGE AND MATERIALS CHANGE THE REPAIR QUESTIONS
Selling a House in Portland’s Neighborhoods
The archived ACS 2008–2012 housing table counted 33,945 Portland housing units, including 17,588 built in 1939 or earlier: 51.8%, with a 1.4-percentage-point margin of error. This historical baseline is not a current 2026 age distribution. The linked inventories below help explain why building records and retained materials matter to a repair decision.
| Neighborhood / District | Housing Profile | Common Challenges We Resolve | Seller Scenario |
|---|---|---|---|
| Parkside / Deering Street historic area | The inventoried area includes 1850s–1890s brick and wood-frame houses and double houses, with Greek Revival, Italianate, Mansard/Second Empire, Queen Anne and Shingle styles. | Review the actual masonry, wood exterior and historic roof repair scope. The inventory does not establish a neighborhood-wide defect rate. | An owner facing historic-material repairs compares restoring the building with an as-is purchase. |
| West End | City-hosted planning records describe historic residential styles dating approximately 1850 through the 1920s. | Establish the condition and repair needs of the older building and exterior features. Age is a reason to investigate, not proof of failure. | An owner weighs the cost and coordination of an older-home restoration against a direct offer. |
| East End / lower Munjoy Hill | The Newbury Street context documents small brick and wood-frame houses and cottages on compact parcels, mostly erected after the 1866 fire. | Inspect retained materials and consider repair access on compact parcels. This localized inventory does not describe all East End properties. | An owner with deferred repairs considers selling in present condition when managing rehabilitation is impractical. |
Housing descriptions apply to each source’s stated area. Condition-check suggestions and seller scenarios are property-specific examples, not measured resident behavior or defect prevalence. We buy houses for cash based on the house we review, rather than assume a neighborhood name establishes its condition.
DOCUMENT THE CAUSE BEFORE CHOOSING THE REPAIR
Portland Property Issues That Can Change Your Selling Plan
Older painted surfaces: dust and chips need a defined scope
Maine CDC identifies pre-1950 housing as particularly likely to contain lead paint. In pre-1978 houses with retained lead-based coatings, peeling paint or friction at windows and doors can release lead-bearing chips and dust. Chipped or flaking coatings and dust around older openings warrant investigation; appearance cannot confirm lead. This is an age-related risk, not a measured Portland-wide hazard rate.
Bring existing test reports and known lead records to the sale discussion. Federal disclosure rules provide a ten-day buyer inspection opportunity unless changed by written agreement or waived. The Maine DEP lead-safe home guidance explains why covered renovation work needs appropriate lead-safe handling. Repair scope may change a conventional buyer’s requested credit or terms; paint presence alone does not establish active exposure or automatic insurance rejection.
Ice dams: a new roof may leave the heat-loss problem unresolved
The Building Science Digest on ice dams explains how uneven roof warming melts snow while colder edges refreeze runoff. The ice ridge holds meltwater, which can enter beneath roofing and wet sheathing or interiors. Large icicles, ice ridges at eaves, recurring winter leaks and ceiling stains deserve a roof-and-attic assessment.
Efficiency Maine’s Gorham case study documents this mechanism in the region, without measuring how often Portland houses experience it. Inadequate air sealing or insulation can affect new as well as old homes. A roof replacement that leaves heat leakage unresolved may not address the cause. Share leak history and repair records; confirmed damage may lead a financed buyer to renegotiate or seek further evaluation rather than automatically prevent a sale.
Flood exposure: check the parcel, floor level and water history
The 2023 Maine State Hazard Mitigation Plan identifies Portland’s Bayside neighborhood in its flooding vulnerability assessment. This is localized area-level evidence, not a finding that every Bayside or Portland home floods. Floodwater entering low openings or below-grade spaces can wet finishes, building materials and equipment; depth, duration and exposed components change the repair scope.
Water lines, standing water or persistent lower-level dampness after a flood are reasons to gather records, rather than infer a FEMA zone from appearance. Review the address in the FEMA Flood Map Service Center, relevant elevation information and previous water-entry repairs. The Maine Bureau of Insurance explains that special-form homeowners coverage commonly excludes flood. Confirm separate coverage and property-specific requirements before treating a standard policy as protection.
Historic roofs and foundations call for building-specific estimates
The Deering Street nomination documents Mansard forms and the 1875–1876 Thomas Brackett Reed House’s hipped slate roof. Those examples do not establish the current dominant roof material in Portland. The 2015 city-filed 119 Winter Street application describes basement work and repointing a stone foundation at that house; it does not prove every older Portland foundation is stone.
For a property retaining these assemblies, obtain a scope that identifies the actual materials, access and concealed conditions before relying on a broad repair allowance. Existing reports help cash home buyers in Portland, Maine assess the house as is without requiring you to organize the restoration first.
THE RECORDS AND THE ACTUAL BUILDING GUIDE THE DECISION
Permits, Radon Testing, and Insurance for a Portland House
Alterations and municipal records
The City of Portland Permitting and Inspections Department handles permit review, inspections and code compliance. Use its Citizen Self Service portal and ask the department about the actual project. Existing unpermitted work needs project-specific review; an as-is agreement does not establish compliance. Provide known notices and alteration records for the purchase review.
Radon needs testing, not a visual judgment
The Maine Attorney General’s radon guidance identifies soil gas and private-well water as pathways. Air testing matters; a property using a private well also warrants water evaluation. Maine CDC says that when a home for sale is tested, an independent Maine-registered radon tester must perform the test. This tester requirement is not a statement that every sale must receive a new test.
Maine’s published premium factors include rebuilding cost, construction, home age, heating type, coastal proximity and claims history. Older systems, coastal wind exposure and primary wood heating can affect premiums; carriers differ, and a higher premium factor alone does not establish automatic denial.
An archival Liberty Mutual underwriting guide posted by the state illustrates screening for roof and foundation condition, heating, plumbing, wiring and occupancy. It is an archival carrier example, rather than a verified current 2026 rule. Request property-specific insurance terms and review known conditions before committing to repairs for a conventional sale.
If your goal is to sell a house fast in Portland, Maine, gather permit records, existing tests, leak history and policy information before deciding what work to fund. Read how cash buyers calculate offers and compare the actual written terms.
EXPLORE THE BUDGET BEFORE CHOOSING A SALE ROUTE
AS-IS Repair Cost Estimator
This calculator provides a broad planning estimate, not a Portland contractor quote, inspection, appraisal, cash offer or guarantee. Actual costs vary with scope, materials, labor, permitting, access and concealed damage. Interior finish work and system allowances are separate to avoid counting the same work twice.
Illustrative planning assumptions, not measured local prices. Interior rates cover finishes such as paint, flooring, and surfaces; the system add-ons below are outside that scope. Count a selected system only once.
Estimated planning range
$31,050–$51,750Interior: $27,000–$45,000; additional work: $0–$0; 15% contingency: $4,050–$6,750.
Specialized Portland work needs a separate scope. The documented historic roof examples and Winter Street stone-foundation project show why basic allowances cannot price every retained assembly. Lead-safe renovation or abatement, radon work, slate or Mansard detailing, ice-dam air-sealing corrections, flood cleanup, structural work and unresolved permit issues are outside these illustrative ranges.
COMPARE EXPECTED PROCEEDS AND WRITTEN TERMS
Cash Sale vs. Traditional Listing in Portland
A traditional sale may produce a higher gross price, but commissions, seller closing costs, repairs, concessions and ongoing holding expenses reduce the amount you ultimately keep. A direct cash sale generally prioritizes speed, certainty and convenience rather than the highest possible gross price.
Portland’s dated market snapshot combines a lower annual median price with faster marketing. Compare a real estate agent’s condition-specific listing estimate with a written offer, rather than apply the city median to your home sale price. You can compare multiple cash offers using the same repair information and settlement assumptions.
| Selling Dimension | Traditional Listing | Direct Cash Sale to MHIC |
|---|---|---|
| Gross Price | Potentially higher gross price | Usually lower than full retail value |
| Commissions | Agent commission may apply | No agent commission |
| Closing Costs | Seller closing costs may apply | MHIC pays normal closing costs |
| Property Condition | Repairs or buyer credits may be requested | Property sold as-is |
| Contingencies | Financing and appraisal contingencies | No buyer-financing contingency |
| Timeline | Longer and less predictable timeline | Seller selects an available closing date |
Compare Your Estimated Selling Options
Use our adjustable calculator to compare a traditional listing with a direct cash sale using your property’s estimated value and expenses.
Use the Net-Proceeds Calculator →MHIC’s purchase has no service fees or agent commission, and normal closing costs are paid as stated in the agreement. Mortgages, taxes and other seller obligations still affect your proceeds. Cash home buyers can have different inspection, cancellation or assignment terms. Ask who will buy the property and fund the purchase, review proof of funds, and confirm the settlement agent before accepting a cash offer.
AUTHORITY AND DEADLINES DETERMINE THE AVAILABLE OPTIONS
Probate, Foreclosure Deadlines, and Complicated Title Situations in Portland
Mortgage foreclosure: work from the actual notices and court papers
Ordinary residential homeowner foreclosure uses a judicial civil action in Maine. The complaint and summons are filed in the appropriate Superior or District Court; the complaint or Clerk’s Certificate of Foreclosure is recorded in the county registry within 60 days of commencement. Maine also has a limited power-of-sale route under §6203-A for qualifying entity/business mortgages, subject to exclusions. It is not the ordinary homeowner process.
For covered owner-occupied primary-residence mortgages securing personal, family or household loans, §6111 provides at least 35 days after written notice before acceleration or enforcement. Notice is sent by certified mail, return receipt requested, and ordinary first-class mail to the last known borrower and cosigner addresses. It includes cure, assistance, mediation and scam-warning information. Paying unaccelerated arrears and permitted charges within the cure period restores the mortgage’s terms.
The Maine Judicial Branch instructs homeowners to respond and request mediation within 20 days after service. Qualifying owner-occupied properties with no more than four units are eligible for mediation. Court cases commonly take several months or more; these milestones do not create one universal default-to-sale timeline.
Under §6322, redemption ordinarily lasts 90 days after judgment for mortgages executed on or after October 1, 1975. Earlier mortgages ordinarily have one year unless their terms provide otherwise. Appeals and exceptions can change the period. This is pre-sale redemption, not an ordinary 90-day right after a completed auction.
After redemption expires, §6323 requires publication once in each of three successive weeks; first publication is ordinarily due within 90 days, and sale generally follows 30–45 days after first publication, subject to applicable exceptions, federal requirements or court extension. Appeared parties or their attorneys receive mailed notice at least 30 days before sale. The property’s notice gives the actual venue and terms. Later reinstatement or redemption before sale may be allowed at the mortgagee’s discretion; it is not an unconditional right. Eligible power-of-sale mortgages have separate notice and recording milestones of at least 21 days before sale.
An offer or purchase contract does not pause foreclosure. An off-market purchase is one possible option only when you have lawful authority, enough time before the scheduled sale, and sufficient proceeds or an approved resolution of claims. Have your attorney and servicer review the actual deadline while you compare a sale with available alternatives.
Inherited property: the small-estate affidavit cannot convey a house
Maine’s collection of personal property by affidavit has a $40,000 statutory base indexed annually. For a person who dies in 2026, the published adjusted cap is $52,500. The test uses the entire estate wherever located, less liens and encumbrances; it is not a gross-assets test or a deduction of every unsecured debt.
At least 30 days must pass after death. No personal-representative appointment may be pending or granted in any jurisdiction, and the claiming successor must be entitled to the property. The affidavit is made by or for that successor and ordinarily presented to the asset holder without a routine court hearing. The section states no express Maine-domicile requirement. It collects personal property and cannot transfer land. Falling below the cap does not provide authority to sell an inherited Portland house.
For the actual real-estate ownership route, contact a probate attorney and the Cumberland County Probate Court at 142 Federal Street, Suite 125, Portland, ME 04101. Have the closing professional confirm the required appointment, ownership and signing documents before choosing a date. Our inherited-house guide can help organize the purchase discussion.
Recorded claims and ownership questions need a closing file
The Cumberland County Registry of Deeds is at 27 Northport Drive, Portland, ME 04103. Its record-search guidance uses grantor/grantee names or book and page, rather than a street-address index. Start with the owner identity in assessor records, then let the title professional examine the relevant recorded history.
Heirship questions, a recorded tax claim or any actual recorded enforcement claim must be reviewed on its own terms. Provide estate documents, notices and balances. A title professional identifies requirements and obtains appropriate payoffs or releases; a cash offer does not remove a lien or guarantee clearance. The verified local settlement-provider example below is not a confirmed MHIC partnership.
Professional guidance matters. MHIC provides direct purchasing solutions, not legal, tax, probate, financial or foreclosure-defense advice. Consult the court clerk, municipal Tax Collector, a Maine real estate or probate attorney, tax professional, or other qualified adviser for your circumstances. Court approval, lien removal and foreclosure prevention are not guaranteed.
THE MUNICIPAL BILL AND RECORDING DATE CHANGE THE PAYOFF
Portland Property Taxes: Confirm the Bill and Any Recorded Lien
The City of Portland Treasury / Office of Treasurer and Tax Collector collects Portland municipal property taxes. For FY2027, installments are due October 16, 2026 and March 12, 2027; interest begins October 17, 2026 and March 13, 2027 respectively. Ask for the balance applicable to your actual settlement date.
The Maine State Treasurer lists a 7.00% maximum annual delinquent-tax rate for 2026. This is the state ceiling, not verification of Portland’s adopted FY2027 rate. Under §505, the municipality establishes the applicable rate within the ceiling, and the commitment-year rate continues for that bill until paid. Confirm the city’s actual rate, interest and applicable charges directly.
A recorded municipal tax-lien mortgage under §943 has statutory priority and ordinarily forecloses automatically 18 months after recording if not redeemed. The Treasurer ordinarily sends an expiration notice 30–45 days before that deadline, subject to statutory notice exceptions. This municipal process is distinct from the judicial mortgage foreclosure described above. If a notice has arrived, have a qualified professional check its recording date, balance and deadline promptly.
FROM WRITTEN AGREEMENT TO RECORDED TRANSFER
What Happens Between Accepting Your Cash Offer and Getting Paid in Portland?
This is an illustrative expedited sequence, not a guaranteed five-day closing. Seller authority, applicable disclosures, title requirements, payoff responses, signing and recording readiness determine the earliest available date. Maine regulates registered settlement agencies and recognizes attorneys acting in their professional duties; do not assume every closing requires the same provider or arrangement.
Day 0 — Mutual agreement and purchase contract
Confirm the written cash offer, condition, disclosures, inspection terms, possession, belongings, cost allocation and an available closing date. MHIC charges zero purchase service fees and no agent commission and pays normal closing costs as stated in the agreement. Taxes, mortgages and other seller obligations remain separate. For an inherited property, confirm lawful seller authority before committing to a timetable.
Days 1–2 — Title search and local due diligence
Confirm the settlement professional for the transaction. C.H. McLaughlin Title Company, LLC at 70 Center Street, Suite 401B, Portland, ME 04101 is a verified local provider example, not an established MHIC partner. Its published cash-closing procedure includes a title search, property-tax and public-utility checks, and arranging previous-loan payoffs. Its owner’s title-insurance policy requirement applies to that firm’s cash closings, rather than every Maine sale.
Cumberland County record research uses names or book and page to examine deeds, mortgages, liens and plans; assessor records help establish owner identity. Share known permit or code notices for project-specific review. Utility account checks do not establish that an ordinary CMP electric bill is a title lien.
Days 2–4 — Payoffs, releases and authority documents
Obtain the current mortgage payoff and verified claim balances, the Portland Treasury tax balance with applicable interest, and required releases or estate-authority documents. Review the proposed settlement statement against the agreement. An unresolved recorded claim, missing signer or delayed payoff response can extend this sequence. Use the property’s actual title requirements rather than presume every transaction needs the same municipal certificate or association document.
Day 5, if ready — Deed signing, recording and proceeds
Maine provides a warranty deed under §763 and a quitclaim deed with covenant under §765. The latter gives more limited covenants concerning claims through the grantor. The agreement, ownership and title circumstances determine the form; there is no single mandatory private-sale deed established by these sources.
Meet the execution and acknowledgment requirements under §203 and county recording requirements, including original signatures, proper acknowledgment and printed names. The cited ordinary-deed requirements do not prescribe two subscribing witnesses; unusual instruments need separate review. Submit the transfer to the Cumberland County Registry of Deeds, 27 Northport Drive, Portland, ME 04103.
For settlements governed by the Funded Settlement Act, §525 calls for recordation and disbursement within two business days of settlement, subject to applicable rescission rights. Confirm the agent’s payout method and release timing; signing does not guarantee immediate bank availability.
Can I sign remotely, and will seller proceeds arrive by wire?
McLaughlin’s seller guidance describes in-person and mail-away signing with a notary. That firm ordinarily issues a seller check at closing, sends mail-away proceeds by overnight check and states that it does not wire seller proceeds. This is a firm-specific practice, not a Portland-wide payout rule. Confirm arrangements with the actual settlement agent, including check payee and funds availability.
Maine’s §1920 journal rules require a journal for electronic and remote notarizations and permit one for tangible-record notarizations; the listed required contents do not include a thumbprint. The appropriate acknowledgment, identity verification and document requirements still apply.
TERMS YOU MAY SEE IN THE PROPERTY FILE
Portland Real Estate & Legal Terms Homeowners Should Know
- Clerk’s Certificate of Foreclosure
- A certificate that may be recorded instead of the foreclosure complaint within 60 days of commencing the civil action; it places the foreclosure in the county land records.
- Period of redemption
- Ordinarily the 90 days after judgment for mortgages executed on or after October 1, 1975, during which the borrower can redeem before the judicial sale. It is not an ordinary 90-day period after auction.
- Tax lien mortgage
- Maine’s recorded municipal tax-lien instrument, ordinarily subject to an 18-month redemption period before automatic foreclosure. A seller must resolve it when clearing tax/title problems.
- Quitclaim deed with covenant
- Maine’s statutory limited-warranty deed: the grantor’s covenants address claims through that grantor. Sellers and buyers should identify this warranty scope before agreeing on the deed.
- Book and page
- Recorded-document identifiers used in Cumberland County title research. Searches use these identifiers or grantor/grantee names rather than a street-address index.
- Collection of personal property by affidavit
- Maine’s small-estate collection procedure after the statutory waiting period and subject to the indexed estate-value cap. It cannot itself transfer an inherited house.
GREATER PORTLAND, THE LAKES REGION AND NEARBY MAINE COMMUNITIES
Portland and Nearby Communities Within Our 75-Mile Review Area
We review residential submissions in Portland and nearby Maine communities. The 75-mile straight-line reference radius starts at Portland City Hall’s published historic-nomination point, 43.659167, −70.258056. These coordinates identify the City Hall property at 389 Congress Street, not a unique surveyed city-center point.
Regional overview centered on Portland City Hall’s published reference point. Select a community for its map and approximate straight-line reference distance.
All 61 surrounding community reference points listed here are within 75 miles, using municipal centroid coordinates in the January 1, 2026 Census county-subdivision table. Distances are straight-line measurements from the City Hall point to community centroids, rather than driving distances or individual-property measurements. The Google map is interactive and does not draw an exact service boundary. Send the physical address for purchase and distance review.
Nearby towns can use a different municipality’s Tax Collector and another county’s Probate Court or Registry of Deeds. Portland’s FY2027 tax dates apply to Portland property. Our Maine cash home-buying page covers broader state submissions. The ZIP FAQ below includes residential delivery areas and postal overlaps for every community shown here.
PORTLAND HOMEOWNER QUESTIONS
Frequently Asked Questions
Which residential ZIP codes do you cover in Portland, Maine and the surrounding communities?
We review private residential properties in the delivery ZIP areas below, including postal overlaps across municipal boundaries. The table covers Portland and all 61 nearby communities shown on this page. A mailing-city name can differ from the municipality; the physical address and lawful ownership determine the purchase review.
| Community / Postal Overlap Area | Residential Delivery ZIP Codes |
|---|---|
| Portland, ME | 04101, 04102, 04103, 04105, 04106, 04108, 04109 |
| South Portland, ME | 04102, 04106, 04107 |
| Westbrook, ME | 04062, 04092, 04105 |
| Scarborough, ME | 04038, 04074, 04092, 04106, 04107 |
| Cape Elizabeth, ME | 04074, 04106, 04107 |
| Falmouth, ME | 04092, 04103, 04105 |
| Cumberland, ME | 04021, 04039, 04096, 04097, 04105, 04110 |
| Yarmouth, ME | 04096, 04097 |
| North Yarmouth, ME | 04039, 04069, 04096, 04097 |
| Gorham, ME | 04038, 04074 |
| Windham, ME | 04021, 04039, 04062 |
| Freeport, ME | 04013, 04032 |
| Gray, ME | 04039, 04071, 04260 |
| Brunswick, ME | 04011 |
| Saco, ME | 04064, 04072 |
| Biddeford, ME | 04005 |
| Old Orchard Beach, ME | 04064, 04072 |
| Buxton, ME | 04005, 04038, 04084, 04093 |
| Hollis, ME | 04042 |
| Standish, ME | 04024, 04071, 04084, 04085 |
| Raymond, ME | 04015, 04071 |
| Casco, ME | 04015, 04029, 04055, 04071 |
| Naples, ME | 04015, 04055 |
| Sebago, ME | 04024, 04029, 04055, 04071 |
| Baldwin, ME | 04024, 04029, 04091 |
| Bridgton, ME | 04009, 04022, 04037, 04040, 04055 |
| Harrison, ME | 04009, 04040, 04268 |
| Harpswell, ME | 04003, 04011, 04066, 04079 |
| Long Island, ME | 04050 |
| Arundel, ME | 04005, 04043, 04046 |
| Kennebunk, ME | 04002, 04043, 04046, 04073, 04090 |
| Kennebunkport, ME | 04046 |
| Wells, ME | 04043, 04090 |
| Ogunquit, ME | 03902, 03907, 04090 |
| York, ME | 03902, 03903, 03909, 04090 |
| Kittery, ME | 03904, 03905 |
| Eliot, ME | 03903, 03908, 03909 |
| South Berwick, ME | 03906, 03908 |
| Berwick, ME | 03901, 03906, 03908, 04027 |
| North Berwick, ME | 03901, 03906, 03908 |
| Sanford, ME | 03906, 04027, 04073, 04083, 04090 |
| Alfred, ME | 04002, 04087 |
| Lyman, ME | 04002, 04005, 04030, 04087 |
| Waterboro, ME | 04002, 04030, 04061, 04087 |
| Limington, ME | 04020, 04048, 04049 |
| Limerick, ME | 04048 |
| Bath, ME | 04530, 04579 |
| West Bath, ME | 04530 |
| Topsham, ME | 04086 |
| Bowdoin, ME | 04008, 04086, 04252, 04280, 04287 |
| Bowdoinham, ME | 04008, 04086, 04287 |
| Phippsburg, ME | 04530, 04562 |
| Woolwich, ME | 04008, 04578, 04579 |
| Auburn, ME | 04210, 04236, 04240, 04258 |
| Lewiston, ME | 04210, 04240, 04250, 04280 |
| Lisbon, ME | 04240, 04250, 04252, 04287 |
| Durham, ME | 04210, 04222, 04250 |
| Poland, ME | 04015, 04256, 04260, 04270, 04274 |
| New Gloucester, ME | 04039, 04071, 04260 |
| Pownal, ME | 04032, 04069, 04097 |
| Chebeague Island, ME | 04017, 04050 |
| Frye Island, ME | 04071 |
PO-box-only and unique institutional codes are excluded. Island delivery areas shown for Portland are included; provide the physical address, occupancy and access details for property-specific review. The list covers the communities shown, rather than every residential ZIP across the full 75-mile circle. If your home is near a postal boundary or in another nearby town, submit its street address for review.
What is the first step if I want to sell my house for cash in Portland, Maine?
Call (866) 651-6617 or submit your address through the offer form today. Share condition, occupancy, known property issues and your preferred timing. We explain a written cash offer and an available schedule after review. For an inherited property, provide the ownership or estate documents you have so the closing professional can identify the next requirements.
Can I sell my house as is in Portland, Maine with peeling paint or winter roof leaks?
Yes. Request an offer before completing repairs and share known lead reports, leak history and previous work. An ice-dam leak may need roof and attic assessment because replacing the covering alone can leave heat leakage unresolved. Most covered pre-1978 sales still require federal lead disclosure materials and a buyer inspection opportunity unless changed by agreement or waived.
How fast can a Portland cash purchase close?
The earliest available date depends on seller authority, applicable disclosures, title search, payoffs, signing, recording and settlement readiness. The five-day sequence on this page is illustrative, not guaranteed. Maine’s Funded Settlement Act has recording and disbursement timing rules for covered settlements, and the actual agent’s payment method and bank availability matter. Portland’s 29-day median days on market does not predict cash-closing duration.
Can a Maine small-estate affidavit authorize selling an inherited Portland house?
No. Maine’s personal-property collection affidavit cannot convey land. For deaths in 2026, the indexed cap is $52,500 for the entire estate wherever located, less liens and encumbrances. At least 30 days must pass, no personal-representative appointment can be pending or granted, and the successor must be entitled to the property. An inherited-house sale needs separate lawful title and signing authority.
Will accepting a cash offer stop a Maine mortgage foreclosure?
No. An offer or signed purchase contract does not pause foreclosure. A sale before the scheduled auction is one possible option only with lawful authority, enough time and sufficient proceeds or an approved resolution of claims. Ordinary homeowner foreclosure uses court proceedings. Check the actual cure notice, court papers, judgment and sale notice with your attorney and servicer rather than rely on a generic timetable.
Are Portland, Maine home prices falling?
The Redfin snapshot retrieved October 2, 2026 reports a $588,111 median sale price, down 5.9% year over year, for all home types in the three months ending August 2026. Median days on market was 29 versus 35 a year earlier. This dated citywide trend does not establish the value change or market value of your individual property.
How should I compare cash home buyers in Portland, Maine?
Compare the written price, proof of funds, inspection and cancellation terms, assignment provisions, normal closing costs and proposed schedule. Ask who will buy the property and fund the purchase. Compare expected proceeds after mortgages, Portland taxes and other seller obligations, and identify the settlement professional. Avoid pressure to sign before you understand the agreement.
Does selling a Portland house as-is remove lead or radon requirements?
No. Cash payment and as-is terms do not by themselves exempt a covered pre-1978 transfer from federal lead disclosures. Maine CDC also says that when a home for sale is tested for radon, an independent Maine-registered tester must perform the test. That rule identifies who may test; it does not state that every home sale must receive a new radon test.
Who pays closing costs when MHIC buys my Portland house?
MHIC pays normal closing costs and charges no purchase service fee or agent commission as stated in the written agreement. Your mortgage, taxes and other seller obligations still reduce proceeds. Confirm the settlement statement, the treatment of any additional charge and the actual payout method before signing.
Is a Portland tax-lien deadline the same as a mortgage-foreclosure deadline?
No. A recorded Maine municipal tax-lien mortgage ordinarily has an 18-month redemption period before automatic foreclosure, with statutory expiration-notice requirements and exceptions. Ordinary homeowner mortgage foreclosure follows a court action, judgment, pre-sale redemption and sale notices. Ask the Tax Collector and an attorney to review the actual recorded tax lien or mortgage case promptly.
Does a Bayside address mean my house floods or has flood insurance?
No. The state hazard plan identifies Bayside in an area-level flooding vulnerability assessment, rather than assign risk to every house. Check the current FEMA parcel map, elevation information and actual water-entry history. Special-form homeowners policies commonly exclude flood, so confirm separate flood coverage and transaction-specific requirements.
YOUR PROPERTY, YOUR DECISION
Request a Cash Offer for Your Portland House
Ready to sell your house fast in Portland? Start with the address, occupancy, condition and moving plans. If you have an older roof, winter leaks, a known test result or an inherited ownership interest, share the records you already have. A written offer lets you compare buying terms with the cost and time of the actual work.
Request Your No-Obligation Cash Offer →
Prefer to talk? Call (866) 651-6617, our national toll-free number. Learn more about our direct home-buying process. You decide whether the offer fits your plans.
PRIMARY CONTACTS AND RECORDS FOR YOUR PROPERTY
Official Portland Homeowner Resources
Central Maine Power’s service-territory tariff lists Portland for electricity transmission and distribution; electricity supply may be purchased separately. Confirm the address’s provider and arrange account changes directly. Utility account handling is separate from determining recorded title claims.