
Sell Your House for Cash in Shreveport, LA
To sell your house fast, compare an as-is offer with a realistic listing plan. Send MyHouseIntoCash your Shreveport house address, current condition, ownership and preferred move date. We review the home and explain the written terms. You can compare the estimated seller net before deciding whether to proceed.
Redfin’s Shreveport housing report gives these figures in its narrative for the three months ending August 2026, checked October 5, 2026. The separate chart panel uses a different period and is not combined with these values. The competition panel scores the area 44/100, “Somewhat Competitive,” and describes typical sales around 4% below asking price.
The median declined while reported market time shortened by five days. Redfin notes that some homes get multiple offers; a maintained home can still merit an open market listing. For an older Highland residence with substantial upkeep or a home with documented flood damage, compare condition-matched recently sold homes, the necessary work and carrying expenses with the written offer. The citywide median and average discount do not determine an individual transaction amount.
Fifty-four days on market is not a complete contract-to-payment period. If you need to sell your house fast, a succession, mortgage release or separate city and parish tax balance may matter more to the available schedule than a citywide average.
Sell It Exactly as It Sits in Shreveport
The city’s 2019–2023 Consolidated Plan reports a historical 2011–2015 ACS baseline of 70% of owner-occupied and 68% of renter-occupied units built before 1980. These are historical housing-age figures, not a 2026 inventory or a lead-test result. For an older home, gather existing paint, pest, roof and repair records before committing to costly repairs for a listing.
An as-is sale still needs honest condition information, clear possession terms and a written agreement about remaining belongings. Our as-is selling guide explains how to compare a present-condition offer with a repair-and-list plan.
Selling a House in Shreveport's Neighborhoods
Historic inventories and the Choice Neighborhood plan describe different housing eras and forms. Use them to frame a property review. The seller scenarios below are potential use cases, not measured neighborhood motivations or current cash-sale trends.
| Neighborhood / District | Housing Profile | Common Challenges We Resolve | Seller Scenario |
|---|---|---|---|
| Highland | Late-19th- and early-20th-century Queen Anne, Colonial Revival and Craftsman/bungalow residences; the original historic nomination’s contributing period is approximately 1890–1936. | Review deteriorating older paint and rehabilitation scope. Age supports lead screening, not proof of lead or a measured district defect rate. | An owner can compare an as-is offer with the cost and time of restoring an older residence. |
| South Highlands | Early-20th-century residential development with Bungalow/Craftsman and Colonial Revival architecture; National Register periods of significance cover 1900–1949. | Assess surviving older coatings and deferred upkeep before budgeting updates; the historic listing does not establish unusual defect prevalence. | An owner of an inherited older residence can compare updating for retail buyers with a direct sale after ownership authority is established. |
| Allendale | The June 2013 Choice Neighborhood plan described predominantly single-family private housing, mainly small shotgun cottages, with some Victorian and Ranch-style houses. | The historical plan documented vacant houses, overgrown lots and blighted structures. Review the present condition and actual notices rather than assume a current neighborhood-wide failure rate. | An absentee or vacant-home owner can compare rehabilitation and continued upkeep with an as-is disposition. |
Construction age and a historical planning observation do not diagnose today’s home. Confirm the actual condition and any applicable historic-review requirements before planning alterations.
What to Check in a Shreveport Home Before Selling
River backwater: review the parcel and water history
Shreveport’s flood-hazard guidance explains that high Red River stages can back water into connected lakes and bayous, including affected areas around Cross Lake and Twelve Mile Bayou. Levels can rise even when rainfall at the house is lower. The concern applies to localized low-elevation flood-affected areas of any construction era, not every home in the city.
Waterlines, wet lower-wall finishes and damaged flooring are reasons to investigate actual inundation history. Floodwater can affect finishes and other building components, so a cosmetic allowance alone may miss the necessary work. Check the address in FEMA’s effective flood map and review the city’s floodplain building requirements before undertaking repairs.
The Louisiana insurance regulator explains that ordinary homeowners policies generally exclude flood. Coverage and past water entry can change a buyer’s costs and negotiations. Compare a documented repair-and-insure plan with an offer for the current condition; a flood concern does not automatically make a sale impossible.
Termites: separate treatment from wood repairs
LSU AgCenter’s termite and decay guidance explains how subterranean termites consume cellulose and can damage structural wood. Moisture and accessible wood or cellulose debris near or under a home support activity. Wood floor, wall or roof components can be affected at any age.
Mud tubes, discarded wings, sagging doors or floors and crumbling drywall warrant a pest-professional assessment. LSU documents native subterranean termites throughout Louisiana; that regional range does not establish a Shreveport infestation percentage or Formosan dominance.
Confirmed activity or damage can require treatment and a separate structural repair scope. LSU notes that ordinary homeowners coverage does not cover termite/decay damage. A wood-destroying-insect assessment may be relevant to the home buyer or buyer’s lender. Use the actual report to compare the work with the written offer; not every warning sign proves an infestation.
Older paint: as-is does not remove disclosure duties
Highland and South Highlands contain documented pre-1978 housing. Where lead-containing coatings remain, deterioration or disturbance can produce contaminated chips and dust. Peeling, chipping, chalking or damaged older paint warrants review, but appearance cannot establish lead content.
EPA’s lead-disclosure guidance applies to most covered pre-1978 sales. Provide known lead information and available reports before the buyer becomes obligated, along with the required pamphlet and inspection opportunity. A covered cash/as-is sale still has those duties.
Use existing tests and appropriate professional advice before disturbing older coatings. An older build date identifies a screening category, not a test-positive rate. Include any actual findings in the repair scope and condition discussion.
Historic assemblies and storm history
The Highland federal building inventory identifies wood-frame residences, some houses described as brick and individual concrete-block buildings. It also records hipped, gabled and mixed hipped/gabled roof forms. These are documented district examples, not current citywide material shares or a foundation inventory. A brick exterior does not establish structural brick.
SWEPCO’s March 4, 2025 storm report identifies damaging regional wind and hail and includes Shreveport among affected locations. Gather any actual roof inspection, claim and repair records; a regional storm report does not prove damage to your home.
Assess the actual assembly and work needed before accepting a generic roof or structural allowance. No parcel-specific expansive-soil diagnosis or coastal storm-surge classification is assumed for this inland market.
The relevant evidence is the actual inspection, address and condition history. Findings can change allowances, coverage or negotiations; they do not automatically cause a buyer to withdraw or financing to fail.
Shreveport Permits, Property Standards and Insurance
Roof condition can change coverage options
The Legislative Auditor’s March 2025 Fortify Homes report documents program participants who could not obtain private coverage without replacing a roof, alongside old/end-of-life and damaged roofs. This is statewide program-sample evidence, not a Shreveport denial rate or a universal roof-age rule.
LDI’s April 30, 2026 market update reports three additional homeowners insurers licensed during January–April and mixed rate changes. New entrants do not establish cheaper premiums or eligibility for your address. Louisiana Citizens is the homeowners insurer of last resort when private coverage is unavailable; no Shreveport-specific market share is established.
Ask the actual carrier about the roof and coverage before including insurance-funded repairs in your plan. No blanket 15-year roof cutoff, named-material denial or mandatory four-point inspection is assumed.
Check permit history before finishing undocumented work
Public Works’ Division of Permits and Inspections is at Government Plaza, 505 Travis Street, Suite 130, Shreveport, LA 71101; 318-673-6100. Its permit list includes remodels, additions, roofing and siding. City inspections cover foundation, framing, final stages and electrical, mechanical and plumbing work.
For an addition or remodel without records, request the actual permit and inspection history. Property Standards identifies substandard structures such as collapsing roofs, fire damage and deteriorated porches, walls, steps, garages or sheds, plus nuisance conditions and related liens. Obtain the actual notice and recorded-lien information; do not assume every notice is a lien.
The city’s Block By Block initiative identifies neighborhood sweeps and SIRA’s work returning vacant homes to commerce. This municipal priority does not measure how many homeowners choose cash offers. For a vacant home, compare ongoing upkeep, documented notices and the feasible rehabilitation scope with the written purchase terms.
For a covered residential transfer, Louisiana’s disclosure statute requires a property disclosure document. Statutory exemptions can apply, including certain estate and court-ordered transfers. Have counsel or the closing provider confirm applicability; selling as-is is not permission to conceal known defects.
How to Compare Shreveport Home Buyers
As-Is Repair Cost Estimator for Shreveport
Build a broad allowance for cosmetic work and selected systems. A Highland home with older finishes, documented termite damage and a flood-affected home can have very different scopes. Use actual inspections, permit requirements and bids where available.
Illustrative U.S.-dollar planning assumptions, not measured Shreveport contractor prices.
The ranges are planning examples, not an inspection, appraisal, contractor quote, required deduction from a cash offer or guarantee. Scope, labor, permits, access, lead-safe work, materials and concealed damage can change costs substantially. A no-work selection still produces $0 under this model; it does not establish that the actual home needs no repairs.
Cash Sale vs. Traditional Listing in Shreveport
A traditional sale may produce a higher gross price, but commissions, seller closing costs, repairs, concessions and ongoing holding expenses reduce the amount you ultimately keep. A direct cash sale generally prioritizes speed, certainty and convenience rather than the highest possible gross price. Shreveport’s reported median declined 5.7% year over year while average market time was 54 days. Compare realistic carrying expenses and actual flood, pest or older-finish work rather than assume a fixed percentage of after-repair value.
| Decision point | Traditional listing | Direct cash sale with MHIC |
|---|---|---|
| Gross Price | Potentially higher gross price | Usually lower than full retail value |
| Commissions | Agent commission may apply | No agent commission |
| Closing Costs | Seller closing costs may apply | MHIC pays normal closing costs |
| Property Condition | Repairs or buyer credits may be requested | Property sold as-is |
| Contingencies | Financing and appraisal contingencies | No buyer-financing contingency |
| Timeline | Longer and less predictable timeline | Seller selects an available closing date |
When comparing cash home buyers in Shreveport, request proof of funds, a written price and an itemized seller net. The agreement controls normal closing-cost coverage. Mortgage payoff, taxes, liens and other seller obligations can still reduce proceeds. Read our cash buyer versus Realtor guide.
Compare Your Estimated Selling Options
Use our adjustable calculator to compare a traditional listing with a direct cash sale using your property’s estimated value and expenses.
Use the Net-Proceeds Calculator →Quick Tips for Comparing Shreveport Home Buyers
The reported 54-day average market time makes carrying expenses worth comparing before you sell. For a flood-affected or older home, use documented work and title requirements to judge what each home buyer is offering.
- Verify the purchasing entity. Ask cash buyers for the legal name, proof of funds and a verifiable track record. Confirm who will purchase properties named in the contract and whether assignment is permitted.
- Ask how buyers plan to buy homes. Ask cash investors whether they intend to renovate, rent or transfer the contract. Buyers should explain the actual agreement, review rights and cancellation terms rather than leave sellers to infer them from an advertisement.
- Compare the itemized net. Cash home buyers who buy homes directly can explain which charges they pay. MHIC’s written agreement controls normal-cost coverage and no realtor commissions; seller payoffs still matter. Include a real estate agent’s realistic listing estimate.
- Confirm the work and possession scope. If you sell your house as is, document what stays and what condition is being accepted. For sellers with flood, pest or permit records, share the actual findings with the home buyer before relying on a settlement estimate.
When you sell your house, ask the home buyer to explain what any “stress free” service promise includes. Written terms, Louisiana succession authority and verified funding conditions provide the basis for a workable plan.
Probate, Foreclosure Deadlines, and Complicated Title Situations in Shreveport
Louisiana uses the term “succession” for estate transfer after death. Its affidavit route can include eligible immovable property, but the value cap alone does not establish signing authority. Court-ordered mortgage seizure and tax-lien enforcement also have different procedures; verify the actual file before planning a fast sale.
Small succession: the resident cap changed in 2026
The First Judicial District Court, Caddo Parish handles civil succession matters at 501 Texas Street, Shreveport, LA 71101. The Clerk of Court filing office is Room 103. Ask the clerk and succession counsel which procedure fits the estate.
Article 3421 defines the current Louisiana-domiciled small succession at $200,000 or less in gross property value at death. Act 293 of 2026 raised that resident threshold from $125,000 effective August 1, 2026. A nonresident’s ancillary succession instead uses $125,000 or less in Louisiana property at death.
If death occurred at least 20 years before the affidavit, Louisiana property of any value may fit the small-succession definition. This is a value-cap exception, not the ordinary waiting period. None of these categories by itself proves that the no-court affidavit procedure is available.
Immovable property can qualify, with important exclusions
Article 3431 permits qualifying no-court small successions for Louisiana domiciliaries who died intestate. The resident testate route requires no Louisiana immovable property and the required unanimous probate waiver. An inherited Louisiana house in a resident testate estate therefore cannot simply use that no-court testate route.
For a nonresident, the eligible categories are intestacy or a testament already probated by another state’s court. Article 3433 supplies the separate nonresident testate affidavit, legatee-signing and attachment requirements.
Under Article 3434, eligible immovables must be sufficiently identified and the affidavit and required attachments recorded in the conveyance records of the parish where the land is located. The qualifying route needs no Louisiana judicial opening; foreign probate is still needed for a nonresident testate estate. No blanket debt-free qualification is stated, and an affidavit does not eliminate liens or transaction-specific title requirements.
Signers and notice are separate from estate size
Article 3432 requires at least two persons for the intestate affidavit, including a surviving spouse, if any, and one or more heirs. With no spouse, at least two heirs sign; if there is only one heir, a second person with actual knowledge also signs. The article authorizes specified natural-tutor and curator signatures.
The current provisions do not state a universal post-death wait. When relying on notice to a non-signing heir, Article 3432 requires 30 days’ mailed notice without objection; inability to locate an heir after reasonable diligence is addressed separately. Have counsel confirm the affidavit, heirs, spouse or usufruct interests and required recordation before agreeing to a transfer. Our inherited-home guide helps frame the selling decision once authority is established.
Executory process is a court-ordered seizure and sale
Article 2631 permits executory proceedings for a qualifying mortgage evidenced by an authentic act with confession of judgment. This judicial route can proceed without the prior citation and judgment used in ordinary proceedings. Where executory requirements are not met, ordinary judicial proceedings are used.
Article 2634 provides for a petition requesting seizure and sale with the required evidence; the court orders issuance of the writ. Article 2721 requires personal or domiciliary written notice of seizure, including the sale’s time, date and place, Article 2642 defense/appeal information and housing-counseling information for residential property.
For covered loans and servicers, Regulation X generally bars the first notice or filing until the loan is more than 120 days delinquent, subject to due-on-sale, lienholder-joinder and applicable loss-mitigation rules. That federal filing restriction is not a Louisiana auction countdown.
Check the sale notice and servicer’s written terms
For an immovable public auction requiring two publications, R.S. 43:203 requires the first advertisement at least 30 days before sale and the second no earlier than seven days before and no later than the day before sale. Advertisement and sale days are excluded from the initial interval calculation. This schedule begins after court process and seizure, not at the first missed payment.
The Caddo Sheriff’s sale page lists civil sales normally on Wednesdays, excluding holidays, at 10:00 a.m., in Room G-1 or G-20, Caddo Parish Courthouse, 501 Texas Street. Confirm the actual case notice and current schedule directly with the Civil Department.
The Louisiana Housing Corporation guide describes servicer-arranged reinstatement as a lump-sum payment of arrears and applicable fees by an agreed deadline. Obtain the actual written amount, terms and payoff; this is not a universal statutory arrears-only cure right.
A completed direct sale can be one option if you have legal authority and sufficient time before the applicable deadline. An offer or signed purchase agreement does not pause foreclosure. Have an attorney assess any defense, appeal or post-sale issue; do not substitute tax-lien rules for mortgage proceedings.
Recorded title clouds need specific documents
Caddo Parish’s conveyance and mortgage records include deeds, mortgages, rights of way, powers of attorney, judgments and tax liens. For heirship, an actual code-enforcement lien or delinquent taxes, the selected title provider identifies the relevant record, authority, payoff or cancellation needed.
The clerk warns that a mortgage certificate is not a full title examination and that staff do not perform a complete title search. Work with the selected provider and Louisiana counsel on required curative measures before relying on a settlement date.
Legal and tax information only. MyHouseIntoCash provides direct purchasing solutions, not legal, tax, probate, financial or foreclosure-defense advice. Consult the court clerk, parish or city tax collector, real estate attorney, tax professional or other qualified adviser about your circumstances. We do not guarantee foreclosure prevention, court or succession approval, lien removal, property-tax forgiveness or title clearance.
Shreveport City and Caddo Parish Taxes: Check Both Balances
The Caddo Parish Sheriff’s Property Tax Department acts as parish tax collector at 501 Texas Street, Room 101, Shreveport, LA 71101. The City Revenue Division collects separate city taxes. The parish bill does not include Shreveport city taxes, so obtain both balances for your home sale.
Current delinquency interest and auction penalty
Current R.S. 47:2127 sets payment by December 31 of the tax year unless a statutory exception applies, with delinquency the following day, January 1. Interest runs from the day after taxes were due at 1% per month or any part of a month, noncompounding, subject to the statutory endpoints.
If the tax lien is offered at auction, a 5% penalty on statutory impositions is assessed; interest does not accrue on that penalty. R.S. 47:2153 addresses delinquency notice and the tax-lien certificate auction. Legally recoverable notice, advertisement and recording costs may be added. Request a parcel-specific payoff rather than apply a blanket collection percentage.
A tax-lien auction is a different process
The current tax-lien framework provides that auction and certificate recording do not by themselves terminate the owner’s ownership or possession. Subsequent judicial enforcement is distinct from a mortgage sheriff sale.
The Sheriff’s FAQ retains legacy tax-sale and 10% collection-fee language. The current 2026 statutes govern the interest and auction penalty stated here; confirm any additional charge’s authority and the current balance with the collector and closing provider. Do not treat an old online calculation as the final payoff.
The Sheriff’s FAQ also describes the eligible homestead exemption as the first $75,000 of market value, or $7,500 assessed value. In Caddo it does not apply to separate city taxes or fire-district fees. Confirm eligibility and both tax obligations rather than assume an exemption clears the account.
A normal-closing-cost provision does not forgive seller debt. Mortgage payoff, actual liens, taxes and other obligations still affect what you keep; compare the itemized seller net and the written agreement.
What Happens Between Accepting Your Cash Offer and Getting Paid in Shreveport?
The day labels illustrate a transaction that is ready to proceed. They are not a five-day payout guarantee. A succession, unresolved lien, payoff delay or signing requirement can extend the schedule. Confirm the selected closing provider’s funding and release conditions before arranging your move.
Confirm the sales price, possession, review rights, available settlement day, zero MHIC fees and no agent commission. Put normal closing-cost coverage in writing. Main Street Title’s local services include closing, escrow, title insurance and attorney services. Its listed title insurers are First American and Fidelity National; who pays a policy premium depends on the agreement.
Main Street Title, LLC / Neupert & Associates is a local Shreveport–Bossier closing, title-examination and succession-services candidate. No established MHIC partnership or comparative reputation ranking has been verified. Use the provider selected for the transaction.
Search Caddo Parish conveyance and mortgage records by owner names and legal description, including deeds, mortgages, judgments, rights of way, powers of attorney and tax liens; review releases and cancellations. A clerk-issued mortgage certificate does not replace the full examination.
For a title-insured sale, R.S. 22:512 generally requires a 30-year minimum search, extended as needed to reach an arm’s-length sale between unrelated parties. A Louisiana-authorized attorney examines the records and provides a written title opinion addressing ownership, recorded encumbrances, curative measures and overdue parish and municipal taxes. This insured-title requirement does not establish that every uninsured transaction must be conducted entirely by an attorney.
Main Street Title advertises abstracts, lien/judgment searches, tax reports and recording services. Review documented municipal notices and permit history where relevant. SWEPCO is the electric provider; confirm address-specific service arrangements. An ordinary electric bill is not presumed to attach to title as a lien.
The closing provider coordinates mortgage figures, releases or cancellations and verified succession authority. Obtain separate Caddo Parish and Shreveport tax balances, including applicable interest and legally recoverable charges. The current 1% monthly noncompounding tax rule and 5% tax-lien-auction penalty should be applied to the actual account, not substituted with legacy website percentages.
Identify what each exception requires before treating title as ready. Recording an affidavit or promising to pay a balance does not itself establish that all necessary curative work has been completed.
Civil Code Article 2440 permits sale of immovable property by authentic act or act under private signature, subject to Article 1839. For an authentic act, Article 1833 requires each executing party to sign before a notary or authorized officer and two witnesses; the parties, witnesses and notary sign, with legible printed or typed names beneath signatures. Separate times or places are permitted under Article 1833(B). The two-witness rule is specific to this form.
Article 2347 requires both spouses’ concurrence to convey or encumber community immovable property. A single name in the record does not resolve every community interest. Establish the appropriate owners, spouses, succession parties and signing method before scheduling.
The Act of Sale is submitted to the Caddo Parish Clerk of Court’s property records office at 501 Texas Street. Ask the selected closing office to confirm execution, recording, verified funds, outstanding payoffs and the conditions for releasing seller proceeds. Confirm the outgoing payment method and bank availability directly; no default wire, escrow-check or immediate-release practice is asserted here.
Shreveport and Nearby Communities Within About 75 Miles
We review homes in the Shreveport area and the following nearby communities: Bossier City, Benton, Haughton, Blanchard, Greenwood, Stonewall, Minden, Mansfield, Springhill, Vivian, Plain Dealing, Homer, Coushatta, Arcadia, Marshall (TX), Jefferson (TX), Carthage (TX), Longview (TX). The supplied Louisiana Census place coordinates and Texas Census place coordinates place these recognized municipalities within 75 straight-line miles of the city reference point. This is geographic context, not road mileage or a drawn purchase boundary.
Pan or zoom the Google map for context. It does not draw a 75-mile service boundary. Submit the actual address so we can confirm condition, ownership eligibility and an available schedule. For a home in Bossier or another parish, use its actual court, tax collector and recording office. Louisiana legal and tax guidance on this page does not govern the Texas communities.
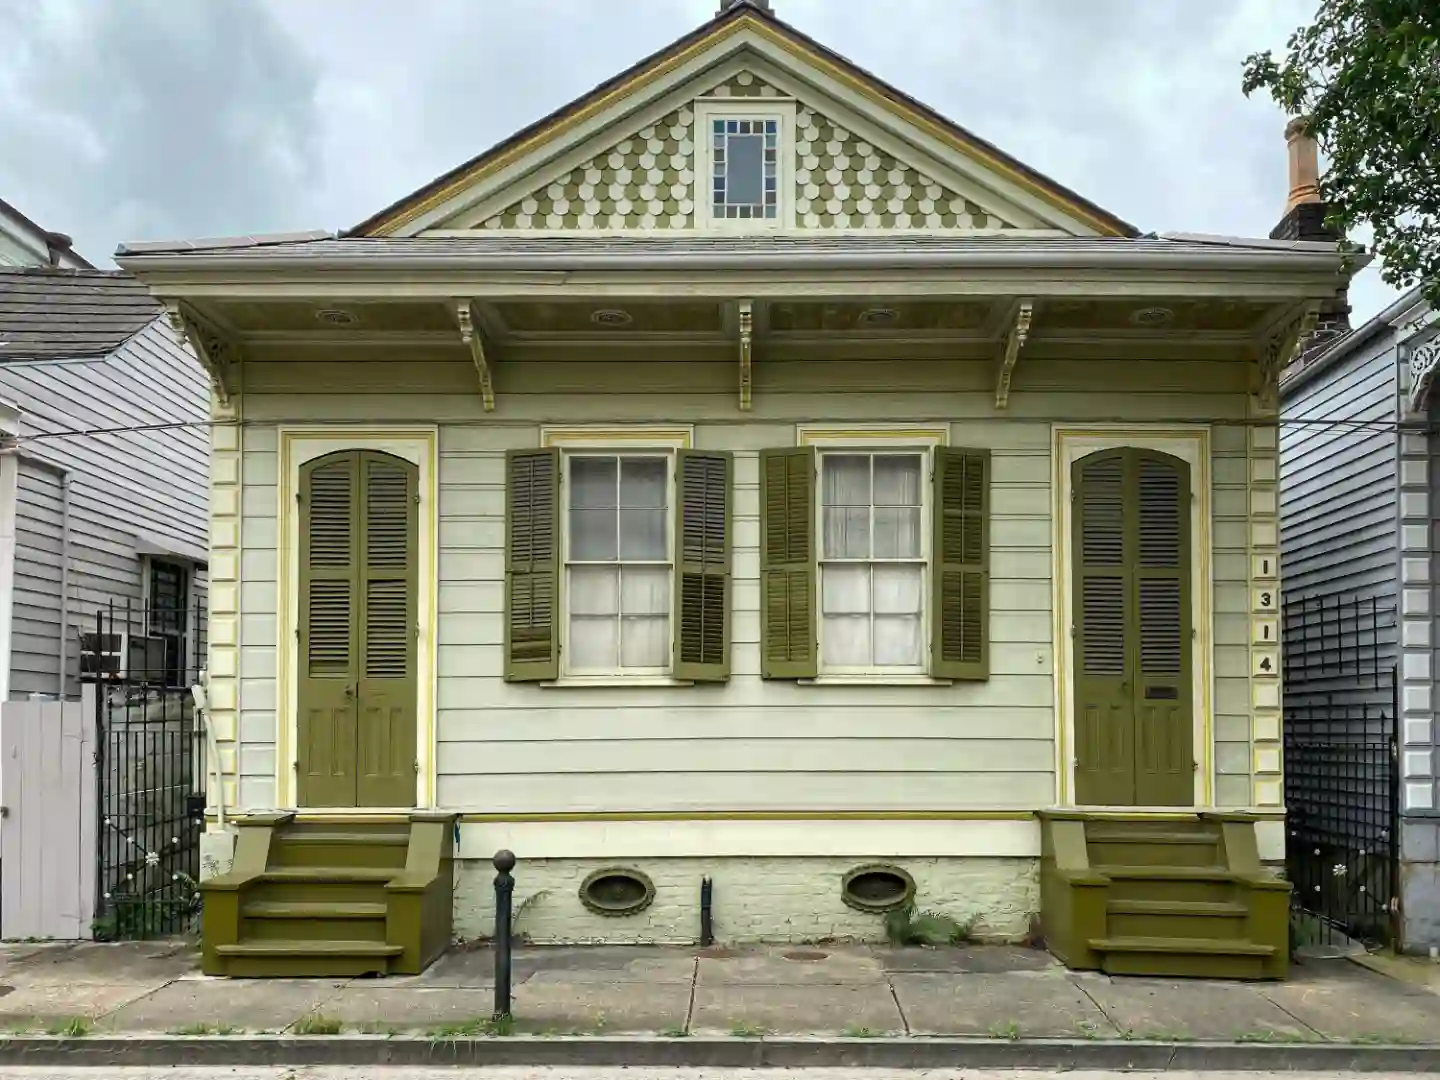
Representative house photo from the MyHouseIntoCash Louisiana media gallery.
See our Louisiana home-buying page for statewide service context. The FAQ delivery lists cover the named communities and documented postal overlaps; mailing names do not establish jurisdiction.
Shreveport Real Estate & Legal Terms Homeowners Should Know
Succession
Louisiana's estate-transfer process after death; an inherited-home seller needs paperwork establishing ownership and authority to convey. Confirm the succession route, owners and authority before agreeing to convey the home.
Louisiana Code of Civil Procedure Article 3431 — Small successions without judicial opening
Small succession
A statutory estate-size/category definition. The current resident cap is $200,000 gross at death; the nonresident Louisiana-property cap is $125,000. Meeting the cap alone does not establish eligibility for the affidavit route. Have counsel check domicile, testament and real-estate eligibility as well as gross value.
Louisiana Code of Civil Procedure Article 3421 — Small successions, as amended by Act 293 of 2026
Authentic act
A writing executed with the notary-and-two-witness formalities of Civil Code Article 1833; this is one permitted way to sign an immovable-property Act of Sale. Confirm this chosen form’s signers and witnesses with the closing office before scheduling.
Executory proceeding
A judicial seizure-and-sale process available for qualifying mortgages evidenced by an authentic act with confession of judgment. It can proceed without the prior citation and judgment required in ordinary proceedings. Have counsel review the actual petition, seizure notice and sale deadline promptly.
Louisiana Code of Civil Procedure Article 2631 — Use of executory proceedings
Homestead exemption
The sheriff's FAQ describes an exemption of the first $75,000 of market value, equivalent to $7,500 assessed value, for an eligible primary residence. In Caddo it does not apply to separate city taxes or fire-district fees, so sellers must review both tax obligations. Obtain both parish and city balances for the seller-net estimate.
Tax lien certificate
Under the current Louisiana tax-enforcement framework, the auction purchaser receives a recorded tax-lien certificate. The auction alone does not transfer the owner's possession or terminate ownership; lien termination and later judicial enforcement have separate rules. Ask the collector and counsel which current or legacy certificate and enforcement rules apply to the recorded file.
Louisiana Revised Statutes 47:2153 — Delinquency notice and tax-lien certificate auction
Shreveport Home-Selling FAQs
How can I sell my house fast in Shreveport without a listing?
Share the address, owners, occupancy, condition and preferred move date with MyHouseIntoCash. Review a written as-is cash offer and estimated seller net before deciding. A home with documented flood or termite damage needs a condition-specific review, while Louisiana succession and title requirements determine who can sign and when settlement is ready.
Which residential delivery ZIP codes overlap Shreveport?
The mapped standard street-delivery codes intersecting the city are 71033, 71047, 71101, 71103, 71104, 71105, 71106, 71107, 71108, 71109, 71111, 71112, 71115, 71118, 71119, 71129. This includes portions with Greenwood, Keithville and Bossier City mailing names. PO Box and unique institutional codes are excluded, including 71102, 71120, 71130, 71137, 71151, 71152, 71153, 71154 and 71156. Postal boundaries do not establish city limits, the correct parish or purchase eligibility; confirm the street with USPS ZIP Lookup.
Which residential delivery ZIP codes cover the nearby Shreveport–Bossier communities?
Bossier City: 71101, 71107, 71110, 71111, 71112; Benton: 71006; Haughton: 71037; Blanchard: 71107; Greenwood: 71033, 71119, 71129; Stonewall: 71078. Lists include full or partial municipal delivery overlaps. Blanchard 71009 is a PO Box code; its standard street-delivery overlap is 71107. Bossier City’s 71113, 71171 and 71172 PO Box codes are excluded. Barksdale AFB 71110 is a standard mapped overlap, but that does not establish privately transferable ownership or purchase eligibility. Confirm the actual address and title.
Which residential delivery ZIP codes cover the other Louisiana communities listed here?
Minden: 71055, 71073; Mansfield: 71052; Springhill: 71075; Vivian: 71082; Plain Dealing: 71064; Homer: 71040; Coushatta: 71019; Arcadia: 71001. Minden’s list includes the Sibley 71073 overlap; its 71058 PO Box code is excluded. These delivery references cover the named communities, not every ZIP inside an entire 75-mile circle. Mailing names and parish jurisdiction can differ.
Which residential delivery ZIP codes cover the East Texas communities listed here?
Marshall (TX): 75670, 75672; Jefferson (TX): 75657; Carthage (TX): 75633; Longview (TX): 75601, 75602, 75603, 75604, 75605. Marshall 75671 and Longview 75606, 75607, 75608 and 75615 are PO Box codes and are excluded. Louisiana succession, tax and Act of Sale guidance does not govern these Texas homes. Confirm each street address and its actual county authorities.
Is Shreveport a competitive real estate market?
Redfin’s displayed competition panel describes it as Somewhat Competitive with a score of 44/100. Its three-month narrative ending August 2026 reports a $200,000 median closed-sale price, down 5.7% year over year, and average market time of 54 days. A maintained home can merit a listing comparison; these measures do not determine an as-is offer for every condition.
What is the hardest month to sell a house?
A single three-month report does not establish the hardest month for Shreveport. The cited August 2026 snapshot shows reported average market time of 54 days, not a seasonal ranking or the full time to payment. Compare current condition-matched listings, buyer activity and the cost of waiting before choosing when to sell.
What is the minimum credit score required to buy a house in Louisiana?
There is no single score covering every mortgage program and lender. CFPB guidance explains that credit is one part of the lending decision. Ask the buyer’s lender or your own mortgage professional about the selected program. For a seller, cash home buyers should demonstrate available funds; a borrowing threshold is not the same as ownership authority or a clear title.
What famous people live in Shreveport?
Current private residency is not established by a list of famous people connected with the city. Visit Shreveport-Bossier’s music history highlights James Burton and Kenny Wayne Shepherd among its musical connections. Those connections should not be treated as confirmation of who lives here today or as a basis for pricing a nearby home.
Which neighborhood in Shreveport is considered the nicest?
There is no single objective ranking that fits every home buyer. Highland and South Highlands have documented historic architecture; their age and maintenance scope can be relevant to an older-home seller. Compare location-specific sales, present condition and your own priorities rather than assign one neighborhood an unsupported “nicest” label.
Are cash home buyers legitimate, and how do I avoid potential scams?
Evaluate the actual house buying company rather than assume a name or advertisement proves legitimacy. Verify its legal identity, track record, proof of funds, written price, review rights and possession terms. Use an identified local closing provider and ask how earnest money, any assignment rights and cancellation are handled. Louisiana title and succession requirements still matter when cash investors pay cash.
What should I check about Cedar Cash Home Buyers and other companies?
BBB’s Cedar Cash Home Buyers profile lists accreditation since March 10, 2023. BBB’s Home Buyer Louisiana USA LLC profile lists an A+ rating and accreditation since April 17, 2020. These are specific entity records, checked October 5, 2026; they do not prove the terms or service availability of any particular offer. Verify the buyer named in your contract and its funds independently.
Does a national buyer name have the same BBB record everywhere?
No single profile should be applied to every similarly named entity or affiliate. The Grapevine WeBuyHouses.com license-services profile lists an A+ rating but says it is not BBB accredited, so a blanket accreditation-since-2020 statement is not supported by that record. For BiggerEquity or another advertised brand, verify the actual purchasing entity and current independent record before relying on a historical rating claim.
How should I compare multiple cash offers?
Ask each home buyer for the legal purchasing entity, written price, itemized seller net, proof of funds, review terms and possession arrangements. Cash investors who buy houses for cash should explain how actual flood, pest or rehabilitation work affects their offer. Compare offers with a credible listing estimate from a real estate agent; the best price on paper may leave less money after terms and obligations are considered.
What makes a fair cash offer for an older home?
A fair cash offer should be supported by condition-matched sales and the actual work and carrying scope. Cash home buyers can explain the assumptions rather than apply a universal 70% of after-repair value formula. For historic stock, older paint or confirmed termite damage can change the necessary repairs. Compare the seller net with a realistic traditional sale before deciding.
Can I sell my Shreveport house as is with major repairs or flood damage?
You can request an offer without choosing to pay for major work first. We review the actual condition and agree on remaining belongings and work scope. In affected Red River-connected areas, water history, the effective FEMA designation and floodplain requirements can change the buyer’s evaluation. As-is terms do not allow concealment of known defects or remove applicable disclosure duties.
What should I check in “sell house fast Shreveport” offers?
Compare the written net, funds, review rights and possession terms, along with the title file’s feasible settlement schedule. A quick estimate from an online platform does not establish succession authority, resolve recorded liens or account for both city and parish taxes. Shreveport home buyers should explain those steps before you rely on payment.
Can I sell my house for cash in Shreveport if I have problem tenants?
We can review an occupied rental or disputed-possession situation. Share leases, rent and deposit records, access arrangements and the actual dispute. The agreement must address possession and existing rights; do not assume occupants must leave automatically for a sale. For an older rental, available paint, pest and permit records help define the review.
Can I sell a house with termites, and what insurance applies?
LSU AgCenter explains that native subterranean termites occur throughout Louisiana and can consume structural wood where cellulose and suitable moisture are available. A pest professional should assess mud tubes, discarded wings or damaged components. Confirmed treatment and structural work can affect the offer and negotiations; ordinary homeowners insurance does not cover termite or decay damage according to LSU guidance. No citywide infestation percentage is established here.
Can I sell a house in Shreveport’s river floodplain?
We can review the address and actual condition. The verified mechanism concerns localized low-elevation Red River-connected floodplain and backwater areas, including affected lakes and bayous. Water can rise from river backwater even with less local rain. Check the effective FEMA map and actual history. Ordinary homeowners coverage generally excludes flood; separate coverage may matter.
Can I sell an older home without removing all the paint?
You can request an offer without repainting first. Most covered pre-1978 sales still require known lead information and reports, prescribed lead information and a buyer inspection opportunity. A cash/as-is agreement does not remove those duties. Appearance cannot identify lead; use actual testing and repair records rather than assume all historic homes have the same hazard.
Can I sell my house before replacing a roof required for private insurance?
You can request a current-condition offer. The statewide Fortify Homes participant survey documents owners who needed roof replacement for private coverage, but it is not a Shreveport-wide underwriting rule. Ask the actual carrier about your roof and policy. New 2026 market entrants do not establish eligibility, and Louisiana Citizens is a last-resort option when private coverage is unavailable. Compare the verified coverage and repair plan with the written terms.
Which disclosures do sellers need before they sell a house as is?
Louisiana’s residential disclosure statute applies to covered transfers, with statutory exemptions including certain estate and court-ordered transactions. Confirm applicability with counsel or the closing provider. Selling as-is does not permit concealment of known defects, and federal lead requirements may also apply to covered pre-1978 homes.
Can I sell an inherited house with a Louisiana small-succession affidavit?
Eligible immovable property can be included, but qualification depends on domicile, testament status, gross value, signers and recording requirements. The resident cap is $200,000 gross at death effective August 1, 2026; the nonresident Louisiana-property cap is $125,000. Resident testate estates with Louisiana immovables do not qualify for Article 3431’s no-court testate route. Meeting a value cap alone does not authorize a sale.
When can heirs sell a house using small succession?
The current affidavit articles do not state a universal post-death wait or blanket debt-free qualification. Article 3432 requires 30 days’ mailed notice without objection when relying on notice to a non-signing heir; reasonable-diligence inability to locate an heir is addressed separately. The 20-year provision is a value-cap exception. Existing liens and transaction-specific title requirements still need attention.
Who signs the intestate small-succession affidavit?
At least two persons sign, including the surviving spouse, if any, and one or more heirs. Without a spouse, at least two heirs sign; if there is only one heir, a second person with actual knowledge also signs. Article 3432 authorizes specified natural-tutor and curator signatures. The nonresident testate route has separate rules. Have succession counsel verify the required parties and attachments.
Which court handles authority to sell an inherited house in Caddo Parish?
The First Judicial District Court, Caddo Parish, handles civil succession matters at 501 Texas Street, Shreveport, LA 71101; the Clerk filing office is Room 103. Qualifying affidavit successions can avoid a Louisiana judicial opening, but the actual eligibility and recordation requirements must be satisfied. Consult the clerk, succession counsel and closing provider.
How does executory mortgage foreclosure begin?
For a qualifying mortgage evidenced by an authentic act with confession of judgment, a creditor petitions the court for seizure and sale with required evidence. The court orders the writ, and the sheriff serves written seizure notice with sale details, defense/appeal information and residential housing-counseling information. Ordinary judicial proceedings apply where executory requirements are not met. Consult counsel about the actual case promptly.
How much notice precedes a Caddo mortgage sheriff sale?
For an immovable public auction requiring two publications, the first advertisement is at least 30 days before sale and the second is no earlier than seven days before and no later than the day before sale. Advertisement and sale days are excluded from the initial interval. The Caddo Sheriff lists civil sales normally Wednesdays excluding holidays at 10 a.m., in Room G-1 or G-20 at 501 Texas Street. Confirm the actual notice and current schedule; this is not a full default-to-sale timeline.
Will a cash offer stop foreclosure or reinstate my loan?
An offer or signed purchase contract does not pause proceedings. A completed sale can be one option if you have legal authority and sufficient time before the applicable deadline. Louisiana Housing Corporation describes servicer-arranged reinstatement as a lump-sum payment of arrears and applicable fees by an agreed deadline, not a universal statutory arrears-only right. Get the actual written terms and legal advice; no prevention guarantee is offered.
Which tax balances must sellers check before they sell a Shreveport house?
Caddo Parish’s sheriff acts as parish tax collector, while Shreveport’s Revenue Division collects separate city taxes. The parish bill does not include city taxes. Obtain both balances for the seller-net estimate. The eligible parish homestead exemption described in the Sheriff’s FAQ does not apply to separate city taxes or fire-district fees.
What are the current Louisiana property-tax deadlines and penalties?
Under current R.S. 47:2127, taxes are due December 31 unless a statutory exception applies and become delinquent the following day. Interest is 1% per month or any part of a month, noncompounding, from the day after they were due, subject to statutory endpoints. Offering the tax lien at auction adds a 5% penalty on statutory impositions, with no interest on that penalty. Legally recoverable costs may apply; request the actual payoff.
Does the current tax-lien auction automatically transfer my home?
Under the current framework, auction and tax-lien certificate recording do not by themselves terminate ownership or possession. Later judicial enforcement is a separate process. The Sheriff’s FAQ includes legacy tax-sale and collection-fee language; confirm the applicable certificate, current rules and payoff with the collector and qualified counsel rather than rely on an old percentage or assume mortgage rules apply.
What title work is needed before I sell a house in an insured Louisiana transaction?
R.S. 22:512 generally requires at least a 30-year search for a title-insured sale, extended as needed to reach an arm’s-length sale between unrelated parties. A Louisiana-authorized attorney provides the written title opinion, including ownership, recorded encumbrances, curative measures and overdue parish and municipal taxes. A clerk-issued mortgage certificate is not a complete title examination.
Who handles closing, the Act of Sale and spouse signatures?
Use the provider selected for the transaction. Main Street Title / Neupert & Associates is a local candidate, not a verified MHIC partner. Article 2440 permits an authentic act or an act under private signature. The authentic-act form requires the executing parties, notary and two witnesses; community immovable property requires both spouses’ concurrence. Confirm the chosen form, authority and signers with the closing office.
Will I receive payment on day five?
The day labels illustrate a ready transaction and are not a payout guarantee. Succession authority, recorded exceptions, payoffs, execution and recording can extend the schedule. Confirm the selected provider’s verified-funds and release conditions, outgoing proceeds method and bank availability directly before arranging a move.
How do I compare cash buyers for houses in Shreveport with an agent listing?
Compare the itemized seller net and actual terms from cash buyers who buy houses for cash with a realistic listing estimate. A traditional sale can have a higher gross price, but realtor fees, concessions, work and carrying expenses affect the result. A home buyer’s offer should use the actual condition, including flood, termite or older-finish findings. The best price for your decision includes timing, possession and the money you keep.
What does the repair estimator include?
It combines illustrative interior per-square-foot ranges with optional system allowances and a 15% contingency. These are planning assumptions, not measured local contractor repair costs, an inspection, appraisal, quote or required deduction from an offer. Actual flood restoration, wood damage, lead-safe work, permits, access, materials and concealed damage can change the scope substantially.
Sell Your House Fast With a Fair Cash Offer in Shreveport
Plan to sell your home fast with a clear next step.
Share the address, owners, occupancy, preferred move date and available flood, pest, paint or permit records. We’ll review the condition and written terms. Louisiana succession authority, separate tax balances and Act of Sale requirements help determine a feasible, hassle free settlement plan.
Request My Cash Offer → Call (866) 651-6617Official Shreveport Homeowner Resources
Check current parcel, case, tax, permit and recording instructions directly with the relevant authority. Nearby homes may use another parish or Texas county; Louisiana rules do not govern the Texas communities.
Residential delivery ZIP coverage references
The postal references show street-delivery classifications and full or partial municipal overlaps: Shreveport; Bossier City; Benton; Haughton; Blanchard; Greenwood; Stonewall; Minden; Mansfield; Springhill; Vivian; Plain Dealing; Homer; Coushatta; Arcadia; Marshall (TX); Jefferson (TX); Carthage (TX); Longview (TX). Confirm a specific street with USPS ZIP Lookup. A standard ZIP is not proof of residential use, privately transferable ownership, jurisdiction or purchase eligibility.