
Get a cash offer in 5 - 10 minutes • Orleans Parish, LA
Sell My House Fast in New Orleans: We Buy Houses in New Orleans As-Is
If you’re searching “sell my house fast in New Orleans,” call or share your address today. We buy houses in New Orleans as-is for cash; review a written offer and choose an available closing date after ownership and title checks.
- Sell in current condition
- No agent commission
- Normal closing costs paid
- Available date of your choice
New Orleans Market Watch
City data • three months ending September 2026
For New Orleans city, across all home types, the supplied Redfin city-market report records the following figures as of October 16, 2026:
These are three-month city figures, not September-only results or metro-area averages. Days on market measures marketing time, not the full time to receive closing funds. The same city report lists a 95.8% sale-to-list ratio and price drops on 40.7% of listings.
For a seller, that makes the cost of waiting worth pricing into the decision. Compare a realistic listing outcome with a written direct offer, especially when a property needs work. These citywide figures do not establish your home’s value or predict its selling time.
Sell It Exactly as It Sits in New Orleans
Our as-is purchase policy lets you request an offer before preparing the house for a listing. A property review may still be needed to establish the offer; the agreed terms belong in your purchase contract.
-
Don’t paint
Skip interior touch-ups and exterior repainting. -
Don’t replace flooring
Leave stained carpets, worn hardwoods or cracked tile. -
Don’t fix the roof
We buy with active leaks, missing shingles or aged roofs. -
Don’t stage the home
Avoid professional staging and decluttering costs. -
Don’t clean it out
Take only what you want; leave unwanted furniture, trash and clutter behind. -
Don’t schedule dozens of showings
Skip open houses, lockboxes and disruptive walk-throughs.
That choice matters for historic New Orleans roofs: HDLC roofing guidance documents slate, terra-cotta tile, metal and asphalt shingles, alongside gabled, hipped and flat or parapet roof forms. Exterior roofing work within historic jurisdiction can require a Certificate of Appropriateness and permits. Check the approval path before committing to repairs solely to sell.
Read our guide to selling a house as-is or see how the direct-offer process works.
What a New Orleans House Needs You to Look at Before Selling
New Orleans cash house buyers need to evaluate the building in front of them. The City’s building-types guide documents Creole cottages from the 1790s–1870s, center-hall cottages from the 1830s–1880s and shotguns from the 1830s–1950s. Those are historic building-type ranges, not the age distribution of today’s entire housing stock.
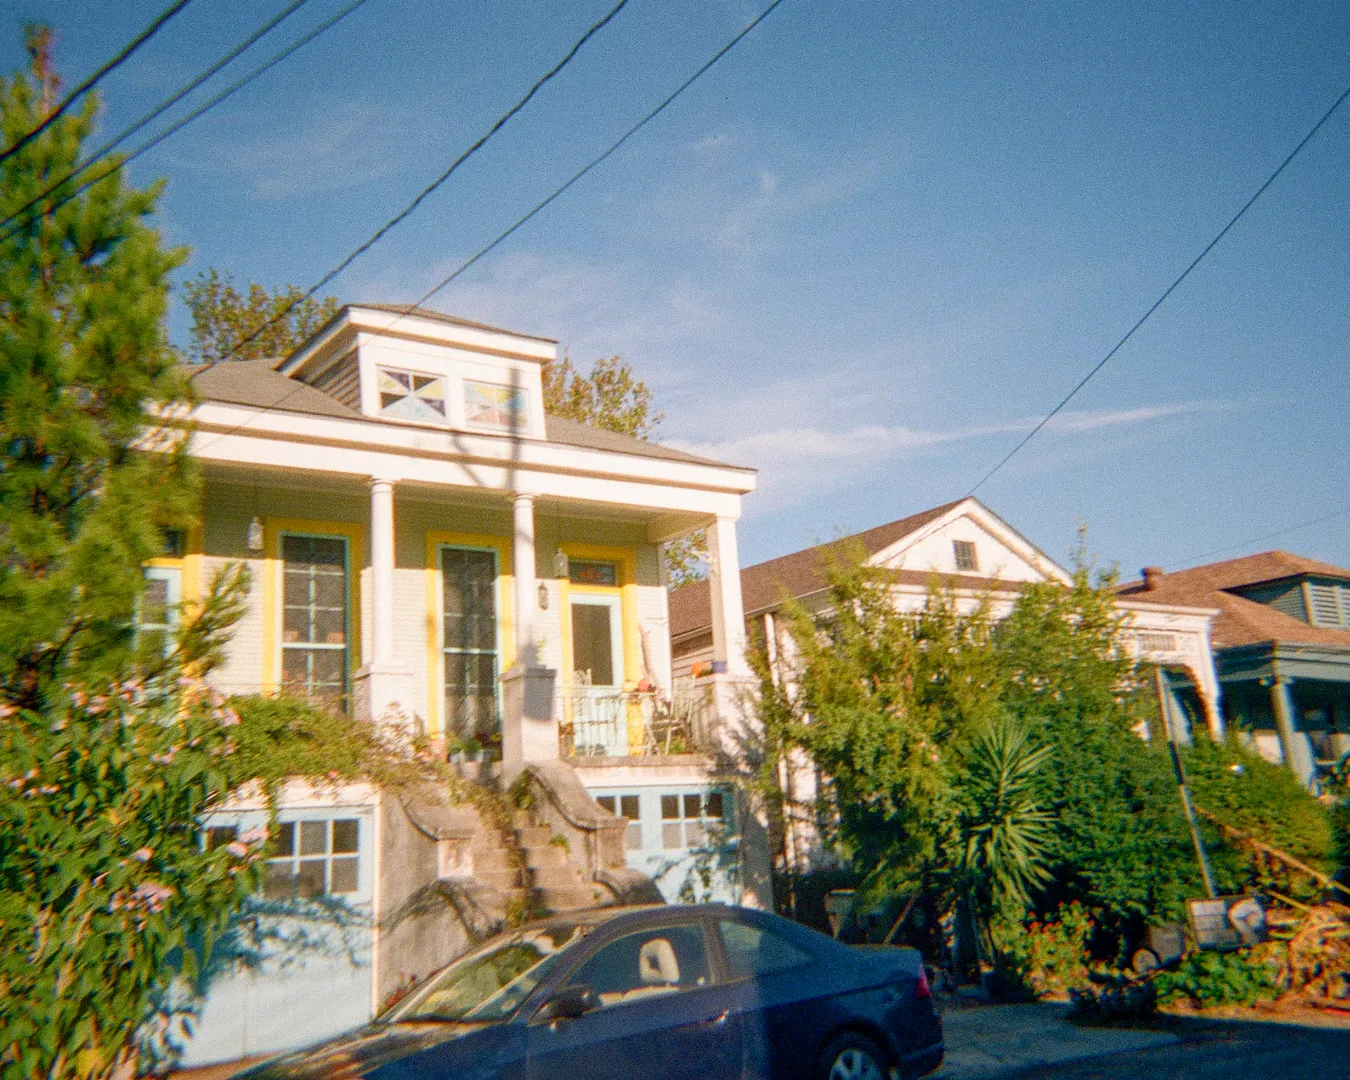
The same HDLC architectural source describes wood-frame homes with weatherboard siding and early Creole cottages with brick-between-posts or masonry construction. Raised masonry piers and crawlspaces occur in historic housing; center-hall cottages are specifically documented on piers. The City’s masonry guidance also describes brick and concrete-block foundations and piers. These examples do not establish citywide shares of foundation or wall types.
For your sale decision, identify the actual wall, roof and foundation systems before comparing repair bids. A cosmetic allowance alone may miss work below a raised floor or behind exterior siding.
Flood exposure needs an address check
NOLA Ready’s flooding profile identifies intense rainfall, overwhelmed drainage, storm surge and levee or floodwall failures. AE and VE are the City’s highest mapped flood-risk zones, while flooding can affect the entire city. Its tropical-cyclone profile also documents wind hazards.
Gather your property’s actual flood and repair history and use the FEMA Flood Map Service Center for an address-specific review. Neighborhood history alone cannot establish present damage, elevation or insurance cost.
Insurance costs need a current quote
Louisiana’s April 30, 2026 insurance update reports three newly licensed homeowners insurers through April, with finalized changes including CURE −10% and USAA +9.2%. These are mixed statewide changes, not measured New Orleans premiums.
LDI’s homeowners guidance identifies Louisiana Citizens as the insurer of last resort when private coverage cannot be secured. Most homeowners policies exclude flood coverage. Compare address-specific homeowners and separate flood quotes before estimating the cost of keeping or listing the property.
Could property condition affect insurance or a rental-property review?
Louisiana Citizens’ underwriting standards, §12 consider construction, heating, wiring, previous fire or other damage, deterioration, vacancy, overcrowding, rubbish and flammable-material storage. These are review criteria, not automatic denials by every insurer.
The Coastal Plan statute requires insurable condition. Use, occupancy or repair condition can make a structure uninsurable under that plan; buildings begun on or after July 29, 1970 must substantially comply with the specified code, including design-wind requirements. Ask the actual insurer how your property is evaluated.
For rental units, the City’s Healthy Homes inspection attestation addresses safe electrical systems, functioning plumbing and hot water, working HVAC, weather-tight roofs and mold conditions. Those rental standards are not a mandatory pre-sale four-point inspection.
Local Repair Problems That Can Change the Selling Decision
The following mechanisms are documented local concerns. Each is a regional tendency; none establishes that your house is affected or that a particular neighborhood has a measured defect rate.
Termites and concealed timber damage
The City’s termite-control agency describes Formosan subterranean termites as well established in metropolitan New Orleans and the primary local structural pest. Subterranean termites consume wood, use concealed entry paths and mud tubes, and can maintain aboveground colonies where moisture persists. Historic wood framing and sills need attention; newer construction is not exempt.
Look for mud tubes, dirt veins, galleries or weakened timber. Concealed damage can precede visible insects. Obtain a pest evaluation and a structural repair assessment when appropriate. As a practical inference, confirmed treatment and timber-repair costs can change a buyer’s repair request; damage does not automatically defeat financing or coverage.
Unequal support and subsiding soils
The City’s subsidence profile explains that drained organic soils shrink and oxidize while young sediments compact. Unequal support movement can cause differential foundation settlement. Rates vary spatially, with higher subsidence identified in developed former marshland.
Progressing diagonal masonry cracks, bowed or leaning walls and out-of-square openings warrant engineering evaluation; those signs alone do not prove subsidence. The City documents increased construction and maintenance costs. In a sale, an unresolved scope may influence negotiations or lender review, so compare an engineer-informed repair plan with the as-is terms.
Moisture, wood rot and hidden sills
HDLC exterior-woodwork guidance explains that persistent rain, leaks, ground contact or condensation can support fungal decay. Incompatible overcladding can trap moisture and hide deterioration, including near porch bases, sills and masonry piers.
Soft or darkened wood, peeling paint, dampness and water stains call for investigation of the moisture source before finish repairs. Selective timber repair may be needed; hidden framing makes a retail repair budget less certain. Check HDLC jurisdiction and design guidance before scheduling regulated exterior work.
The City’s property-maintenance code guidance also identifies termite-damaged load-bearing members, rotted columns, leaning or missing piers, sagging foundations, loose or leaking roof coverings and flashing, and drainage directed beneath raised houses. These are documented review points, not a ranking of common sale-inspection failures.
If a buyer or lender needs additional condition evidence, that may increase repair allowances or prolong review; some transactions may be renegotiated or withdrawn. We buy houses in New Orleans with condition issues, subject to property review and mutually acceptable terms. Compare written numbers rather than assuming every issue must be repaired first.
Selling a House in New Orleans’s Neighborhoods
Historic-district records help identify what to evaluate, rather than predicting an owner’s reason for selling. The seller scenarios below are practical examples, not measured neighborhood behavior. “Resolve” means evaluating a purchase that accounts for the condition; repair or title clearance is never guaranteed.
| Neighborhood / District | Housing Profile | Common Challenges We Resolve | Seller Scenario |
|---|---|---|---|
| Tremé | 1830s Creole cottages, 1840s townhouses and 1880s–1890s double shotguns. | Check moisture penetration and deterioration of historic exterior components; prevalence is unmeasured. Inspection guidance | If a rehabilitation scope is substantial, compare preservation-sensitive bids and timing with an as-is offer. |
| Bywater | Predominantly single-story wood-frame historic residences with gabled or hipped roofs; shotguns and Creole cottages. | Where timber damage is confirmed, obtain pest and repair evaluations; local termites do not establish the share of affected homes. Inspection guidance | An owner with damaged sills can compare documented repair costs with a direct offer. |
| Mid-City | Substantial development around 1900–1940; wood-construction shotguns, raised-basement bungalows and two-story houses. | The district history documents Katrina/Rita flooding and later siding, window and door alterations; assess current repairs individually. | If storm rehabilitation remains incomplete, compare the remaining scope with an as-is sale. |
| Algiers Point | Major growth in 1850–1900; Greek Revival, Italianate and Victorian houses, later rebuilding, and many raised wood structures. | Inspect moisture-exposed raised sills, porches and other timber components; no district-wide damage rate is established. Inspection guidance | For a raised historic home, price specialist work before choosing rehabilitation or a direct sale. |
AS-IS Repair Cost Estimator
Use this tool for a broad planning estimate, not an inspection, appraisal, contractor quote or guarantee. Actual costs can vary substantially with scope, materials, labor, permitting, access and concealed damage.
In New Orleans, concealed wood decay or site-specific foundation movement can make floor-area allowances incomplete. Add separate specialist allowances only when they are outside the work already included in your per-square-foot figure.
Cash Sale vs. Traditional Listing in New Orleans
A traditional sale may produce a higher gross price, but commissions, seller closing costs, repairs, concessions and ongoing holding expenses reduce the amount you ultimately keep. A direct cash sale generally prioritizes speed, certainty and convenience rather than the highest possible gross price.
New Orleans’s reported 70 median days on market is a useful planning reference, not your property’s schedule. With a raised historic home, include any engineer, pest-treatment or HDLC-sensitive repair scope in the comparison rather than treating all preparation as cosmetic.
| Dimension | Traditional Listing | Direct Cash Sale |
|---|---|---|
| Gross Price | Potentially higher gross price | Usually lower than full retail value |
| Commissions | Agent commission may apply | No agent commission |
| Closing Costs | Seller closing costs may apply | MHIC pays normal closing costs |
| Property Condition | Repairs or buyer credits may be requested | Property sold as-is |
| Contingencies | Financing and appraisal contingencies | No buyer-financing contingency |
| Timeline | Longer and less predictable timeline | Seller selects an available closing date |
The direct-sale column describes MHIC’s offered purchase approach, subject to the written contract. Existing mortgages, back taxes, liens and other seller obligations can reduce net proceeds even when MHIC pays normal transaction closing costs. A title issue or missing authority can delay either type of sale.
Compare Your Estimated Selling Options
Use our adjustable calculator to compare a traditional listing with a direct cash sale using your property’s estimated value and expenses.
Use the Net-Proceeds Calculator →Comparing cash home buyers in New Orleans? Ask for the purchase price, conditions, buyer funding arrangements and expected deductions in writing. Our guide to how cash buyers calculate offers explains the pricing conversation.
Probate, Foreclosure Deadlines, and Complicated Title Situations in New Orleans
A direct offer is one possible selling option when the owner has legal authority to sell and enough time to finish the transaction. A signed purchase agreement does not stop a court sale or establish an heir’s authority.
Inherited homes: Louisiana’s small-succession affidavit
Louisiana’s small-succession affidavit procedure permits an out-of-court route for eligible estates. Under Article 3421, the gross-value limits at death are $200,000 for a Louisiana domiciliary and $125,000 of Louisiana property for a nonresident ancillary succession. Act 293 of 2026 increased only the Louisiana-domiciliary limit, effective August 1, 2026. These are gross values, not equity after debts. A death at least 20 years before the affidavit provides an alternative for Louisiana property of any value.
Real estate can be included for qualifying intestate estates. A Louisiana-domiciled person who left a will and owned Louisiana real estate cannot use this affidavit route for that property. A qualifying nonresident testate estate can include Louisiana real estate when another state’s court has probated the will. Article 3431’s eligibility rules matter as much as the dollar limit.
Affidavit signatures, notices, exclusions and recording
For an intestate affidavit, Article 3432 generally requires at least two people, including the surviving spouse if any and one or more heirs. Without a surviving spouse, at least two heirs sign; a sole heir signs with another knowledgeable person. Natural tutors and curators may sign for minors or interdicts as the article permits.
There is no general post-death waiting period stated for that intestate affidavit. A non-signing heir must be unlocatable after reasonable diligence or receive 30 days’ notice by U.S. mail without objection. The 20-year alternative is not a waiting period for every succession. Review the required heir-notice provisions with counsel before relying on them.
For the nonresident testate route, at least two people sign, including the spouse if any and one or more legatees; without a spouse, two knowledgeable people sign. Non-signing legatees require 30 days’ mailed notice without objection. Attach the certified foreign probate order and will. The separate Louisiana testate/no-immovable route requires all heirs and legatees, including the surviving spouse, and the required waivers; it does not authorize a Louisiana inherited-house transfer when that decedent owned Louisiana immovable property.
Missing signatures, consents or notices, or exceeding the applicable gross-value limit without the 20-year alternative, can prevent use of the route. Articles 3421 and 3431 do not state a categorical debt-free requirement, but the affidavit does not adjudicate creditor disputes. Article 3434 requires recording an affidavit affecting immovable property in the property’s parish conveyance records. An eligible route does not require a Louisiana judicial opening or hearing; eligibility alone still does not prove that a particular signer can sell.
When a court succession is needed, contact the Civil District Court for the Parish of Orleans; Clerk’s Civil Division, Successions — Docket 1, at 421 Loyola Avenue, New Orleans, LA 70112; Civil Division filing office, Room 402 (official hours and locations). Bring your ownership and succession documents to the closing professional before choosing a firm date. Our inherited-house selling guide explains the purchasing option.
Mortgage foreclosure: use the actual notice and scheduled sale date
Louisiana mortgage foreclosure is judicial. A conventional mortgage can be enforced through ordinary court proceedings or expedited executory process. Executory process begins with a petition for seizure and sale and the authentic evidence required by Article 2635; the court then orders a writ of seizure and sale under Article 2638. Ordinary enforcement requires a judgment before enforcement under Article 3722.
The 60-day rule is not a full foreclosure timeline. R.S. 13:3852 bars the initial sheriff’s sale from being scheduled earlier than 60 days after the signed court order commanding the writ. Service and publication requirements also apply. No verified New Orleans practical average from first default notice to sale is supplied, so do not plan around a fixed total duration.
Seizure notices, publication, federal timing and appeal deadlines
Article 2721 requires personal or domiciliary service of the executory seizure notice, the Article 2642 defense/appeal provisions, sale time, date and place, and residential housing-counseling information. For an online auction, the seizure notice or a later notice served at least three days before sale must identify its date, bidding-opening time and platform address.
The statutory seizure-notice form states a 15-day period after service of the seizure notice for a suspensive appeal in executory process. Have an attorney review your actual papers promptly; this is not a deadline MHIC can extend.
Under R.S. 43:203, an initial immovable-property sale requires at least two published notices. The first precedes the sale by at least 30 days; the second runs within seven days before sale and no later than the preceding day. Exclude the first-publication and sale dates when counting the required interval. A rescheduled sale can have different publication requirements; see also Article 2722 and Article 2331.
The former Article 2639 three-day demand-for-payment provision was repealed in 2003; it is not a current universal pre-seizure requirement. For mortgages and servicers covered by Regulation X, §1024.41(f)(1), the first foreclosure notice or filing generally cannot occur until the loan is more than 120 days delinquent, subject to due-on-sale and other-lienholder exceptions. That federal prefiling protection is separate from Louisiana’s post-order scheduling rule.
Article 2340, applied to executory sales through Article 2724, allows prevention of the sale before adjudication by paying the sheriff the judgment amount, interest and costs. This is full payoff. A universal Louisiana right to reinstate an accelerated loan solely by paying arrears was not verified; review the mortgage, loan program and any lender loss-mitigation agreement with a qualified professional.
As a legal synthesis of Article 2371 and the pre-adjudication payoff rule, the borrower has no general post-sale redemption period after a completed ordinary Louisiana mortgage sheriff’s sale. This concerns mortgage foreclosure, not property-tax lien enforcement or tax-sale redemption.
The OPSO official real-estate sales portal lists scheduled, stopped and completed cases. Its stated venue is the first-floor lobby of Orleans Parish Civil District Court, 421 Loyola Avenue, New Orleans, LA 70112; auctions are Thursdays at noon unless otherwise advertised. Verify the case-specific listing and court papers. An off-market closing may be an option before a sale only with sufficient time, authority and title readiness; no purchase offer guarantees foreclosure prevention.
Back taxes, recorded claims and municipal concerns
The City’s Bureau of Treasury collects Orleans Parish ad valorem property taxes; the assessor values property. For the 2026 bill, the City permitted payment through February 28, 2026 before monthly interest, with the delinquency/interest period beginning March 1. Verify the actual bill and year rather than applying a general statewide December 31 date.
R.S. 47:2127(B) provides simple interest of 1% per month or part-month on delinquent statutory impositions until paid or a tax lien certificate issues. If offered at tax-lien auction, a 5% penalty on statutory impositions applies; that penalty does not itself bear interest. Other authorized costs can apply. Request the current payoff instead of estimating an old balance.
The Treasury FAQ distinguishes pre-2026 tax sales from tax-lien certificate auctions and says the certificate auction date will be announced when scheduled. Mortgage sheriff’s sales and tax-lien auctions follow different processes.
Have the selected title professional investigate heirship questions, recorded mortgages or judgments, back taxes and any recorded municipal enforcement claims. The Department of Code Enforcement handles maintenance enforcement and adjudication at 1340 Poydras Street, Suite 1100; (504) 658-5050. The Department of Safety and Permits, Building Division handles construction compliance at the same street address, Suite 800, with applications and searches through One Stop App. Compare property records with any altered siding, roofing or incomplete rehabilitation before assuming all work was approved.
The recording destination is the Orleans Parish Clerk of Civil District Court, Land Records Division, 1340 Poydras Street, 4th Floor, New Orleans. It is the consolidated office for sales, mortgages and other land instruments; the former Mortgage, Conveyance and Notarial Archives offices are no longer separate recording destinations. An identified title issue may require releases, additional documents, consents or a court process; clearance is not guaranteed.
My House Into Cash offers direct purchasing solutions, not legal, tax, probate, foreclosure-defense or financial advice. Consult the court clerk, Treasury, a Louisiana real-estate attorney, tax professional or another qualified professional about your circumstances. We cannot guarantee court approval, lien removal, tax forgiveness, title clearance or foreclosure prevention.
What Happens Between Accepting Your Cash Offer and Getting Paid in New Orleans?
The days below are illustrative working-day targets, not a promised five-day closing. An available date depends on the property, seller authority, title work, required payoffs, document availability and confirmed funds. A succession, disputed claim or missing release can take longer.
Day 0 target: mutual agreement and purchase contract
Confirm price, condition, access, closing-cost allocation and an available date in writing. MHIC charges no service fee or agent commission and pays normal closing costs under the agreed terms. Existing debts and seller obligations still affect your net proceeds. For community immovable property, Louisiana law requires both spouses’ concurrence; identify required sellers before scheduling signing.
Days 1–2 target: title search and municipal due diligence
Your selected settlement professional searches the Orleans Land Records conveyance, mortgage and Unified Indexing System records. Modern records are available by paid online subscription or free public access at the clerk’s office; historical originals can require office research.
For a title-insured sale, R.S. 22:512 requires a Louisiana-licensed attorney’s written title opinion. It covers ownership; mortgages, judgments, liens and privileges; servitudes, rights of way, leases, options, rights of first refusal and usufructs; the legal description; curative work; and overdue parish and municipal property taxes. The sale search covers at least 30 years and extends farther if needed to reach an arm’s-length transfer between unrelated parties. The separate federal-judgment mortgage-record search covers 20 years. These are title-insurance requirements, not a universal rule for every uninsured cash sale.
Compare any identified code or permit concerns with the City’s enforcement records and permit process. Entergy New Orleans, LLC is the primary electric utility. Ask it about your service account and move-out arrangements; an ordinary electric balance is not established here as a title lien.
Days 2–4 target: payoffs and any required title clearance
The selected agent coordinates current mortgage payoffs, any necessary recorded releases, succession documents and Treasury tax figures. The Bureau of Treasury collects the tax payment; use its current payoff, including applicable interest and costs. A recorded claim cannot be assumed erased merely because the sale is for cash.
Crescent Title, LLC is an independent local candidate with attorney-led closings and Uptown, Lakeview and Marigny offices; its Uptown office is 7835 Maple Street, New Orleans, LA 70118. It describes search, commitment, curative work, payoff coordination, lien releases, funding and recording. No MHIC business relationship or endorsement has been verified. Confirm who will handle your transaction and what outstanding work remains.
Day 5 target, if ready: act of sale, recording and authorized payout
Louisiana uses an act of sale for immovable property. Civil Code Article 2440 allows an authentic act or an act under private signature; it does not mandate a general warranty deed for every private sale. For an authentic act, executing parties sign before a notary or other authorized officer and two witnesses, who also sign, with legible printed or typed names below. Parties may sign at different times or places if each execution satisfies the requirements.
The private-signature alternative has its own acknowledgment rules under Article 1836. R.S. 35:12 addresses full names, permanent mailing addresses, printed notary and witness names, and notary identification or applicable attorney bar-roll number. Missing required identification can cause recording rejection. Follow the closing professional’s document instructions.
The agent arranges recording with the Land Records Division at 1340 Poydras Street, 4th Floor. Team Title’s seller checklist documents wire transfer as a local proceeds option and asks for a voided check or wiring instructions in advance or at closing. No market-wide evidence establishes wires as the dominant method. Confirm your agent’s disbursement method and timing.
Under R.S. 22:532, disbursement follows escrow instructions or the signed settlement statement and sufficient funds in a permitted form, including unconditionally received wires or specified bank checks. Signing does not guarantee immediately available funds in your bank account.
Who handles settlement, title insurance and remote signing?
Louisiana law permits a title insurer or producer to act as a fiduciary closing, escrow or settlement agent. The attorney-opinion requirement above applies to title-insured property; it does not establish that an attorney must personally attend every uninsured cash-sale signing.
An owner’s title policy and a lender’s policy protect different interests. R.S. 22:531 requires a written explanation when a purchase-money lender’s policy is issued without an owner’s policy request: the lender’s policy does not protect the buyer-owner, and an owner’s policy may be purchased. A universal local rule charging the seller that premium was not verified; check the contract.
Southern Title documents office, mobile and mail-away closings. Availability depends on your transaction and documents; arrange the signing method with the selected agent.
New Orleans Google Map, Nearby Communities and Residential ZIP Codes
Use the Google map below to explore New Orleans and the surrounding area. New Orleans and Orleans Parish are coterminous, as the City’s community profile explains. Purchase availability depends on review of the specific property and address.
The 18 nearby residential communities listed below are supported by Census incorporated-place records and Census designated-place records. Send the actual address to confirm whether we can make an offer.
Pan or zoom to explore the area, or open New Orleans in Google Maps. The map and ZIP list provide geographic context; MHIC reviews each property individually.
For other Louisiana addresses, see our Louisiana home-buying page.
Which residential ZIP codes are included in New Orleans and these surrounding communities?
The table covers New Orleans and all 18 communities above, including smaller ZIP-area overlaps. It cross-references the Census 2020 ZCTA-to-place relationship file; the City’s All In for New Orleans survey map also identifies the city’s residential ZCTAs.
| Community | Residential ZIP-area reference |
|---|---|
| New Orleans | 70037, 70112, 70113, 70114, 70115, 70116, 70117, 70118, 70119, 70122, 70124, 70125, 70126, 70127, 70128, 70129, 70130, 70131 |
| Metairie | 70001, 70002, 70003, 70005, 70006, 70062, 70065 |
| Kenner | 70003, 70062, 70065 |
| River Ridge | 70062, 70123 |
| Harahan | 70123 |
| Gretna | 70053, 70056 |
| Harvey | 70053, 70058, 70072 |
| Marrero | 70058, 70072 |
| Westwego | 70072, 70094 |
| Belle Chasse | 70037 |
| Chalmette | 70032, 70043 |
| Arabi | 70032 |
| LaPlace | 70068, 70084 |
| Luling | 70039, 70057, 70070 |
| Destrehan | 70047 |
| Slidell | 70445, 70458, 70460, 70461 |
| Mandeville | 70448, 70471 |
| Covington | 70433, 70435 |
| Hammond | 70401, 70403, 70454 |
Census ZCTAs approximate ZIP delivery areas; they are not current USPS delivery-route boundaries. Communities can share ZIP codes, and a mailing city can differ from the municipality. Institutional and PO-box-only codes are not the focus of this house-selling list. Confirm the exact property ZIP with USPS address lookup and send us the street address. This table covers the named communities; confirm other addresses individually.
New Orleans Cash-Sale Questions, Answered
How do I sell my house for cash in New Orleans?
Call (866) 651-6617 or send the property address and condition through the offer form above. Review a written as-is offer and its conditions, then select an available closing date after ownership, title and funds are confirmed. Existing debts and title issues affect net proceeds and timing.
Can I sell my New Orleans house as-is if the inspection finds termite or foundation damage?
Yes, you can request an as-is offer for a house with condition issues. New Orleans guidance documents concealed termite damage, wood decay and site-specific settlement concerns. Property review establishes the proposed price and terms; an inspection finding does not automatically make every buyer or lender decline a property.
Does a Louisiana small-succession affidavit let every heir sell an inherited house?
No. Louisiana’s current gross-value limits are $200,000 for a Louisiana domiciliary and $125,000 of Louisiana property for a nonresident ancillary estate, with a separate 20-year alternative. Testacy, real-estate eligibility, signatures, notices and recording also matter. A Louisiana-domiciled decedent who left a will and Louisiana real estate is excluded from this affidavit route. Ask a Louisiana attorney to establish sale authority.
Can a cash offer stop an Orleans Parish foreclosure?
An offer or signed contract does not stop foreclosure. A completed sale may be an option only when the owner has authority and enough time before the scheduled sheriff’s sale. Louisiana uses judicial proceedings; the 60-day minimum runs from the signed writ order, not the first missed payment. Use your actual court papers and obtain legal advice promptly.
Will I receive my money immediately when I sign?
Not necessarily. The settlement agent must have sufficient permitted funds and follow the escrow instructions or signed settlement statement. Wire transfer is a documented local option, but the agent’s disbursement timing and your bank’s availability timing must be confirmed.
Do you consider houses in every residential ZIP listed for the surrounding area?
Send the street address in any of the listed residential ZIP areas for review. The table includes all 18 named surrounding communities, shared ZIP areas and smaller overlaps. Census ZCTAs approximate delivery areas, so USPS address lookup is the final postal check. The Google map and ZIP list provide geographic context; MHIC reviews each property individually.
For the legal and closing details behind these answers, use the source-linked succession and foreclosure section and Louisiana’s settlement-funds statute. To sell a house fast in New Orleans, start with the actual address and documents so the offer and possible closing date can be evaluated together.
New Orleans Real Estate & Legal Terms Homeowners Should Know
- Authentic act:
- A Louisiana instrument executed before a notary or other authorized officer and two witnesses, with the required signatures. For an owner selling a home, it describes a legal execution form for the act of sale. Source
- Predial servitude:
- A burden on one owner's property for the benefit of another owner's property. A seller's title review needs to identify such recorded rights because they affect the rights being conveyed. Source
- Small succession:
- An estate meeting Louisiana CCP Article 3421 gross-value or 20-year criteria. Meeting the definition alone does not authorize every inherited-house transfer; the separate affidavit eligibility rules must also be satisfied. Source
- Executory process:
- Expedited judicial seizure and sale based on a qualifying mortgage or privilege with a confession of judgment. A seller receiving these court papers must work from the actual seizure notice and sale date. Source
- Homestead exemption:
- A legally allowed reduction of taxable assessment for an eligible home. The Orleans Parish Assessor handles exemption eligibility; a seller must distinguish that assessment relief from payment of the actual Treasury tax bill. Source
- Certificate of Appropriateness:
- HDLC approval for regulated work on a landmark or property within its historic-district jurisdiction. A seller planning exterior rehabilitation should establish this approval requirement before pricing or scheduling the work. Source
Ready to Compare an Offer for Your New Orleans House?
Start with the address and the facts you already have.
For a historic raised house, an inherited property or a home with unfinished repairs, share the condition and any relevant ownership papers. We can discuss a direct offer while the selected professionals determine the title and closing requirements.
Official New Orleans Homeowner Resources
Use these official records and agencies to check the property, outstanding obligations and the steps that apply to your sale.