
A Competitive Market Still Calls for a Property-Specific Decision
The supplied Redfin Hammond city report describes the all-home-types market as Very Competitive, with an 81/100 Compete Score, for the three months ending September 2026; the chart labels the observation September 2026. These are city-level closed-sale and market indicators, not an as-is cash valuation or a promise of time from first contact to funded closing.
If your house is ready for broad retail exposure, a listing deserves consideration. If a basement problem or unfinished rehabilitation makes that route less practical, compare a written current-condition offer with your likely repair budget and net proceeds.
Sell It Exactly as It Sits in Hammond
We buy houses in Hammond, IN, without requiring a renovation first. Our direct-purchase policy lets you skip the preparation below. Tell us about known defects, access needs and anything you want to leave behind so the written agreement reflects the property.
- Don’t paint.Skip interior touch-ups and exterior repainting.
- Don’t replace flooring.Leave stained carpets, worn hardwoods or cracked tile.
- Don’t fix the roof.We buy with active leaks, missing shingles or aged roofs.
- Don’t stage the home.Avoid professional staging and decluttering costs.
- Don’t clean it out.Take what you want; leave unwanted furniture, trash and clutter as agreed in writing.
- Don’t schedule dozens of showings.Skip open houses and lockboxes; coordinate the access needed for our property review.
For Hammond’s older homes, selling as-is still requires attention to applicable disclosures. The City documents 1920s–1930s Robertsdale bungalows; for most pre-1978 sales, EPA’s lead-disclosure rules require known lead information, available records, the lead pamphlet and a buyer inspection opportunity, subject to exceptions and permitted timing changes. An as-is price does not replace that paperwork.
Learn more in our as-is selling guide. A condition review may still be needed; inspection, cancellation and price-adjustment rights should be clear in the contract.
Selling a House in Hammond’s Neighborhoods
A full-basement bungalow and a house with a specialty historic roof can call for different repair scopes. The records below identify documented housing characteristics; they do not establish present defects or how frequently neighbors choose an off-market sale. Seller scenarios are illustrative options.
On smaller screens, scroll the table sideways.
| Neighborhood / District | Housing Profile | Common Challenges We Resolve | Seller Scenario |
|---|---|---|---|
| Robertsdale | The City documents many Chicago bungalows built in the 1920s–1930s, with full basements; Water Gardens is a smaller residential area built in 1926–1927. | Ask about basement condition and any sewer-backup history; no neighborhood defect frequency is established. | Illustrative option: compare the bungalow’s rehabilitation scope with a current-condition offer. |
| Forest-Ivanhoe Residential Historic District | National Register district with a 1925–1952 period of significance; Tudor Revival, English Cottage and Colonial Revival homes, with brick, limestone, stucco and wood exterior materials. | Assess the actual masonry, stucco and roof condition; historic documentation does not establish current defects. | Illustrative option: compare preservation or rehabilitation costs with an as-is sale. |
| Forest-Southview Residential Historic District | Contributing homes date to 1912–1949; Colonial Revival, Tudor/English Cottage and other revival homes, with some American Four-Square and Craftsman examples. Later ranch/contemporary homes were also inventoried. | Review actual wood-window, masonry and slate/clay-tile roof condition where present; no district-wide defect rate is established. | Illustrative option: weigh a restoration project against selling before repairs. |
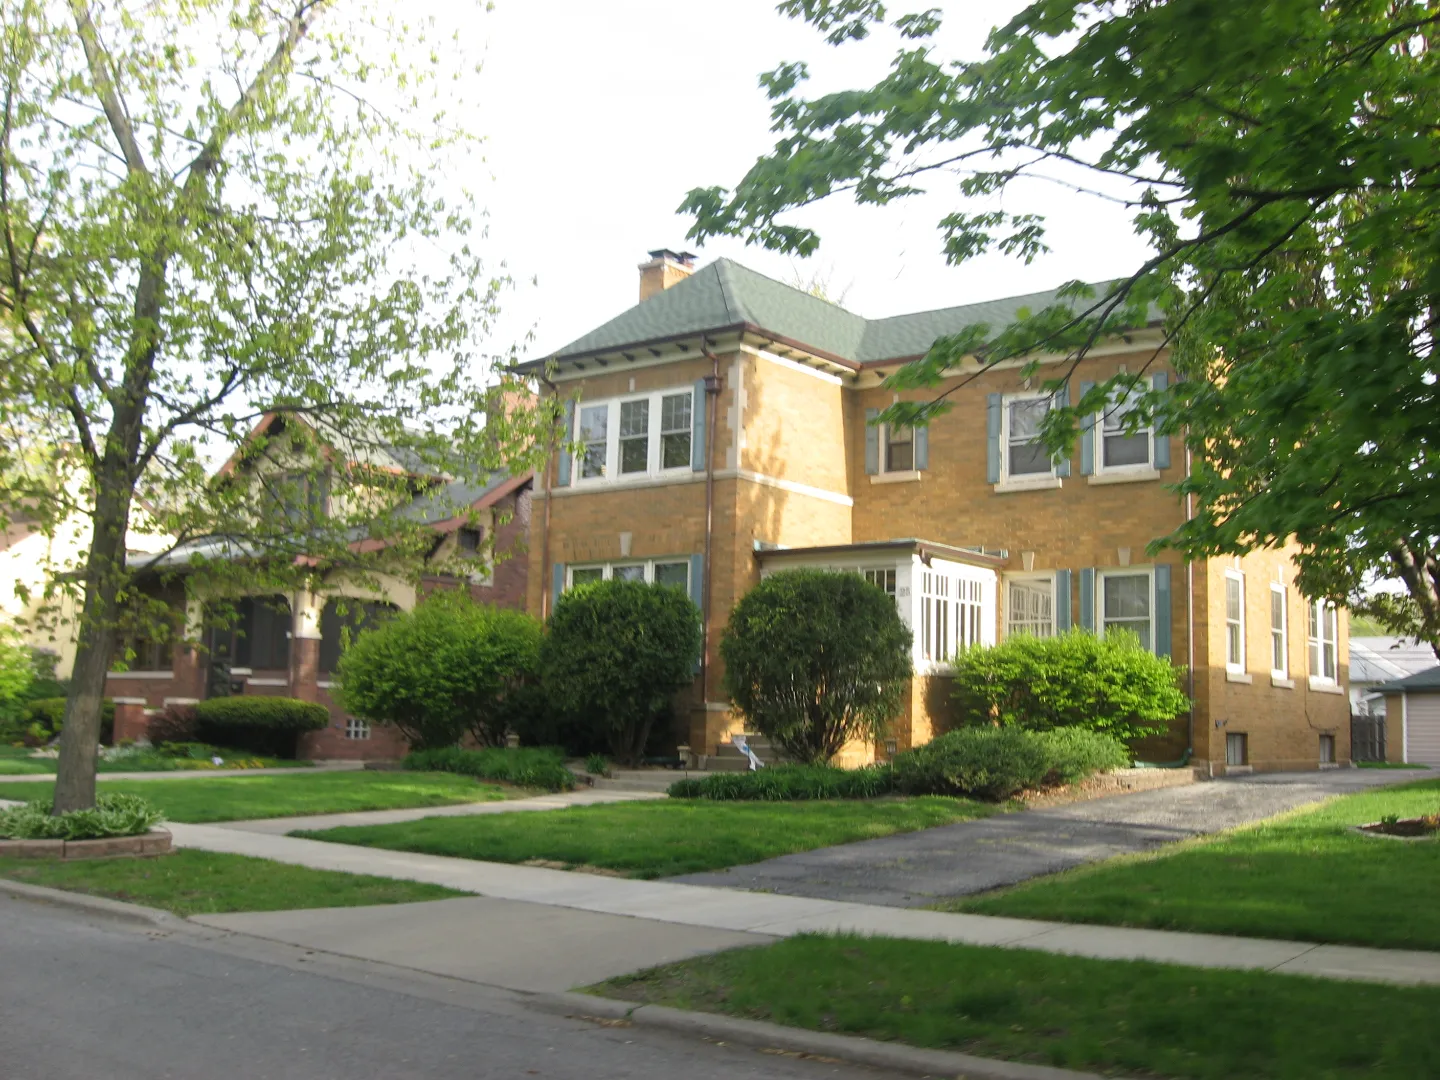
The City’s residential-style guide also documents brick bungalows, Prairie examples with brick, stucco or wood exteriors, and prefabricated enameled-steel Lustron homes. It describes low-pitched bungalow/Prairie roofs, steeper Cape Cod/Tudor forms and generally slab-built Lustrons, with exceptions. Appearance alone does not establish load-bearing construction, and these examples do not establish a citywide median construction year or dominant foundation or roof material. Identify your actual building before comparing contractor scopes.
Basement Backups, Older Paint and the Work Behind a Repair Budget
Private sewer laterals and basement backups
The Hammond Sanitary District’s Flood Proofing Guide explains that roots, grease or broken lateral segments can restrict drainage, while excess inflow or a surcharged main can push sewage into basement drains or toilets. Owners maintain the lateral to the main, including the part under public right-of-way.
Water rising through a floor drain is a useful history to share, not a diagnosis of the exact cause. As a planning inference, an unresolved lateral scope can increase a buyer’s repair allowance or prompt requests for inspection and credits. Compare a qualified assessment with an offer that accounts for the condition. This is a regional tendency, without a verified neighborhood concentration or era cutoff.
Lead-paint questions in pre-1978 houses
In homes that contain lead-based paint, deterioration can create hazardous chips and dust; friction or impact on painted surfaces can also produce dust. Peeling, chipping, chalking or cracking is a warning sign, but EPA explains why appearance alone cannot identify lead.
This is an age-specific concern for older Hammond stock, not evidence that every house contains lead or that Hammond has an unusually high citywide rate. Share existing reports and known information. A buyer may account for evaluation or specialist work in the repair scope; a defect does not automatically cause financing to fail.
Check flood mapping separately from sewer-backup history
Use the address in Indiana DNR’s Floodplain Information Portal, including the effective FEMA layer and DNR Best Available Floodplain mapping. The portal can produce a Floodplain Analysis and Regulatory Assessment. A neighborhood name does not establish a parcel’s flood determination.
Separately, EPA’s January 2026 Grand Calumet cleanup announcement concerns contaminated sediment in the Area of Concern, including Hammond’s Lake George Canal corridor. That waterway work does not establish contamination at a residential parcel. Use the property’s own site history when a buyer or professional raises a specific concern.
Verify permits, code notices and utility reconnect requirements
Hammond’s published inspections FAQ says permits are required for work valued at $500 or more, including remodeling, siding, roofing and rehabilitation; fences, decks and porches need zoning approval and a permit regardless of value. Contact Inspections about electrical and plumbing work. Before starting sale preparation, ask what your particular project requires.
The Building Division handles permits, construction/remodeling inspections and contractor registration at City Hall, Room G1, 5925 Calumet Avenue, Hammond, IN 46320; call 219-853-6317. Code Enforcement, at the same room and address, handles housing, rental-registration, nuisance and property-maintenance ordinances; call 219-853-6447. Bring actual notices and permit records into the sale discussion instead of assuming an offer resolves them.
The City FAQ lists $50 for a gas reconnect inspection and/or $50 for an electric reconnect inspection. A recent purchaser provides ownership proof and identification; a tenant provides a signed lease and identification. This specific reconnect process is not evidence of a universal point-of-sale inspection. NIPSCO documents electric-system projects serving Hammond customers; confirm service and reconnect steps for the address. Do not treat an ordinary electric bill as a recorded property lien without a verified legal basis.
For a vacant house, check insurance before choosing a renovation timeline
The Indiana FAIR Plan’s consumer rules describe possible eligibility after denials from at least three insurers, limited coverage valued on an actual-cash-value basis, and an inspection of the interior, exterior and basement. Vacant or unoccupied properties are generally ineligible unless actively renovated by a licensed contractor with completion and occupancy within 90 days. Inability to complete the inspection can lead to declined or limited coverage.
These are FAIR Plan terms, not every insurer’s rules. Ask your insurer about your actual coverage while comparing a repair-and-list schedule with a direct sale; obtain the carrier’s decision rather than assuming a universal roof-age cutoff or mandatory four-point inspection.
The City’s PY2026 draft action plan reports that higher housing prices and mortgage rates hindered its Homebound assistance program, and describes emergency/minor repair, basement backflow prevention and disability-ramp assistance. That supports comparing assistance or keeping the property alongside selling; it does not establish seller-motivation rates or guarantee current program eligibility. Ask the City about present availability before committing to work.
AS-IS Repair Cost Estimator
Explore a broad interior-renovation allowance before deciding whether to repair or request an as-is offer. For a Hammond basement backup, potential lead work or specialty slate/clay-tile roof, obtain a separate specialist scope rather than assuming a general square-foot allowance covers it.
Interior allowance $37,500–$90,000 + separate allowance $0, with 15% contingency.
Assumptions: The three square-foot ranges and default 15% contingency are illustrative editorial presets, not measured Hammond contractor prices. Formula: (renovation area × selected low/high rate + separate allowance) × (1 + contingency). Presets do not automatically include sewer laterals, lead abatement, specialty roofs, structural work, major environmental work, permits or engineering. Add those separately without double-counting quoted work. Severe or concealed damage can exceed the displayed range.
This is a broad planning estimate, not an inspection, appraisal, contractor quote, cash offer or guarantee. Actual costs vary substantially with scope, materials, labor, permitting, access and concealed damage. Calculator entries stay in this page and are not sent as a lead submission.
Cash Sale vs. Traditional Listing in Hammond
A traditional sale may produce a higher gross price, but commissions, seller closing costs, repairs, concessions and ongoing holding expenses reduce the amount you ultimately keep. A direct cash sale generally prioritizes speed, certainty and convenience rather than the highest possible gross price.
As cash home buyers in Hammond, Indiana, we evaluate current condition rather than using the citywide median as your offer. The market snapshot’s 20 days on market does not include every step to payment. When comparing cash buyers for houses in Hammond, IN, request the written purchase price, closing-cost allocation, review rights and expected payoffs.
| Dimension | Traditional listing | Direct cash sale |
|---|---|---|
| Gross Price | Potentially higher gross price | Usually lower than full retail value |
| Commissions | Agent commission may apply | No agent commission |
| Closing Costs | Seller closing costs may apply | MHIC pays normal closing costs |
| Property Condition | Repairs or buyer credits may be requested | Property sold as-is |
| Contingencies | Financing and appraisal contingencies | No buyer-financing contingency |
| Timeline | Longer and less predictable timeline | Seller selects an available closing date |
Compare Your Estimated Selling Options
Use our adjustable calculator to compare a traditional listing with a direct cash sale using your property’s estimated value and expenses.
Use the Net-Proceeds Calculator →Normal closing costs do not erase your mortgage payoff, back taxes, recorded obligations or negotiated exceptions. Listing terms vary; the table describes a typical financed-buyer route rather than every possible listing contract. Review the actual settlement estimate and purchase agreement.
Probate, Foreclosure Deadlines, and Complicated Title Situations in Hammond
A cash offer is one possible sale option, not a court or title solution by itself. An authorized owner or fiduciary needs enough time to complete the transaction and satisfy the applicable closing requirements before a scheduled foreclosure sale. Share notices and authority documents early; consult an Indiana real estate attorney about deadlines and legal rights.
Inherited property: the personal-property affidavit is different from a real-estate transfer
Indiana’s Dispensing With Administration provisions, IC 29-1-8, distinguish the section 8-1 small-estate affidavit from sections 8-3/-4 summary administration. The ordinary small-estate affidavit collects personal property, not a house or land. Being below a dollar threshold does not automatically authorize someone to sell estate real estate.
- Section 8-1 affidavit: For deaths after June 30, 2022, the gross probate estate wherever located, less liens, encumbrances and reasonable funeral expenses, must not exceed $100,000. Earlier death-date tiers differ. Wait at least 45 days after death. See the Coalition for Court Access affidavit.
- Section 8-3 summary route: For those death dates, gross probate estate less liens and encumbrances cannot exceed $100,000 plus administration costs and reasonable funeral expenses. Qualifying real estate can pass through a county-recorded affidavit identifying the property and distributees’ interests; a personal representative of an unsupervised estate or another court-appointed fiduciary is required. This section does not prescribe the separate 45-day wait applicable to section 8-1.
- Authority and exclusions: Section 8-1 is unavailable if appointment of a personal representative is pending or granted anywhere, or the estate exceeds the applicable ceiling. Identify and notify all distributees; the affiant must be entitled to receive for them. Distribution does not extinguish superior rights.
The Indiana Judicial Branch’s case-type guide distinguishes an affidavit ordinarily presented to the holder, with optional court enforcement, from summary administration involving a court-appointed fiduciary and a closing statement. A section 8-1 signer may be a distributee or someone acting on one’s behalf; that alone is not section 8-3 real-estate authority.
For a court estate proceeding, Indiana’s probate-venue guidance points to the decedent’s Indiana county of domicile, or an Indiana county holding a nonresident’s estate property. Lake County publishes Lake Circuit Court — Probate Division as Circuit Court Probate, at 2293 N. Main Street, Courtroom B203, Crown Point, IN 46307. Ask the clerk about procedures and your attorney about authority, required filings and whether a proposed sale needs court action. We do not promise probate approval.
Mortgage foreclosure: separate the lawsuit, response deadlines and sale date
Indiana mortgage foreclosure is judicial: a complaint, court judgment and sheriff’s sale. The IHCDA mortgage-foreclosure summons accompanies the complaint. A lis pendens is a separate litigation notice in the county Clerk’s lis pendens record, not the instrument that substitutes for filing the lawsuit.
- Before filing: For covered residential mortgages, the IHCDA prescribed presuit notice is sent by certified mail at least 30 days before filing, subject to statutory exceptions. IHCDA’s notice instructions describe the notice process.
- Federal protection is separate: When Regulation X, 12 CFR 1024.41(f) and (g), applies, the first foreclosure filing generally cannot occur until the loan is more than 120 days delinquent. Exceptions include due-on-sale violations and joining another lienholder’s foreclosure. Applicable loss-mitigation protections may further delay filing or sale.
- After receiving the summons: The published IHCDA form gives 20 days to answer, or 23 when received by certified mail. A settlement-conference request is separate and due within 30 days of receipt; eligibility and exceptions depend on the statute. Ask counsel which deadline applies to your case.
- Post-complaint waiting rules: Under IC 32-29-7-3, execution process ordinarily cannot issue until three months after the complaint; the period is six months for mortgages executed January 1, 1958–June 30, 1975, and twelve months for earlier mortgages. Court-found abandonment has an accelerated exception. These are legal timing rules, not a measured local completion range.
- Sale notice: IC 32-29-7-3(e) calls for advertising weekly for three successive weeks, with first publication at least 30 days before sale, and service on each owner when placing the first advertisement; prescribed newspaper/website alternatives are permitted. The Sheriff’s posted information sheet specifies the Gary Crusader on three consecutive Thursdays, with advertising beginning 30 days before sale.
The state-prescribed notice describes preventing the sheriff’s sale by paying the judgment under IC 32-29-7-7. Full-judgment redemption is not the same as an unrestricted right to reinstate by paying arrears. Ask your attorney and servicer whether a conditional reinstatement or another resolution is available for the actual loan; no general installment-reinstatement promise is made here.
Under IC 32-29-7-7 and -13, an ordinary borrower has no post-sale redemption period after a completed mortgage-foreclosure sheriff’s sale. Property-tax-sale redemption is a separate process.
The Sheriff’s posted venue is the auditorium of Building B, the Courts building, 2293 North Main Street, Crown Point, IN 46307. Its posted schedule is the first Friday monthly at 10 a.m. or shortly thereafter, moving to the following Friday for a holiday. Confirm the property-specific notice and cancellation status through the Civil Division. A reliable Hammond/Lake County measured default-to-sale range was not established in the research; do not use a five-day purchase example as a foreclosure deadline.
Back taxes and recorded claims: obtain the actual payoff
The Lake County Treasurer, published as John Petalas, collects property taxes. The Hammond office is 232 Russell St, Hammond, IN 46320; 219-933-2900. The main office is 2293 N Main Street, Building A, second floor, Crown Point, IN 46307; 219-755-3760.
DLGF’s 2026 installment dates are May 11 and November 10, 2026; the following days are May 12 and November 11. The initial penalty is 5% of unpaid tax if paid within 30 days after the due date and no earlier installment remains delinquent on that parcel; otherwise it is 10%. Missing that condition raises the initial penalty to 10%, not 5% plus another 10%.
For taxes payable in two equal installments, IC 6-1.1-37-10 as described by DLGF adds another 10% of taxes still unpaid on the day after each first and second installment due date in every year after initial delinquency. These are statutory penalties, not a quoted monthly interest rate. Unpaid tax can lead to a tax sale, whose redemption amounts follow separate rules; ordinary penalties are not the full tax-sale redemption payoff.
Ask the title professional to verify mortgages, releases, recorded claims and any estate authority questions. Bring actual code notices and any municipal lien documents; the title review determines what affects this parcel and what documentation or payment is needed. A proposed payoff does not guarantee lien removal, tax forgiveness or clear title. You can also review our guide to selling with liens or taxes.
My House Into Cash provides a direct-purchase option, not legal, tax, probate, financial or foreclosure-defense advice. Consult the court clerk, Lake County Treasurer, your attorney or a qualified tax professional about your circumstances. An offer does not establish legal authority, change a court deadline or guarantee title clearance.
What Happens Between Accepting Your Cash Offer and Getting Paid in Hammond?
To sell a house fast in Hammond, Indiana, start title work early. Indiana’s Notary Public Guide describes title-company closings as prevailing practice: companies examine title, typically arrange documents, and use attorneys or licensed notary/title agents for closing. That is a description of practice, not a requirement that every seller hire an attorney.
-
Day 0 · Finalize the purchase agreement
Agree on price, property condition, access, items left behind, possession and an available closing date. In an MHIC direct purchase, there are no agent commissions or MHIC service fees, and MHIC pays normal closing costs. Existing seller debts and negotiated exceptions still affect your net. A Hammond-wide rule about who pays each title-insurance premium was not verified; use the signed contract and settlement quote.
-
Days 1–2 · Examine title and the relevant records
The selected title company checks ownership and recorded obligations. A locally operating example, Stewart Title–Greater Indiana Title Company, describes searching deeds, mortgages, assessments, liens, wills and divorce records, then issuing a title commitment. Its stated workflow includes tax information, loan payoffs, any needed survey and applicable association fees. This is that company’s workflow, not a universal municipal-certificate requirement.
The Lake County Recorder maintains deeds, mortgages, liens, releases and plats and links to lcrecorder.com for viewing/purchase. Its holdings generally exclude court orders, judgments and wills, so relevant court records need separate review. Use the Treasurer’s Tax Search and Payment service for parcel balances and bring known code or permit notices to the closing professional.
Stewart Title–Greater Indiana lists an appointment-only Hammond office at 2901 Carlson Drive, Suite 324, Hammond, IN 46323; 219-641-6300. This verifies a local candidate, not an established MHIC partnership or independent reputation rating. The actual closing company must be agreed for the transaction.
-
Days 2–4 · Confirm payoffs and satisfy title requirements
The closing professional obtains the relevant mortgage and tax figures and identifies releases, fiduciary documents or other recorded-claim requirements. Use Lake County’s actual tax record and payoff instructions rather than a flat assumed tax proration. An unresolved heirship issue, lien dispute or needed court action can extend this example substantially. Signing a purchase agreement does not clear those matters.
-
Day 5, if ready · Sign, record and receive released proceeds
Indiana recognizes a statutory warranty conveyance under IC 32-17-1-2, but that form is not mandatory for every transfer. The deed follows the contract and seller’s legal capacity. Under IC 32-21-1-13, the conveyance must be written, signed by the grantor and acknowledged or proved as the statute permits; an ordinary acknowledged deed does not add a general separate-subscribing-witness requirement.
Recording guidance requires the appropriate acknowledgment/proof certificate, legible and consistent signature names subject to exceptions, and the county auditor’s endorsement that the land is entered for taxation or not taxable. The Lake County Recorder, published as Gina Pimentel, records Hammond deeds at Building A, second floor, 2293 N Main Street, Crown Point, IN 46307; 219-755-3730. Its e-recording service accepts approved business submitters, including title companies, law firms and banks; a seller need not assume a separate Recorder’s-office visit.
Indiana’s Good Funds guidance requires qualifying money in escrow before disbursement: incoming amounts of at least $10,000 from a single party must be wired, and electronic funds must be unconditionally held and irrevocably credited. This incoming-money rule does not require every seller’s proceeds to be paid by wire. Confirm the closing agent’s wire/check options and release timing; a signed deed or incoming transfer instruction alone does not establish available proceeds.
What should I expect at the signing appointment?
The local title company’s seller checklist calls for photo/signature identification and keys or garage openers. This documents an in-person option, not a requirement that buyer and seller attend together. Ask the actual agent which documents, identification and arrangements apply to your sale.
The Secretary of State’s guide says a traditional paper notarization does not require a notary journal. Remote notarization requires an electronic journal and prohibits biometric identifiers, including fingerprints, in that journal. No paper-deed thumbprint mandate was verified; use the closing professional’s actual signing instructions.
Explore Hammond and Nearby Communities on Google Maps
Use the map to explore Hammond, Indiana, and nearby communities. Zoom and pan to view the area, then check the community list and ZIP guide below. Contact us to confirm purchase availability for your property.
Nearby communities to ask us about
- Whiting, IN
- East Chicago, IN
- Munster, IN
- Highland, IN
- Griffith, IN
- Schererville, IN
- Dyer, IN
- St. John, IN
- Merrillville, IN
- Crown Point, IN
- Gary, IN
- Hobart, IN
- Portage, IN
- Chesterton, IN
- Valparaiso, IN
- Cedar Lake, IN
- Lowell, IN
- Lake Station, IN
- Hebron, IN
- Kouts, IN
- Calumet City, IL
- Lansing, IL
- South Holland, IL
Indiana and Illinois are different jurisdictions. For an Illinois property, confirm that state’s process with the closing professional; the legal and tax guidance on this page concerns Hammond, Indiana. Explore our Indiana service page for the broader statewide overview.
Hammond Real Estate & Legal Terms Homeowners Should Know
- Sales Disclosure Form (State Form 46021)
- Use the county assessor’s submission instructions for Indiana’s transfer-data form. State Form 46021 supplies conveyance information to assessing officials; it is a different document from the seller’s property-condition disclosure. Source and details.
- Duly entered for taxation
- This county auditor endorsement is needed before recording a deed. It confirms entry in the taxation records, not clear title, so keep the title examination separate. Source and details.
- Good Funds
- Qualifying money must be in the settlement escrow before it is disbursed. The $10,000 threshold concerns incoming funds from each party, not the amount or required payment method of your seller proceeds. Source and details.
- Taxing district
- The combined local taxing units serving an area determine the taxing district. Check the Hammond parcel record and actual bill instead of applying one assumed city tax rate. Source and details.
- E-Recording
- Approved business submitters, including title companies, law firms and banks, can submit land documents electronically to the Lake County Recorder. Ask the closing agent how the deed will be submitted rather than assuming a personal trip to the office. Source and details.
Hammond Cash Home Sale FAQs
Which residential ZIP codes are included in Hammond and the surrounding area?
Hammond’s standard street-delivery ZIPs are 46320, 46323, 46324 and 46327; Robertsdale addresses also use 46394, the Whiting postal ZIP. The table covers all 25 standard-delivery ZIPs listed for Lake County, plus six Porter County ZIPs and three Illinois ZIPs for the named nearby communities: 34 distinct standard-delivery ZIPs. Mailing-city names and municipal boundaries differ.
| City / postal community | Residential street-delivery ZIP codes |
|---|---|
| Hammond, IN (including Robertsdale) | 46320, 46323, 46324, 46327, 46394 |
| Whiting, IN | 46394 |
| East Chicago, IN | 46312 |
| Munster, IN | 46321 |
| Highland, IN | 46322 |
| Griffith, IN | 46319 |
| Schererville, IN | 46375 |
| Dyer, IN | 46311 |
| St. John, IN | 46373 |
| Merrillville, IN | 46410 |
| Crown Point, IN | 46307 |
| Gary, IN | 46402, 46403, 46404, 46406, 46407, 46408, 46409 |
| Hobart, IN | 46342 |
| Portage, IN | 46368 |
| Chesterton, IN | 46304 |
| Valparaiso, IN | 46383, 46385 |
| Cedar Lake, IN | 46303 |
| Lowell, IN | 46356 |
| Lake Station, IN | 46405 |
| Hebron, IN | 46341 |
| Kouts, IN | 46347 |
| Calumet City, IL | 60409 |
| Lansing, IL | 60438 |
| South Holland, IL | 60473 |
PO Box-only codes, including Hammond 46325, Crown Point 46308, Gary 46401, Merrillville 46411 and Valparaiso 46384, are excluded from the residential street-delivery list. If you use a PO Box, give us the property’s street address.
ZIP-type cross-checks: Lake County, Porter County, Calumet City, Lansing and South Holland. Hammond’s Council minutes also discuss residents in 46394. Verify the exact address with the USPS ZIP Code lookup. This is a complete standard-delivery list for the Lake County and named nearby postal areas above, not every ZIP in the surrounding region, and it does not guarantee operational coverage.
How do I sell my house for cash in Hammond?
Call (866) 651-6617 or use our normal cash-offer form with the property address. We review the known condition and explain a written offer. If you accept, the selected closing professional verifies ownership, payoffs and title requirements before an available closing date is confirmed. A direct sale is one option to compare with listing or keeping the property.
Can I sell my Hammond house as-is with basement water or unfinished repairs?
Yes, MHIC can evaluate the house in its present condition. Share known sewer-backup history, reports, permits and notices. Hammond Sanitary District identifies private-lateral restrictions and surcharged mains as possible basement-backup mechanisms; the actual property needs its own assessment. As-is terms do not replace applicable disclosure obligations. Hammond Sanitary District guide.
Can a Hammond cash sale close in five days?
A straightforward MHIC purchase may close in as little as five days when authority to sell, title requirements, payoffs and good funds are ready. Five days is a possible transaction example, not a promise of immediate payout or a substitute for probate or foreclosure deadlines. The closing professional confirms release timing and payment options. Indiana Good Funds guidance.
Does Indiana’s $100,000 small-estate affidavit let me sell an inherited Hammond house?
Not by itself. IC 29-1-8-1 concerns personal property, not a house or land. A separate section 8-3 real-estate route has its own estate-value test, recorded-affidavit requirements and qualified-fiduciary requirement. Ask an Indiana attorney to establish who can sign and what court or recording steps apply before accepting a sale contract. Indiana small-estate provisions.
Will a cash offer stop a Hammond foreclosure?
An offer alone is not foreclosure-defense relief. A completed sale may be an option if an authorized seller has enough time before the scheduled sheriff’s sale and can meet the closing and payoff requirements. Indiana uses judicial mortgage foreclosure, and an ordinary borrower has no redemption period after the completed mortgage-foreclosure sale. Consult your attorney and servicer about the actual notices, rights and deadlines. Indiana mortgage-foreclosure provisions.
Will I receive the full cash-offer price?
Your net proceeds depend on the written agreement and settlement statement. MHIC charges no agent commission and pays normal closing costs, but mortgages, taxes, recorded obligations and negotiated exceptions can reduce what you receive. Use the Lake County parcel tax record and current payoff figures rather than assuming that an as-is sale removes debts. Lake County tax search.
Is Hammond’s 20-day market time the same as a 20-day closing?
No. The supplied Redfin snapshot for all home types in the three months ending September 2026 reports 20 median days on market, a $199,905 median sale price, a −0.048% year-over-year price change and an 81/100 Very Competitive score. Those are city-level market indicators, not an individual home valuation or elapsed time from first contact to released sale proceeds. Redfin Hammond city report.
Compare a Written Cash Offer for Your Hammond House
Start with the address and the condition you know today. Bring a sewer report, tax notice or estate document if you already have one; the first conversation can begin before you assemble a complete file.
Our published business number is toll-free; it is not presented as a Hammond-local office number.
Official Hammond Homeowner Resources
- Lake Circuit Court — Probate contact
- Lake County Assessor — official parcel-record access
- Lake County Treasurer — property taxes
- City of Hammond — Building Division
- City of Hammond — Code Enforcement Division
- Indiana DNR — Indiana Floodplain Information Portal (FEMA and DNR mapping)
- Indiana Code 2026 — IC 29-1-8, Dispensing With Administration
- Indiana Code 2026 — IC 32-29-7, Mortgage Foreclosure and Redemption
- Lake County Sheriff — Civil Division and sheriff-sale information
- NIPSCO — verified Hammond electric-service projects
Use these offices and records for property-specific answers. Market figures are the supplied October 15, 2026 research snapshot; legal and tax details refer to the linked materials and stated 2026 dates. Confirm current requirements, actual balances, court deadlines and service availability with the responsible office or qualified professional.