
Tampa Market Watch: Price Growth Does Not Mean a Quick Sale
The supplied Tampa housing-market report covers the three months ending August 2026 and was retrieved October 7, 2026. It describes the market as somewhat competitive, with a Compete Score of 46 out of 100. The report also records a 96.9% sale-to-list ratio and price drops on 42% of listings. Those measures describe different aspects of the market; a reduced asking price is not the same as a falling citywide median sale price.
For Tampa homeowners, the practical choice is between pursuing a retail price with room for marketing and negotiations, or comparing that plan with an as-is cash offer. The 46-day figure is a marketing measure, not a guaranteed contract-to-payment timeline. A median also cannot establish your home's fair market value.
Want to sell a house fast in Tampa? Compare recent, similar sales and your expected holding expenses. A house that needs roof documentation or flood-related work can have a different selling path from a move-in-ready home.
Sell It Exactly as It Sits in Tampa
We buy houses in Tampa in their current condition. You can sell your house as is without preparing it for retail buyers; our purchase proposal accounts for the work instead. This is MHIC’s buying policy, not a promise that every cash buyer follows the same terms.
Skip interior touch-ups and exterior repainting.
Leave stained carpets, worn hardwoods, or cracked tile.
We buy houses with active leaks, missing shingles, or aged roofs.
Avoid professional staging and decluttering costs.
Take what you want; leave unwanted furniture, trash, and clutter behind as agreed in the contract.
Skip open houses, lockboxes, and disruptive walk-throughs. We coordinate the access needed to evaluate the property.
Before spending on exterior work in a designated historic district, check Tampa’s historic-preservation approval requirements. A direct offer gives you another option if compatible repairs would take more time or money than you want to commit.
Request a No Obligation Cash Offer →Selling a House in Tampa’s Neighborhoods
Tampa’s historic districts call for more than a cosmetic checklist. The housing profiles below come from municipal design guidance and the National Park Service. They help identify what to inspect before budgeting a sale; they do not establish defect rates or neighborhood seller motives.
| Neighborhood / District | Housing Profile | Common Challenges We Resolve | Seller Scenario |
|---|---|---|---|
| Seminole Heights | Early 1910s–1920s bungalow and Florida Vernacular stock; wood-frame houses, porches, gabled roofs and brick piers are documented district features. | Inspection focus: original exterior wood and porch deterioration, foundation-enclosure condition, and preservation approval for exterior changes. Defect frequency is not quantified. We evaluate the work in an as-is purchase proposal. | Compare a cash offer with a repair-and-list plan for your own property. |
| Tampa Heights | Historic residential development from the late 1870s through the mid-1920s, with varied historic styles, porches and gabled or hipped roofs. | Inspection focus: deteriorated historic porch details and exterior wood, roof repair scope and compatible replacement materials. Defect frequency is not quantified. We evaluate the work in an as-is purchase proposal. | Compare a cash offer with a repair-and-list plan for your own property. |
| Ybor City | Cigar-worker residential stock associated with the 1886–World War I district; documented residences are typically wood-frame and gable-roofed. | Inspection focus: condition of older wood framing and gabled roof structures. We evaluate the work in an as-is purchase proposal. | Compare a cash offer with a repair-and-list plan for your own property. |
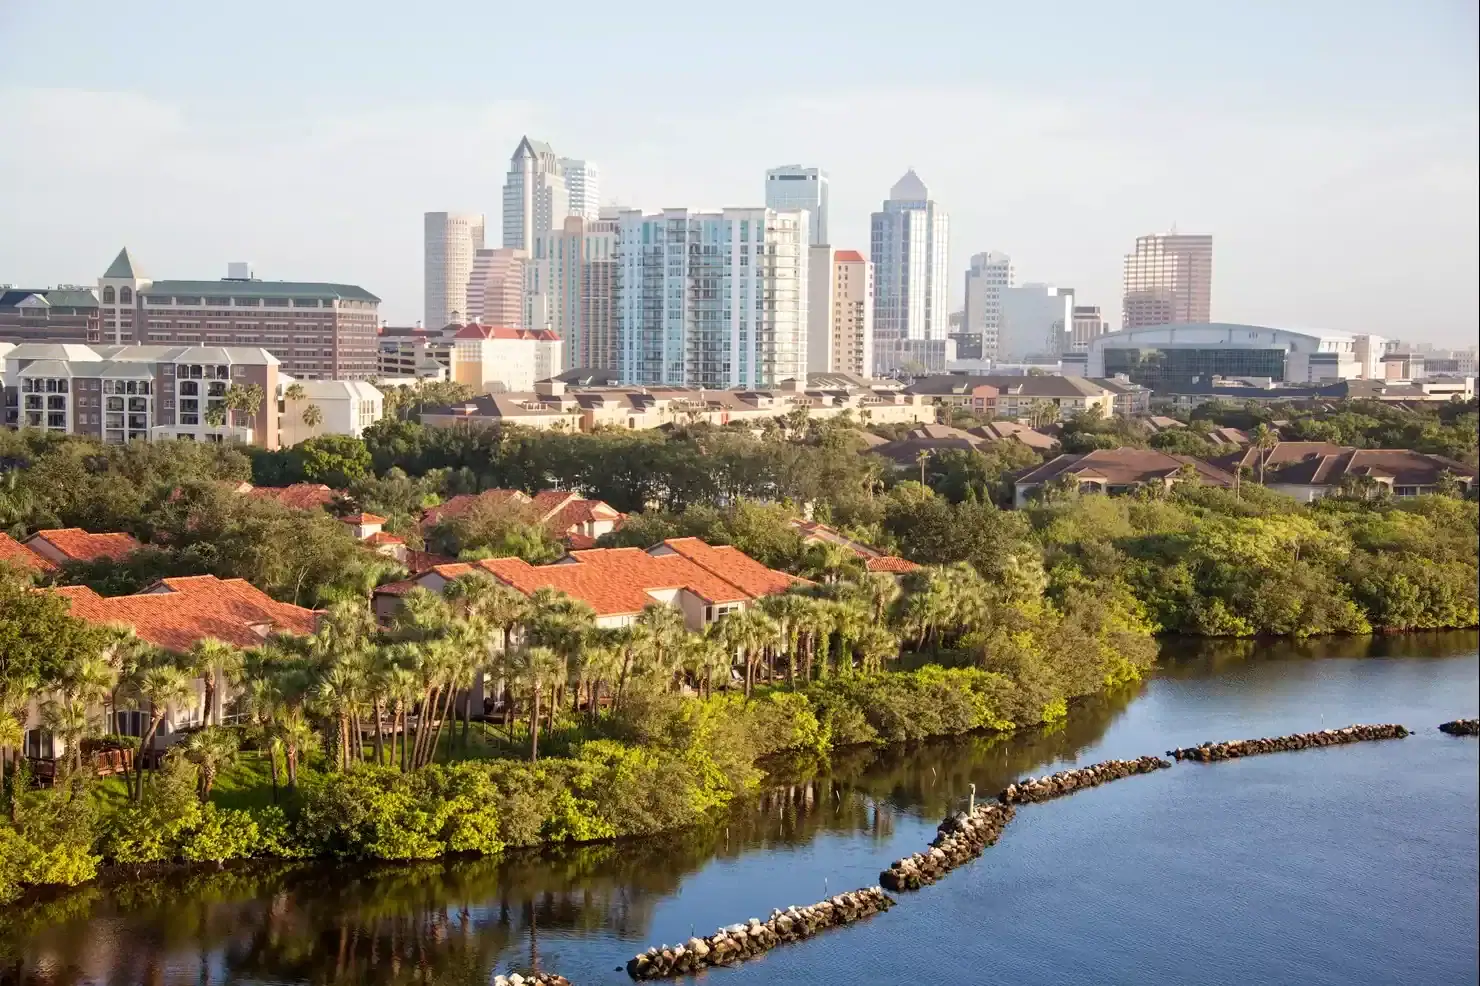
For a Seminole Heights bungalow with raised pier construction, assess the actual wood and foundation-enclosure condition. In Tampa Heights, historic roof forms and compatible replacement materials can change the scope of a repair plan. Ybor City’s documented wood-frame residences make the condition of individual framing members relevant. None of these profiles proves that a particular house has damage.
A useful next step is to gather inspection reports, repair photographs, and available permit records before comparing offers. We buy houses as is, so the discussion can focus on price, access, and the work a buyer will assume.
Tampa Property Conditions That Can Change Your Selling Plan
Floodwater and concealed moisture
Tampa documents localized flooding, limited drainage relief, and tidal influence. Exposure varies by parcel; this is not a claim that every Tampa home floods. Use the FEMA Flood Map Service Center for the specific address.
The EPA’s flood-cleanup guidance explains that water can wet drywall, wood, flooring, and concealed cavities. Persistent dampness, visible mold, and previously flooded surfaces warrant assessment even when the outer surface looks dry. A practical sale implication is that an inspection may expand the repair allowance; it does not automatically mean a buyer or lender will reject the house.
In affected flood-hazard areas, Tampa’s substantial-damage and improvement guidance can change rebuilding requirements. Ask the City for the applicable determination before planning major repairs.
Wind damage and a leaking roof
On asphalt-shingle roofs, high wind can lift or remove shingles and expose joints or penetrations that admit water into the roof deck and interior. DOE / PNNL roof guidance identifies this mechanism; it does not establish a Tampa failure rate.
Missing shingles or attic and ceiling stains justify a roof assessment. Roof damage and documented remaining life can affect Citizens insurance eligibility, so roof records may matter to a financed buyer’s timetable. Florida’s roof-age underwriting protections are separate; age alone is not the same as a damaged roof.
We can evaluate a cash offer with the roof in its current state. Compare that proposal with a written repair scope before committing to costly repairs solely to list.
Termites in structural wood
UF/IFAS documented Asian subterranean termite establishment in South Tampa in March 2023. That is evidence of local occurrence, not citywide prevalence.
Subterranean termites can hollow wood while leaving a thin outer surface. UF/IFAS inspection guidance identifies mud tubes, swarm evidence, shed wings, and damaged wood as reasons to seek identification and inspection. Structural wood matters in any construction era, including floor and roof members.
Treatment and structural repair are separate questions. Check species exclusions in any treatment contract. In our assessment, documented repair findings can change negotiations; this is a practical inference, not a measured Tampa financing-denial rate.
Insurance checks and older systems
Citizens requires a four-point inspection for relevant homeowner, dwelling, and mobile-home applications when the structure is more than 20 years old. This is its eligibility rule, not a universal Florida mandate.
Its four-point form examines roof, electrical, plumbing, and HVAC condition. It flags unsafe wiring, double taps, improper grounding, and active leaks. It records cloth or knob-and-tube wiring, single-strand aluminum branch wiring, and galvanized, cast iron, or polybutylene piping. A listed material does not, by itself, establish universal rejection.
Ask the buyer and insurance agent what documentation or corrections their transaction requires. A cash purchase removes the buyer’s mortgage approval contingency; it does not erase condition, title, or insurance questions.
Flood zones and evacuation zones serve different purposes. Tampa’s hurricane guidance distinguishes flood and building/insurance risk from emergency storm-surge evacuation exposure. Check both before using a map to plan repairs or a sale.
Dated insurance notice: October 7, 2026
Citizens’ October 7 bulletin announced a statewide suspension of new-policy binding and changes increasing coverage at 11:05 a.m. Eastern because of Tropical Storm Isaias. This is a historical, dated notice. Have the insurance agent check the current binding alert before relying on coverage availability; the bulletin does not establish that a suspension remains in force on your closing day.
AS-IS Repair Cost Estimator
This calculator provides a broad planning estimate, not an inspection, appraisal, contractor quote, or guarantee. The dollar ranges below are adjustable planning assumptions created for this tool, not verified Tampa contractor prices. Actual repair costs can vary substantially with scope, materials, labor, permitting, access, and concealed damage.
Tampa’s floodplain determinations and historic-preservation requirements can change the work itself. The tool therefore excludes elevation, substantial-damage compliance, and historic restoration from its allowances. Check the relevant City flood guidance or historic design requirements before budgeting those projects.
See the assumptions and exclusions
Interior allowances cover a broad cosmetic or renovation scope and exclude the separately selectable systems. The moderate and extensive bands are not an instruction to renovate the whole house. Select only the scope you are considering; system boxes begin unchecked to avoid silently including extra work.
Roof size is not derived from interior square footage. System allowances are flat illustrative ranges, not measurements of your house. Treatment does not include termite-damaged structural wood. Flood remediation, mold assessment or removal, foundation repair, engineering, elevation, major structural rebuilding, permit charges, historic restoration, and unusual access costs are not separately priced. The contingency is simply a percentage of the selected allowances and may not cover these exclusions.
The tool does not predict a cash offer or subtract its result from a market value. Obtain property-specific professional advice where needed.
Cash Sale vs. Traditional Listing in Tampa
A traditional sale may produce a higher gross price, but commissions, seller closing costs, repairs, concessions and ongoing holding expenses reduce the amount you ultimately keep. A direct cash sale generally prioritizes speed, certainty and convenience rather than the highest possible gross price.
Tampa’s reported 46-day median marketing period makes holding expenses worth comparing. For a home with roof leaks, ask how an inspection or insurance requirement might affect a retail sale. Cash buyers can evaluate that condition directly, while conventional buyers may seek a repair credit. These are decision factors, not a prediction that your listing will fail.
| Decision Factor | Traditional Listing | Direct Cash Sale With MHIC |
|---|---|---|
| Gross Price | Potentially higher gross price | Usually lower than full retail value |
| Commissions | Agent commission may apply | No agent commission |
| Closing Costs | Seller closing costs may apply | MHIC pays normal closing costs |
| Property Condition | Repairs or buyer credits may be requested | Property sold as-is |
| Contingencies | Financing and appraisal contingencies | No buyer-financing contingency |
| Timeline | Longer and less predictable timeline | Seller selects an available closing date |
Agent commissions are negotiable; a fixed 6% charge is not assumed. MHIC charges no service fee. Your mortgage, lien payoffs, unpaid taxes, and any agreed prorations still affect proceeds. Confirm the purchase agreement and settlement statement; paying normal closing costs does not mean forgiving your debts. Other cash home buyers may allocate expenses differently.
Compare Your Estimated Selling Options
Use our adjustable calculator to compare a traditional listing with a direct cash sale using your property’s estimated value and expenses.
Use the Net-Proceeds Calculator →Probate, Foreclosure Deadlines, and Complicated Title Situations in Tampa
Facing foreclosure: verify the case and auction date first
Florida mortgage foreclosure is judicial: the lender files a circuit-court action. A mortgage foreclosure complaint and summons/service are distinct from a recorded lis pendens, which alerts others to litigation affecting the property. These rules concern mortgage foreclosure, not tax-deed sales.
- For covered servicing, the federal loss-mitigation rule generally requires more than 120 days of delinquency before the first foreclosure notice or filing, with exceptions including due-on-sale and lienholder joinder. It does not give every seller 120 days after receiving court papers.
- Rule 1.140(a) generally allows 20 days after service to answer, subject to statutory exceptions and procedural motions. Have an attorney review the actual papers and deadline.
- Under Florida’s judicial-sale statute, the final-judgment-to-sale window is generally 20–35 days; a later date is permitted with the plaintiff’s or attorney’s consent. Judgment notices include statutory surplus and homestead warnings. Sale notice is published on a qualifying public website for at least two consecutive weeks, or in a newspaper weekly for two consecutive weeks with the second publication at least five days before sale.
- Hillsborough’s Clerk requires sale notice and proof of publication at least 24 hours before auction. Regular online foreclosure sales are Monday–Friday at 10 a.m. through the county auction portal; verify the particular case’s scheduled sale and any court-approved change.
A cash offer is one possible sale option when you have authority to sell and enough time to complete the transaction. Signing a purchase contract does not itself postpone an auction. There is no verified practical Hillsborough default-to-sale average in this research; these separate timing rules should not be added into one universal countdown.
Florida’s redemption statute sets the cutoff at the later of the clerk’s certificate-of-sale filing or the time specified in the judgment/order. It does not create a fixed number of post-auction redemption days or an unconditional arrears-only reinstatement right. Before judgment, the required tender depends on the security agreement, valid acceleration, and reasonable foreclosure expenses; after judgment, the final-judgment amount matters. Ask the servicer for figures and a Florida attorney to interpret your rights.
Inherited property: eligibility is not authority to sign
Florida Summary Administration may be available if the estate subject to administration in Florida, less property exempt from creditors’ claims, does not exceed $150,000, or if the decedent has been dead for more than two years. The $150,000 threshold took effect July 1, 2026. It is not a gross worldwide-estate limit. A valid will directing Chapter 733 administration can exclude this route.
Real property is not categorically excluded, but a court order of summary administration is required for distribution or transfer under that procedure. Homestead and title requirements still need resolution, and known or reasonably ascertainable creditors must be identified, served, and provided for as required. A low estate value does not let an heir automatically sell the house. There is no universal 30-day wait for the monetary route; the separate two-year route and applicable petition and creditor rules must be checked.
The petition statute allows a beneficiary or will-nominated personal representative to petition, with surviving-spouse and beneficiary signing/joinder rules, exceptions, and notice to nonjoining beneficiaries. The procedure can apply to resident or nonresident decedents. Probate venue generally follows a Florida resident’s domicile county or, for a nonresident, a Florida county where property is located. Ask counsel which court and ownership documents apply to your case.
The verified local court reference is the Circuit Court of the Thirteenth Judicial Circuit, in and for Hillsborough County, Florida — Probate, Guardianship, Mental Health & Trust Division, at Edgecomb Courthouse, 800 E. Twiggs Street, Tampa, FL 33602. Check the assigned judge’s case-specific courtroom or office before attending.
Heirship, municipal liens, and unpaid property taxes
A closing title agency or attorney reviews the ownership chain, recorded claims, and evidence of authority. The Hillsborough County Clerk of the Circuit Court & Comptroller — Official Records / Recording maintains the recorded property documents, with the recording office at 419 Pierce Street, Room 140, Tampa, FL 33602. Ask the closing professional to explain every commitment requirement and payoff rather than assuming a lien will disappear when the house sells.
Tampa’s Neighborhood Enhancement Division handles relevant code matters. Its municipal lien and utility-balance search matters alongside the recorded-title search: an unresolved active code action can progress to a lien after ownership changes. The title professional should evaluate the case itself. The city balance search is not a statement that every ordinary electric bill attaches to title.
MHIC provides a direct purchasing option, not legal, tax, probate, financial, or foreclosure-defense advice. We cannot guarantee a stopped foreclosure, probate approval, lien removal, forgiven taxes, or clear title. Consult the court clerk, Tax Collector, Florida real estate attorney, or tax professional about your individual circumstances.
Unpaid Hillsborough Property Taxes: Ask for the Actual Payoff
The Hillsborough County Tax Collector is the relevant county tax-payment authority; the supplied research identifies Nancy Millan as Tax Collector. Real-estate taxes are payable beginning November 1 and become delinquent April 1 of the following year. When comparing a cash offer with a later sale, request the current amount owed instead of relying on an old annual bill.
Florida’s delinquency-interest statute provides an 18% annual rate with a 3% minimum, plus applicable advertising and collection/sale costs. Unpaid real-property taxes can enter a tax certificate sale on or before June 1. Certificate interest is bid competitively, up to 18%; the certificate creates a lien rather than immediate ownership of the house.
Once a certificate exists, its redemption amount includes principal, applicable interest, and statutory costs. Under the certificate-redemption rule, a 5% minimum can apply when accrued interest is below 5% of face value, except to certificates bid at 0%. Do not stack these figures into a made-up universal penalty. The closing professional needs the Tax Collector’s current redemption or payoff figure.
We can review a Tampa property with unpaid taxes, but a fair cash offer does not establish that its proceeds will cover every debt. Ask to see the estimated amount left after mortgages, recorded liens, taxes, and agreed settlement adjustments.
What Happens Between Accepting Your Cash Offer and Getting Paid in Tampa?
We buy houses for cash, but the available closing date still depends on authority, searches, payoffs, signatures, and disbursement. The sequence below uses the requested day markers as an illustrative target for an already-prepared file, not a five-day promise. Tampa’s municipal search alone is published at seven business days; an applicable HOA estoppel generally has a ten-business-day issuance period.
Day 0 target · Agreement and contract
Review the price, property condition, access, included contents, deposit, any inspection or termination rights, and expense allocation before both sides sign. MHIC charges zero service fees and no agent commissions. The agreement should explain who pays normal transaction expenses and how existing debts affect your proceeds.
Florida Department of Financial Services guidance allows a title agency or attorney to handle closing/title work. The title-premium payer has first choice of agent, and buyer and seller should agree on the provider. The guidance does not establish attorney-only closings or who customarily pays the premium in Hillsborough; use the agreement.
Days 1–2 target · Order searches and review the file
The selected closing professional reviews Hillsborough Official Records for deeds, the ownership chain, mortgages, releases, judgments, liens, and property-related litigation, then explains title-commitment requirements and exceptions.
Request Tampa’s code-enforcement lien and utility-balance search through Conduits / Net Assets early. The published fee is $25, responses are provided within seven business days, and payoff letters are valid for 45 days. Starting this request on day one can extend the closing beyond day five.
Check unpaid taxes/certificates and the City’s permit and inspection history. For an applicable HOA, the statutory estoppel certificate generally must be issued within ten business days. Other jurisdictions have their own searches; a Tampa mailing address does not prove the property is within Tampa city limits.
Days 2–4 target · Obtain payoffs and address requirements
Request mortgage and lien payoffs, current Tax Collector redemption figures, and any required estate or ownership documentation. Title requirements must be addressed before insuring and disbursing. A negotiation, release, court order, or new document can take longer than this sample window.
Tampa’s Construction Services Division handles reported work without a permit. Its published reporting number is 813-274-3198. Use the permit record to determine what needs professional review; selling as-is does not supply a missing permit.
Day 5 target, or the later agreed date · Signing, recording, and proceeds
A statutory warranty deed is one available private-transfer instrument; it carries the full-warranty covenants described in Florida law. The contract, ownership, and title requirements determine the appropriate deed; it is not mandatory for every transfer.
Florida conveyance formalities generally require the grantor or authorized agent to sign before two subscribing witnesses, subject to statutory exceptions. Recording requires acknowledgment or permitted proof of execution; ordinary closings use a notarial acknowledgment. Hillsborough requires witnesses’ printed names and addresses. A married homestead owner’s spouse must join the conveyance under Article X, section 4(c) of the Florida Constitution, even when only one spouse holds title.
The closing professional coordinates submission to the Hillsborough Official Records recording office. Documented Florida payment options include a bank wire or closing-agent check; proceeds and wire-account ownership must match how title is held, including a trust where applicable. Signing, recording, and money appearing in your account are distinct events. Confirm disbursement conditions and bank timing with the closing agent; no universal same-day funding guarantee applies here.
Out-of-town signing and notary records
Florida Bar closing guidance describes attended settlement and arranged mail-away execution. Ask the closing professional what is acceptable for your file.
For traditional notarizations, the Governor’s notary manual recommends a journal without making it mandatory. Florida does not require a thumbprint; a consenting signer may provide one, but declining is not by itself grounds to refuse notarization. For online notarizations, Florida’s separate electronic-journal and recording rules require secure records and at least ten years’ retention as specified by statute. Availability for your deed must be arranged with the closing professional.
A clean, prepared file can move faster than a contested estate or property with unresolved claims. We help coordinate the purchase; the closing title agency or attorney determines what the file requires. Confirm the closing provider in your agreement before relying on a proposed timetable.
How to Choose a Tampa Fast Home Buyer
When you compare cash buyers, ask for a written offer showing the price, deposit, access requirements, termination rights, expense allocation, and whether assignment is allowed. Request proof of funds promptly—within 24 hours is a useful comparison target, not a legal Tampa deadline. Verify the buyer’s identity and closing contact independently.
A reputable cash home buyer should explain why the offer differs from full retail value: condition, comparable sales, project scope, and the buyer’s costs can all matter. Avoid bait-and-switch tactics, unsupported promises of a guaranteed cash offer, and hidden fees. Reviews can help, but they are not a substitute for the agreement and funding evidence.
In Tampa, also ask when the municipal lien search will be ordered and how an active code case will be addressed. The City’s seven-business-day search process provides a concrete test of whether a proposed timetable is realistic. Trusted cash home buyers should be willing to discuss that work before you rely on a deadline.
Share your Tampa property details and ask MHIC to explain a fair cash offer in writing. We buy homes as is, and you can compare our terms with other cash buyers or a listing. Read our why-sell-to-us guide and cash buying overview before deciding.
Compare multiple buyers on the same basis
A Tampa fast home buyer should explain the buying process as clearly as the price. When you compare reputable cash home buyers, ask each home buyer for the same information: price, funding evidence, inspection rights, any assignment provision, and an estimated settlement statement. That makes it easier to assess a fair deal instead of choosing the largest headline number.
We purchase houses in their as is condition and pay cash under the agreed terms. If you would rather use the traditional real estate market, ask real estate agents to estimate agent fees, possible buyer credits, and the time needed to market a house with its present condition. The traditional home selling process may suit you when maximizing gross price matters more than finishing quickly.
For Tampa homeowners comparing options across the Tampa Bay area, condition and jurisdiction matter more than a broad slogan. A Tampa fast home buyer evaluating a city property should account for its municipal search; a buyer working in a surrounding community needs the searches that apply there. Request a written timetable when you need to sell quickly, especially if you are facing foreclosure.
Tampa and Surrounding Communities Within 75 Miles
We review homes in Tampa and the nearby communities below. The supplied Census Gazetteer coordinate check places all 18 within 75 straight-line miles of Tampa’s internal representative point, 27.970086, −82.479673. This point is not a surveyed downtown center; road distances differ. Property type, access, and title still affect whether a purchase is workable.
Showing Tampa, Florida. Choose a community to change the Google map.
The map is for exploring these service communities; it does not display a drawn 75-mile boundary or determine parcel eligibility. The municipal and county rules described above apply to Tampa / Hillsborough as specified, not automatically to every mapped community. Send the street address if your home is outside the named areas.
To sell your Tampa house fast, share the complete address rather than only a ZIP code. We buy houses for cash in Tampa and review the listed surrounding communities; a Tampa Bay mailing name alone does not identify the government office responsible for permits or code matters.
Tampa Cash Home Sale Questions
How can I sell my house fast in Tampa?
Start with the address, condition, ownership details, and the date you hope to finish. We buy houses in Tampa and can review an as-is cash offer without a listing. If you accept, a title agency or attorney handles the required closing work. Order Tampa’s municipal search early; its published seven-business-day response means a very short closing requires a file that is already prepared.
Can I sell my house for cash in Tampa without fixing it first?
Yes. MHIC can evaluate the house in its present condition, including a leaking roof, worn finishes, or cleanout needs. We buy houses for cash and account for the work in the offer. Tampa floodplain and historic-district rules may affect a repair-and-list alternative, so compare that scope before committing to repairs. An as-is purchase still requires agreed access, ownership authority, and closing review.
How quickly can a cash sale close in Tampa, FL?
MHIC advertises closings in as little as seven days for qualifying, prepared files. That is a possibility, not a guarantee for every Tampa home. The municipal lien search is published at seven business days; an applicable HOA estoppel generally has a ten-business-day issuance period. Estate orders, payoff delays, or title defects can require more time. Ask the closing professional to confirm the available date.
Are Tampa home prices dropping?
The supplied city report for the three months ending August 2026 recorded a $478,683 median sale price, up 10% year over year. It also reported price drops on 42% of listings and a 46-day median marketing period. A listing-price reduction is different from a decline in the citywide median. Compare current sales of similar homes before using that dated snapshot to price your house.
Is now a good time to sell a house in Tampa, Florida?
It depends on your property and goals. The supplied report shows price growth alongside longer marketing than the prior year. If your house is ready for retail buyers and you can allow for marketing, listing may produce a higher gross price. If roof, flood-related, or title work changes the plan, compare a written cash offer with expected listing proceeds and holding expenses. Citywide figures cannot time the best sale for an individual owner.
How do I get my Tampa house sold ASAP?
Confirm who can sign, gather mortgage and tax payoff information, disclose the actual condition, and choose a buyer with documented funds and workable written terms. Start the Tampa municipal search promptly. Cash buyers remove a buyer-financing contingency, but they still need the file’s closing requirements addressed. If an auction is scheduled, have your attorney confirm the deadline; an offer does not postpone it.
What is the 3-3-3 rule in real estate?
Ask the person using that phrase what they mean and which source supports it. It is not a closing deadline or authority-to-sell rule established in the Tampa research used here. For this transaction, rely on the signed contract, the City’s search timing, applicable Florida statutes, and the closing professional’s requirements rather than an unexplained marketing label.
Can I sell an inherited Tampa house while probate is underway?
A buyer can discuss a potential purchase while the estate work is underway, but the person signing must have the required authority and the title file must satisfy applicable court and ownership requirements. Florida summary administration may qualify under its $150,000 statutory valuation test or the more-than-two-years alternative, subject to exclusions. A court order is required under that route; qualifying does not automatically authorize an heir to sell.
Can selling to cash buyers stop a Hillsborough foreclosure?
A completed sale may be one option when the owner has authority, enough time, and a workable payoff. MHIC cannot guarantee foreclosure prevention. A purchase contract or cash offer does not itself stop a judicial auction. Check the case-specific sale date with the Clerk and have a Florida attorney review redemption, payoff, and any required court action.
Are agent commissions and closing costs taken out of my offer?
MHIC charges no agent commission or service fee and pays normal closing costs under the agreed purchase terms. Existing mortgages, unpaid taxes, liens, and agreed prorations still affect the amount you receive. Ask for an estimated settlement statement. Other cash buyers may use different expense allocations, and a listing agent’s commission is negotiable.
Do you buy houses with unpermitted work or active code cases?
We can evaluate the property for an as-is purchase, but the condition and unresolved requirements affect the proposal and closing. Tampa Construction Services handles permit and inspection questions. Neighborhood Enhancement’s search covers relevant code liens and municipal utility balances, and an active unresolved action can progress after ownership changes. The closing professional should review the case rather than treating an as-is sale as a permit or lien cure.
What should I ask a Tampa fast home buyer before I accept?
Ask how the buyer will verify funds, order Tampa’s municipal search, address any active code case, and confirm the closing timetable. A useful question is: “If I want to sell my house fast, what could extend this particular file?” Cash home buyers in Tampa should explain the written terms and expected proceeds. Compare the answer with a traditional sale, including estimated realtor fees and possible inspection requests from traditional buyers.
Do most cash buyers offer the same terms?
No two proposals should be assumed identical. Compare the agreement, funding evidence, assignment rights, access, and expense allocation. MHIC pays normal transaction expenses under the purchase terms, but ask each buyer who pays closing costs and whether any service fee applies. If you want to sell as is for cash in Tampa, ask what repair requests or termination rights remain in the contract. Many homeowners find that written comparison more useful than a broad promise to sell your house fast.
Which residential ZIP codes do you cover in Tampa and the surrounding area?
We review residential properties across Tampa and all 18 surrounding communities named on this page. The ZIP list below covers standard residential delivery areas associated with those places; postal names and municipal boundaries can overlap. PO-box-only, unique institutional, and military-base ZIPs are excluded. Send the actual street address to confirm service.
| Community / Postal Area | Residential ZIP Codes |
|---|---|
| Tampa and adjoining Tampa-address residential areas | 33602, 33603, 33604, 33605, 33606, 33607, 33609, 33610, 33611, 33612, 33613, 33614, 33615, 33616, 33617, 33618, 33619, 33624, 33625, 33626, 33629, 33634, 33635, 33637, 33647 |
| Brandon | 33510, 33511 |
| Riverview | 33569, 33578, 33579 |
| Temple Terrace | 33617, 33637 |
| Plant City | 33563, 33565, 33566, 33567 |
| Valrico | 33594, 33596 |
| Lutz | 33548, 33549, 33558, 33559 |
| Wesley Chapel | 33543, 33544, 33545 |
| Land O’ Lakes | 34637, 34638, 34639 |
| Zephyrhills | 33540, 33541, 33542, 33543, 33544, 33545 |
| Dade City | 33523, 33525 |
| Lakeland | 33801, 33803, 33805, 33809, 33810, 33811, 33812, 33813, 33815 |
| Clearwater / Clearwater Beach | 33755, 33756, 33759, 33760, 33761, 33762, 33763, 33764, 33765, 33767 |
| Largo | 33770, 33771, 33773, 33774, 33778 |
| Dunedin | 34698 |
| Safety Harbor | 34695 |
| Palm Harbor | 34683, 34684, 34685 |
| Oldsmar | 34677 |
| St. Petersburg and adjoining postal communities | 33701, 33702, 33703, 33704, 33705, 33706, 33707, 33708, 33709, 33710, 33711, 33712, 33713, 33714, 33715, 33716 |
The directory was cross-checked against the Florida ZIP type and city directory. It is not a claim to list every ZIP intersecting a 75-mile circle. Use USPS address lookup for the property’s current mailing ZIP. An overlapping or unlisted ZIP does not automatically exclude a home.
Tampa Real Estate & Legal Terms Homeowners Should Know
Lis pendens: Recorded notice of litigation affecting real property; a seller/title agent must examine the underlying case when clearing title. Official source →
Tax certificate: Interest-bearing lien arising from unpaid property taxes. A certificate buyer receives a lien, not immediate ownership; a sale closing needs the correct redemption payoff. Official source →
Summary administration: Florida court probate route available under the $150,000 statutory valuation test or after death more than two years earlier, subject to eligibility; inherited-property sellers need the distribution order. Official source →
Substantial damage / FEMA 50% Rule: Tampa's floodplain ordinance defines substantial damage as restoration cost equal to or exceeding 50% of the structure's pre-damage market value. In regulated flood areas this can trigger flood-resistant construction; obtain the City's determination before planning repairs. Official source →
Certificate of Appropriateness (COA): Historic-preservation approval for regulated changes in Tampa's designated historic districts; verify approval requirements before exterior repair or replacement work. Official source →
HOA estoppel certificate: Association statement of assessments and required account/property information used to establish amounts and issues to address in a sale closing. Official source →
Ready to Sell Your House Fast in Tampa?
Send the address and condition of your Tampa home, and tell us the timing you have in mind. We buy houses in Tampa as-is and explain a written fair cash offer, so you can compare it with your other selling options. There is no obligation to accept. You can sell your house fast when the title work and agreed timing permit; the offer gives you a concrete starting point for that decision.
Request Your Free Cash Offer
For a direct conversation, call (866) 651-6617 or use the form. Share any scheduled auction, estate issue, or unresolved code notice early so the closing timetable can be assessed.
Choose after reviewing the price, terms, expenses, and available closing date.
Official Tampa Homeowner Resources
Use these official offices and primary resources to check the particular property, court case, tax account, permit record, or insurance requirement. Tampa and Hillsborough sources have the jurisdiction stated in their guidance.