
Sell My House Fast in Hartford, CT — We Buy Houses for Cash
(866) 651-6617 CLICK TO CALL NOW FOR A FAST, NO OBLIGATION CASH OFFERTo sell your house fast in Hartford, CT, call or share your address, condition and timing today. We buy houses in Hartford as-is for cash. Review your written offer, then choose an available closing date with a Connecticut closing attorney. Compare the proceeds with listing before deciding.
Get a Fair As-Is Cash Offer Without Listings, Repairs, or Commissions
Use our fast response form to receive a fair all cash offer today.
Talk with trusted real estate professionals from MyHouseIntoCash to buy your house fast. We handle all the paperwork and tailor a hassle free closing process to fit your moving plans.
Receive a clear, no obligation offer with zero pressure and zero spam.
Hartford market watch
A Competitive Market Still Leaves You a Choice
Redfin’s Hartford city report for the three months ending August 2026 describes the market as “Very Competitive,” with a 78/100 Compete Score, a 102.2% sale-to-list ratio and an average 32 days to pending. Median days on market rose by two days from a year earlier. The 32-day average and 37-day median are different measures; neither guarantees your selling price or includes a promised cash-closing date.
A home ready for retail buyers may benefit from listing. If repairs, a rental deadline or an ownership question change your plans, compare a written cash offer against the work and money needed to list. Homeowners asking “How can I sell my house fast in Hartford?” should compare net proceeds and contract terms, not just headline prices. Explore our Connecticut cash home buying service.
Reporting period: three months ending August 2026. Data in the supplied brief was retrieved October 7, 2026. Market figures describe retail sales, not the value of a particular as-is property.
Your current-condition selling option
Sell It Exactly as It Sits in Hartford
We buy houses in Hartford, CT, in their current condition. You can request an offer before hiring a contractor or clearing every room. Hartford’s adopted 2022 housing plan estimates that about half of all housing units were built before 1950, a quarter during 1950–1970 and a quarter after 1970. Those are approximate planning figures, not a new 2026 survey or single-family-only counts. For an older home, an as-is offer lets you compare the cost of updating with a sale that accounts for its existing condition.
- ✓Don’t paint. Skip interior touch-ups and exterior repainting.
- ✓Don’t replace flooring. Leave stained carpets, worn hardwoods or cracked tile.
- ✓Don’t fix the roof. We evaluate homes with active leaks, missing shingles or aged roofs.
- ✓Don’t stage the home. Avoid professional staging and decluttering costs.
- ✓Don’t clean it out. Take what you want; arrange in writing to leave unwanted furniture, trash and clutter behind.
- ✓Don’t schedule dozens of showings. Skip open houses and lockboxes; coordinate the access needed for our property review.
An as-is sale does not remove applicable disclosure duties. For covered pre-1978 housing, Connecticut’s lead-disclosure guidance explains the known-lead information, available reports and federal pamphlet required. Buyers generally receive a ten-day lead-inspection opportunity unless waived. Read the inspection, cancellation and items-left-behind provisions in your agreement.
Our guide to selling a house as-is explains the broader decision. Tell us about known issues so the written offer reflects the property you actually have.
Historic housing, practical decisions
Selling a House in Hartford’s Neighborhoods
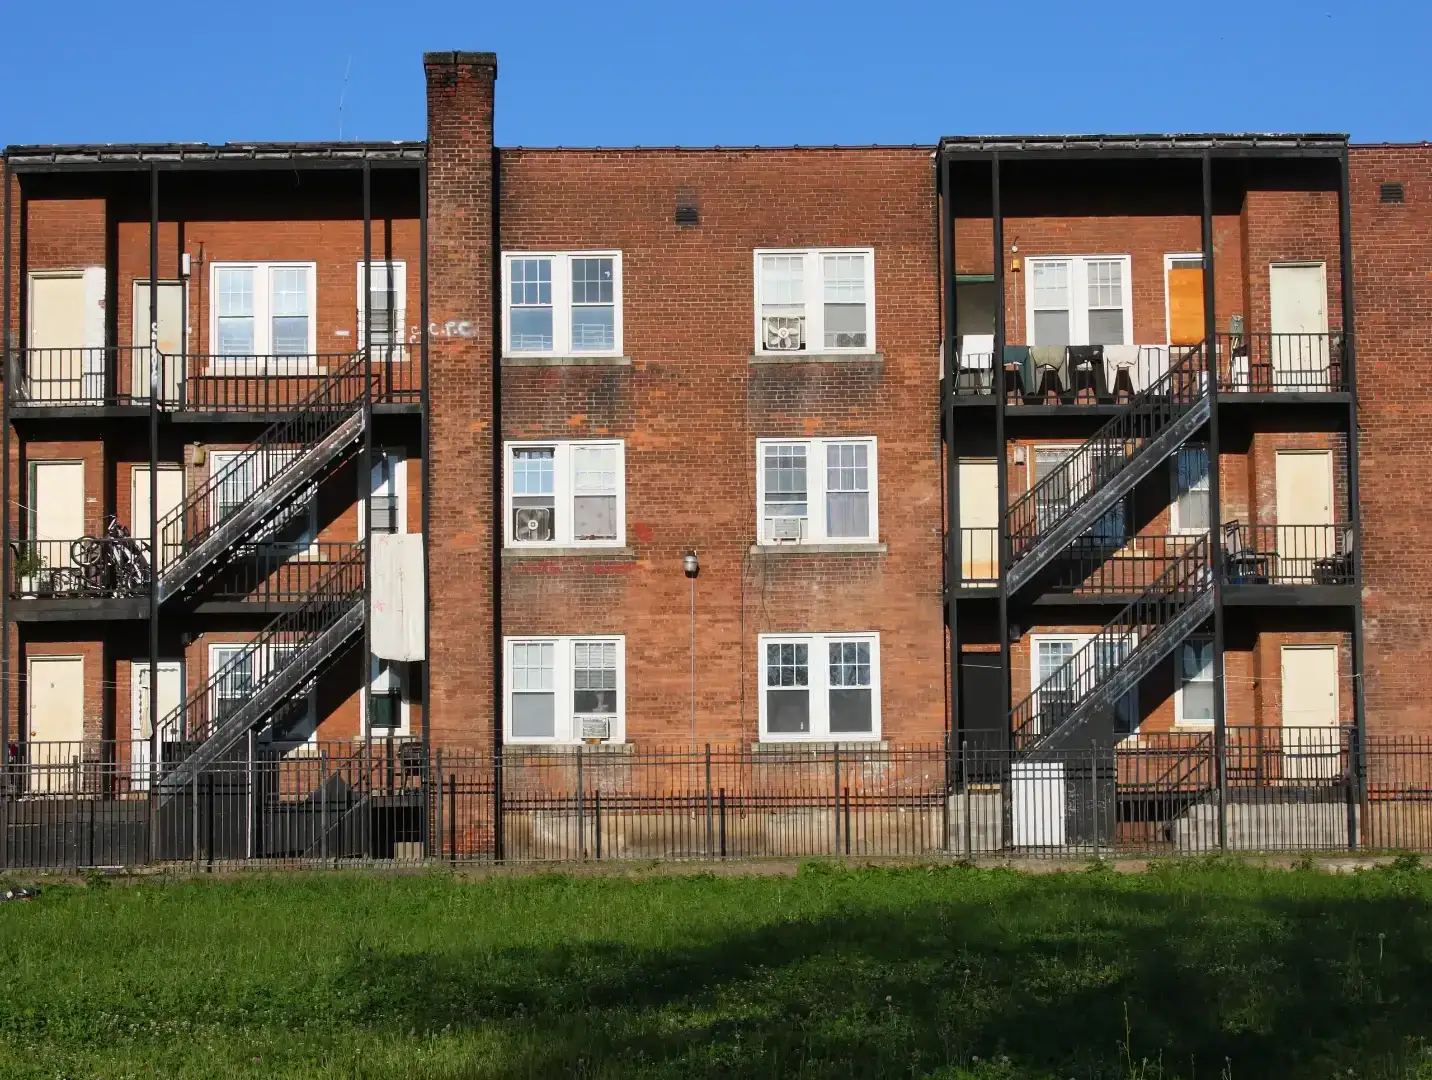
Historic inventories document local wood-frame and brick houses, including mixed brick-and-wood examples. They also record cross-gabled, hipped and gambrel roofs, with slate and asphalt replacements among the examples. These records describe buildings and eras; they do not establish today’s condition, a dominant citywide material or a defect rate. Use them to ask better questions about your own house.
| Neighborhood / District | Housing Profile | Common Challenges We Resolve | Seller Scenario |
|---|---|---|---|
| West End | The West End North inventory includes late-19th- and early-20th-century wood-frame and brick Queen Anne, Shingle and Colonial Revival houses. The district extends into West Hartford. | Evaluate the cost of restoration and worn finishes. Retained pre-1978 paint may need specialist assessment; covered exterior changes or demolition require applicable historic review. | An owner could compare restoration-and-listing costs with a current-condition offer. This is an example, not a measured neighborhood selling trend. |
| Frog Hollow | The historic core dates approximately to 1850–1910, including wood Greek Revival houses, brick Italianate houses and double houses, and Queen Anne rowhouses. | Review painted surfaces, rental heating records and applicable lead compliance. Qualifying three-unit rentals are included in the city’s 2026 licensing phase. | A rental owner could compare documented compliance and repair work with an as-is sale. No landlord-exit frequency is established. |
| Asylum Hill | The Collins and Townley Streets inventory records 19th-century Italianate double houses, Queen Anne, Shingle and Colonial Revival buildings, plus brick and wood apartment houses. | Account for deferred maintenance and known reports. For covered rentals, heating documentation and housing/fire inspections matter to licensing. | An owner managing an older rental could assess a direct offer alongside a repair plan. A historic description does not show the building’s present condition. |
For the applicable property, check Hartford Planning & Zoning’s historic review requirements, Connecticut DPH lead-inspection guidance and the city rental-license requirements. Seller scenarios above are practical examples inferred from these requirements.
What can change the repair-and-list plan
Hartford Property Conditions Worth Checking Before You Spend
Older painted windows and doors
In pre-1978 homes with retained lead-based coatings, deterioration and friction can create chips and dust that contaminate living areas. The EPA’s lead guidance explains the mechanism. Peeling, chipping, chalking, cracking or debris warrants attention, but appearance and building age do not prove lead is present.
A general home inspection is not a licensed lead inspection. Use an applicable DPH-qualified specialist and share existing reports. Assessment, lead-safe work and buyer inspection decisions can change a listing plan; an as-is purchase still carries applicable disclosures.
Scope: an era-specific concern, not a finding that every older Hartford house contains hazardous lead.
Ice dams and interior water damage
The Connecticut Insurance Department’s winter alert describes how heat leakage or inadequate attic insulation can warm a snowy pitched roof. Meltwater refreezes at colder eaves, and an ice dam can back water into the building.
Roof-edge ice, persistent eave icicles and upstairs stains after snowmelt are possible screening signs inferred from that mechanism; an inspection is needed to identify the cause. In a sale, documented damage may prompt repair allowances or negotiated credits. Insurance generally covers ice-dam damage subject to the policy; ice removal, pre-existing damage and exclusions may differ.
Scope: a Connecticut winter tendency, not evidence of unusually high Hartford-wide prevalence.
Water history is specific to the parcel
The joint Hartford/West Hartford flood study addresses Kane and Kennedy Brooks, the South Branch Park River and connected storm drainage. It does not designate every Hartford house as flood-prone.
Gather actual water history and drainage reports, and have the address’s flood mapping reviewed. Ordinary homeowners insurance generally excludes flood. Connecticut’s § 49-7b flood notice requirement, effective July 1, 2026, applies to covered mortgage applicants at least ten days before closing; it is not an automatic waiting period for every cash sale.
Roof condition can affect insurance
The Connecticut Insurance Department’s Roof Risk FAQ identifies damaged or missing shingles, excessive layers, unrepaired damage, moss or debris, and overhanging limbs as possible underwriting concerns. Roof-age rules vary by material and carrier; there is no universal 15-year cutoff. Cosmetic discoloration visible only in aerial imagery is insufficient by itself.
Ask the insurer what evidence it needs before paying for a replacement solely to make a sale possible. Nonrenewal requires at least 60 days’ written notice with reasons. The Connecticut FAIR Plan is an eligibility-based option for applicants unable to obtain ordinary-market coverage. A direct offer can be compared with repair and coverage options; it cannot promise insurability.
Snow and ice, frozen pipes and winter tree damage are also documented Connecticut hazards in the winter alert. No Hartford citywide defect ranking, foundation-system distribution, four-point inspection mandate or insurer market-share claim is assumed here.
A dated local compliance checkpoint
Selling a Hartford Rental or a Home With Unfinished Permit Work
Hartford’s rental-license program gives qualifying three-unit buildings, excluding owner-occupied properties, a July 1–October 31, 2026 application window. The license runs for four years. Heating documentation, housing/fire inspections and applicable lead-safe reports are part of the documented compliance checkpoints.
If you are considering a sale, organize the lease, license status, inspection correspondence and known repair reports. Ask the city what obligations apply while the property is owned or transferred. An offer is one option to evaluate; requesting it does not cancel a licensing deadline. The deadline establishes a compliance trigger, not evidence of widespread landlord selling.
Hartford Licenses & Inspections / Housing Code Enforcement handles building permits, plan review, inspections and code compliance, including heat, hot water, sanitation and ventilation concerns. Historic work may also need Planning & Zoning review. For an altered unit or unfinished project, ask about the actual address and work; a building’s age alone does not establish a violation.
Eversource is Hartford’s electric delivery utility through Connecticut Light and Power Company doing business as Eversource; the competitive electricity supplier may differ. Arrange account changes separately with the utility. Ordinary electric bills are not treated as title liens in this page’s closing explanation.
Interactive planning tool
As-Is Repair Cost Estimator
Use a broad repair allowance to compare listing preparation with an as-is offer. Hartford’s older housing stock and applicable lead or historic-review requirements can add specialist work outside a cosmetic budget. This tool is not an inspection, appraisal, contractor quote, offer or guarantee. The amounts below are illustrative U.S.-dollar planning assumptions, not measured Hartford contractor prices.
Interior finish rates cover a broad finish allowance. Add only work outside that scope to avoid counting it twice. All additional work is unselected by default.
Actual costs vary substantially with scope, materials, labor, permitting, access and concealed damage. Structural work, lead assessment or abatement, historic restoration, flood remediation and hazardous-material work need separate qualified bids. Insurance coverage is separate. This range is not an automatic deduction from your cash offer.
Compare the money and the terms
Cash Sale vs. Traditional Listing in Hartford
A traditional sale may produce a higher gross price, but commissions, seller closing costs, repairs, concessions and ongoing holding expenses reduce the amount you ultimately keep. A direct cash sale generally prioritizes speed, certainty and convenience rather than the highest possible gross price.
Hartford’s reported 102.2% sale-to-list ratio is a reason to consider retail exposure when the home and your timing suit it. It does not mean every property sells above asking or that a cash offer matches the city median. If you are comparing cash home buyers in Hartford, obtain a written price, cost allocation and cancellation terms for each offer.
| Decision Point | Traditional Listing | Direct Cash Sale With MHIC |
|---|---|---|
| Gross Price | Potentially higher gross price | Usually lower than full retail value |
| Commissions | Agent commission may apply | No agent commission |
| Closing Costs | Seller closing costs may apply | MHIC pays normal closing costs |
| Property Condition | Repairs or buyer credits may be requested | Property sold as-is |
| Contingencies | Financing and appraisal contingencies | No buyer-financing contingency |
| Timeline | Longer and less predictable timeline | Seller selects an available closing date |
Confirm all terms in the purchase agreement. Inspection, title, authority and other written conditions may still apply to a cash purchase. Mortgage balances, property taxes, recorded claims and any negotiated exceptions affect net proceeds in either route. Normal closing costs paid by MHIC do not erase the seller’s debts.
Compare Your Estimated Selling Options
Use our adjustable calculator to compare a traditional listing with a direct cash sale using your property’s estimated value and expenses.
Use the Net-Proceeds Calculator →Confirm the authority and the actual deadline
Probate, Foreclosure Deadlines, and Complicated Title Situations in Hartford
An inherited house is outside the small-estate affidavit route
Connecticut’s affidavit in lieu of probate procedure under §§ 45a-273 and 45a-275 covers solely owned probate personal property totaling no more than $40,000, without deducting debts; nonprobate assets are excluded. The decedent must have had no solely owned Connecticut real property at death. This procedure does not transfer an individually owned Hartford house. A low estate value alone does not authorize an heir to sell real estate.
The surviving spouse may file; otherwise next of kin, or a sufficiently interested person approved by the court, including a creditor, may qualify. File in the decedent’s probate district of residence; § 45a-273 imposes no separate Connecticut-residency requirement on the affiant. A Probate Court decree is required, ordinarily without notice and hearing. Over-limit personal assets, solely owned Connecticut real estate or existing formal proceedings prevent this route. A differing will can require waivers or consents; unpaid debts alone do not disqualify it.
Section 45a-275 addresses the situation where neither will probate nor administration is requested within 30 days after death. Separately, the court must wait 30 days after sending the affidavit to the Department of Administrative Services before issuing its decree. These are distinct periods, not a shortcut to a house sale.
The Hartford Probate Court (PD-01), with jurisdiction over Hartford, is at 250 Constitution Plaza, 3rd Floor, Hartford, CT 06103-2814. Ask the court and a Connecticut attorney which authority and documents the particular estate requires. Use our inherited-house selling guide to compare keeping, listing and a direct purchase.
Strict foreclosure can end without an auction
Connecticut uses a judicial foreclosure process, including strict foreclosure, foreclosure by sale and qualifying foreclosure by market sale. A writ, summons and foreclosure complaint initiate the action; a recorded lis pendens gives notice of the pending property case.
In strict foreclosure, the court sets law days for redemption and there is no auction. In foreclosure by sale, consult the case-specific court order and Judicial Branch’s Pending Foreclosure Sales notice for the date, venue, advertising and conditions. There is no single statewide newspaper-publication schedule.
- For covered mortgages, Regulation X § 1024.41(f) generally prohibits the first foreclosure filing until delinquency exceeds 120 days; exceptions apply.
- For covered EMAP loans, § 8-265ee requires notice allowing 60 days to seek a conference or contact CHFA.
- Superior Court process must be served at least 12 days before the return date. Covered owner-occupied borrowers receive mediation forms with service; appearance and the mediation certificate are due 15 days after the return date.
- Qualifying mediation prevents judgment until completion or termination. Filing, service, mediation and scheduling are separate stages; they do not establish one default-to-sale minimum.
Under § 49-25, payment of the full debt, interest and costs before sale stays proceedings; that section does not establish an arrears-only reinstatement right. Strict-foreclosure redemption is tied to the court-set law day. In foreclosure by sale, redemption remains possible before court confirmation; no fixed borrower redemption period follows a confirmed mortgage sale. Have counsel check the applicable route and actual orders.
A direct cash sale may be possible while the owner has legal authority and enough time to complete the transaction and necessary payoffs before the applicable deadline. An offer or signed contract does not pause the court case. No verified Hartford default-to-sale average is supplied, so this page does not estimate one. Our foreclosure selling guide explains the sale option; obtain qualified foreclosure advice promptly for your case.
Property taxes, heirs and recorded claims
The Hartford Town and City Clerk holds the city’s land records; this is not a county-recorder process. A closing attorney examines ownership, recorded mortgages and encumbrances, and the authority of anyone signing for an estate. Share heirship questions, code-enforcement notices, tax bills and known liens early. The attorney determines what documents, payoffs or releases are needed; a buyer cannot promise that every title cloud will be resolved.
Hartford is traditionally described as Hartford County. The Census Bureau now uses the Capitol Planning Region as the county equivalent; city offices still handle Hartford property-tax collection and land recording. That distinction helps you contact the correct office.
My House Into Cash provides a direct purchasing option, not legal, tax, probate, financial or foreclosure-defense advice. Consult the court clerk, Hartford Tax Collector, a Connecticut real estate attorney and a tax professional about your situation. We do not guarantee foreclosure prevention, court approval, probate authority, lien removal, tax forgiveness or title clearance.
Use a payoff for the planned closing date
Hartford Property Taxes: What Comes Out of the Sale Proceeds?
The City of Hartford Office of the Tax Collector generally bills real estate taxes in July 1 and January 1 installments. For the October 1, 2025 Grand List, the first installment was due July 1, 2026, with payment by August 3, 2026 avoiding delinquency.
Payments after August 3, 2026 incur interest calculated from July 1: 1.5% for each month or fraction of a month, equivalent to 18% annually, with a $2 minimum interest charge. The statutory interest rule makes a current, date-specific payoff more useful than the unpaid amount on an older bill.
Give the closing attorney the tax account details and mortgage payoff information before selecting a tight closing date. Compare the estimated funds remaining after debts and adjustments. MHIC paying normal closing costs does not mean a $200,000 offer produces $200,000 in your account when mortgages, taxes or recorded claims must be paid.
From written agreement to disbursement
What Happens Between Accepting Your Cash Offer and Getting Paid in Hartford?
A Connecticut-licensed attorney must conduct a paid ownership-transfer closing, including a cash purchase. The work includes title review, payoffs, adjustments, recording and disbursement. The schedule below is an illustrative five-day target for a ready-to-close file, not a promise. Title issues, court authority, payoff responses, signing arrangements and funding can require more time; agree on an available date after review.
Day 0: Mutual Agreement & Purchase Contract Finalized
Confirm the price, condition, access, items to remain, closing date, inspection/cancellation terms and written cost allocation. MHIC charges no purchasing fee or agent commission and pays normal closing costs under the agreement. Disclose known matters and provide estate or other signing-authority documents before assuming a short timeline is feasible.
Days 1–2: Title Search & Municipal Due Diligence
Following applicable Connecticut closing practice guidance, the attorney reviews Hartford town land records for the ownership chain, mortgages and recorded encumbrances; verifies property taxes and applicable water/sewer or association charges; and requests payoffs, releases and required common-charge certificates for applicable condominiums or PUDs. Disclosed code or permit issues are referred to the appropriate city office for the property.
Connecticut’s forty-year marketable-record-title framework has exceptions. It is not a universal search-depth checklist or a rule that erases every older claim. Lender title coverage may be required in financed transactions; owner coverage is considered separately.
Days 2–4: Payoff & Title Clearance
The attorney obtains dated mortgage and Hartford tax payoffs, reviews recorded claims and arranges the necessary releases or other documents. Applicable water/sewer and association balances are considered on their own facts. An unresolved heirship issue, estate authority, recorded lien or delayed release can extend this stage. Clearance must be established, not assumed from an accepted offer.
Day 5 target: Deed Signing, Recording & Funding
The contract and the grantor’s legal capacity determine the deed. Connecticut offers a statutory warranty deed with specified title covenants for an ordinary private sale; executor and administrator deeds are separate statutory forms. Under § 47-5, the written deed is signed by the grantor or authorized representative, acknowledged and attested by two witnesses, and includes the grantee’s current mailing address.
Arrange signing with the attorney: Connecticut remote notarization is prohibited for real-estate conveyance and closing documents. A notary journal is recommended rather than generally required, and these rules do not identify a general thumbprint mandate. The attorney records the instruments with the Hartford Town and City Clerk and disburses by wire or check under the closing instructions. Confirm actual disbursement and bank availability; same-day receipt is not guaranteed.
One possible attorney provider is The Jorgensen Law Firm, LLC, 89 Oak Street, Hartford, CT 06106, which advertises residential buyer/seller closings, complicated-title work and wires to sellers and lienholders. It is a candidate provider only; no MHIC partnership, approved-provider status or independent quality endorsement was verified. Connecticut Bar Association guidance also includes check disbursement. Choose and confirm the professionals for your transaction.
Hartford and all 18 supplied nearby communities
Explore the Hartford Area and a 75-Mile Reference Radius
Request an evaluation in Hartford, West Hartford, East Hartford, Wethersfield, Newington, Bloomfield, Windsor, South Windsor, Manchester, Glastonbury, Rocky Hill, Farmington, Avon, Simsbury, Canton, Berlin, New Britain, Enfield or Vernon. These nearby municipalities are documented in the Census Connecticut town Gazetteer. Send the street address so we can confirm whether the property is one we can purchase.
Regional overview centered on Hartford. Select a town to see its approximate straight-line distance from Hartford.
Check another location against the 75-mile radius
Enter the location’s latitude and longitude to check straight-line distance from Hartford’s Census center. Use the address’s coordinates rather than a town center for a property-specific check.
The 75-mile check is a geographic reference, not driving mileage or a guarantee of purchasing coverage. Town-center distances use Census reference points. Hartford’s center is 41.7660909, -72.6834574; it is a geographic centroid, not an office address. The Google map can be panned and zoomed; it does not draw a radius circle. Postal areas cross municipal boundaries.
For broader coverage, visit we buy houses throughout Connecticut. If your address is outside these communities, ask about it directly.
Terms you may see in Connecticut paperwork
Hartford Real Estate & Legal Terms Homeowners Should Know
- Strict foreclosure:
- Court-ordered title transfer after unredeemed law days, without an auction; deadlines constrain sellers. Read the source ↗
- Law day:
- Court-set strict-foreclosure redemption deadline; obtaining a buyer does not extend it. Read the source ↗
- Grand List:
- Hartford's October 1 assessment base used for the following tax bills; check the applicable list year and installments when planning closing payoffs. Read the source ↗
- Rental License:
- Hartford's four-year building license for covered rentals; qualifying three-unit applications are due October 31, 2026, except owner-occupied buildings. Read the source ↗
- Affidavit in lieu of probate:
- Court-approved small-estate personal-property procedure; it cannot transfer a solely owned Hartford house. Read the source ↗
- Root of title:
- The recorded conveyance or title transaction underlying Connecticut's forty-year marketable-title framework; statutory exceptions mean it does not erase every older claim. Read the source ↗
Direct answers for Hartford sellers
Frequently Asked Questions
Which residential ZIP codes do you cover in Hartford and the surrounding communities?
We evaluate properties in Hartford’s residential postal areas and the 18 nearby communities listed below. This is a residential mailing-area list, excluding PO-box-only and institutional or business-only codes; confirm the full street address before relying on a ZIP.
| Community / Postal Area | Residential ZIP Codes |
|---|---|
| Hartford | 06103, 06105, 06106, 06112, 06114, 06120 |
| West Hartford | 06107, 06110, 06117, 06119 |
| East Hartford | 06108, 06118 |
| Wethersfield | 06109 |
| Newington | 06111 |
| Bloomfield | 06002 |
| Windsor | 06095 |
| South Windsor | 06074 |
| Manchester | 06040, 06042 |
| Glastonbury / South Glastonbury | 06033, 06073 |
| Rocky Hill | 06067 |
| Farmington / Unionville | 06032, 06085 |
| Avon | 06001 |
| Simsbury / Tariffville / Weatogue / West Simsbury | 06070, 06081, 06089, 06092 |
| Canton | 06019 |
| Berlin / East Berlin | 06037, 06023 |
| New Britain | 06051, 06052, 06053 |
| Enfield | 06082 |
| Vernon / Vernon Rockville | 06066 |
Sources: the Hartford ZIP map, Connecticut’s postal directory and ZIP classification directory (October 1, 2026). Use USPS ZIP Code Lookup for the actual address. A postal-area name does not establish a municipal boundary or eligibility for an offer.
How do I sell my house for cash in Hartford?
Call (866) 651-6617 or submit your address, known condition and preferred timing. MHIC reviews the property and provides a written offer to consider. If you accept, a Connecticut-licensed attorney handles the closing, title review, payoffs, recording and disbursement. Confirm the price, net proceeds and available date in writing.
Can I sell a Hartford house as-is without fixing lead paint or roof damage?
You can request an as-is offer before completing repairs. Disclose known conditions and provide existing reports. Covered pre-1978 sales still have lead-disclosure requirements, and a general home inspection is not a licensed lead inspection. The agreement should explain access, inspection rights and any items left behind; an as-is label does not waive applicable duties.
Is a cash offer the best choice in Hartford’s competitive market?
It depends on your property and priorities. The supplied Redfin city report for the three months ending August 2026 shows a $339,775 median sale price, a 78/100 Compete Score and a 102.2% sale-to-list ratio. A ready-to-list house may benefit from retail exposure. Compare the listing’s estimated net proceeds, repair costs and timing with the written cash offer; those city averages do not value your house.
Can a Connecticut small-estate affidavit transfer my inherited Hartford house?
No. The affidavit in lieu of probate procedure covers qualifying solely owned probate personal property of no more than $40,000 without deducting debts, with nonprobate assets excluded. It requires that the decedent had no solely owned Connecticut real property at death. It does not transfer an individually owned Hartford house. Ask Hartford Probate Court and a Connecticut attorney to confirm the estate’s authority to sell.
Can a cash sale stop a Hartford foreclosure or extend a law day?
A cash sale can be one option if the owner has authority and sufficient time to complete the transaction and required payoffs before the applicable deadline. An offer or contract does not stop the case or extend a law day. Connecticut strict foreclosure has no auction; foreclosure by sale uses case-specific court orders. Have a Connecticut attorney verify the deadline and available remedies immediately.
What happens to unpaid Hartford property taxes at closing?
The closing attorney obtains the applicable tax payoff and accounts for it in the settlement. For the October 1, 2025 Grand List’s July 1, 2026 installment, payment after August 3, 2026 incurs interest from July 1 at 1.5% per month or fraction of a month, with a $2 minimum. Ask the Hartford Tax Collector for a current balance; normal closing costs paid by MHIC do not forgive property taxes.
What should I check before selling a Hartford three-unit rental?
Qualifying three-unit rentals, except owner-occupied buildings, have a July 1–October 31, 2026 rental-license application window. Gather the license status, leases, heating documentation, inspection correspondence and applicable lead-safe reports. Confirm transfer and compliance questions with Hartford Licenses & Inspections; requesting a purchase offer does not remove the deadline.
Can I sign a Hartford deed remotely?
Connecticut remote notarization is prohibited for real-estate conveyance and closing documents. A deed must be signed by the grantor or authorized representative, acknowledged and attested by two witnesses under § 47-5. Ask the closing attorney to arrange a lawful signing method, especially if you are out of state.
How quickly can a Hartford cash sale close and when will I receive the money?
A short closing target depends on verified signing authority, title, payoffs, access and available funding. The five-day example on this page is an illustrative ready-file schedule, not a guarantee. The Connecticut closing attorney records the instruments and disburses by wire or check under the instructions; bank availability and same-day receipt must be confirmed.
Does a wet Hartford basement mean the house is in a flood zone?
No. The joint Hartford/West Hartford study addresses specific watersheds and storm drainage, including Kane and Kennedy Brooks and the South Branch Park River. It does not establish a flood designation for every parcel. Review the address’s mapping, actual water history and drainage reports. Ordinary homeowners insurance generally excludes flood.
How should I compare cash buyers for houses in Hartford?
If you search “we buy houses Hartford CT” or “sell house fast Hartford CT,” compare each buyer’s identity and funding, written price, net proceeds, inspection and cancellation rights, cost allocation, signing requirements and available date. Ask who will conduct the Connecticut attorney closing and whether any title or estate issue must be resolved first. Do not assume a fast-offer headline promises immediate payment or clears legal deadlines.
Request a Cash Offer for Your Hartford House
Looking to sell your house fast in Hartford, CT? Share the address, known condition and the date you have in mind. We will explain a written offer and the closing requirements so you can decide how it compares with listing or keeping the property.
Request Your No-Obligation Offer →
Or call (866) 651-6617. This is MHIC’s published company number.
Learn how cash buyers calculate offers before comparing your options.
Primary sources for your property and transaction
Official Hartford Homeowner Resources
Use the office responsible for the actual parcel and issue. These links provide information; they do not establish an endorsement or partnership with MHIC.