
⚡ Get a cash offer in 5 - 10 minutes • Washington County, AR
Sell My House Fast in Fayetteville, AR — We Buy Houses for Cash
To sell your house fast in Fayetteville, AR, call or share your address today. We buy houses in Fayetteville, AR, as-is: review a written cash offer and choose an available closing date after title and payoff review.
A direct sale, a clear written offer, and a moving date you can plan around.
Get Your No-Obligation Offer
Sell your Fayetteville house as-is, for cash.
Tell us about the property and your preferred timing. Review the offer and written terms before deciding.
Fayetteville market watch
What Fayetteville’s Market Means for Your Selling Plan
Redfin’s Fayetteville report describes the three months ending September 2026 as somewhat competitive, with a 59/100 Compete Score and a 98.2% sale-to-list ratio. Its separate competitiveness panel quotes about 40 days to pending. Marketing time does not include the entire contract-to-closing period.
If your house is ready for retail buyers, a listing may justify the preparation and wait. If condition or timing matters more, compare a written as-is offer with the repairs, carrying costs and proceeds in a realistic listing plan.
Snapshot checked October 23, 2026. Citywide results are context, not a valuation or closing forecast for your property.
Our as-is purchase policy
Sell It Exactly as It Sits in Fayetteville
We buy houses in Fayetteville, AR, in their current condition. Request an offer before spending on listing preparation. The written agreement sets out the property review, items you want to leave, and the available closing date.
For most pre-1978 homes, federal lead-disclosure information must be provided before signing the sale contract. Selling for cash or as-is does not by itself remove that duty. Our as-is selling guide explains how to compare the options.
Match the plan to the actual house
Selling a House in Fayetteville’s Neighborhoods
Fayetteville’s April 2025 Housing Assessment, using 2023 ACS data, reports that 71.1% of occupied housing structures were built between 1980 and 2020. Historic-house concerns therefore belong to the applicable house and district. Start with construction date, maintenance records and any previous alterations.
| Neighborhood / District | Housing Profile | Common Challenges We Resolve | Seller Scenario |
|---|---|---|---|
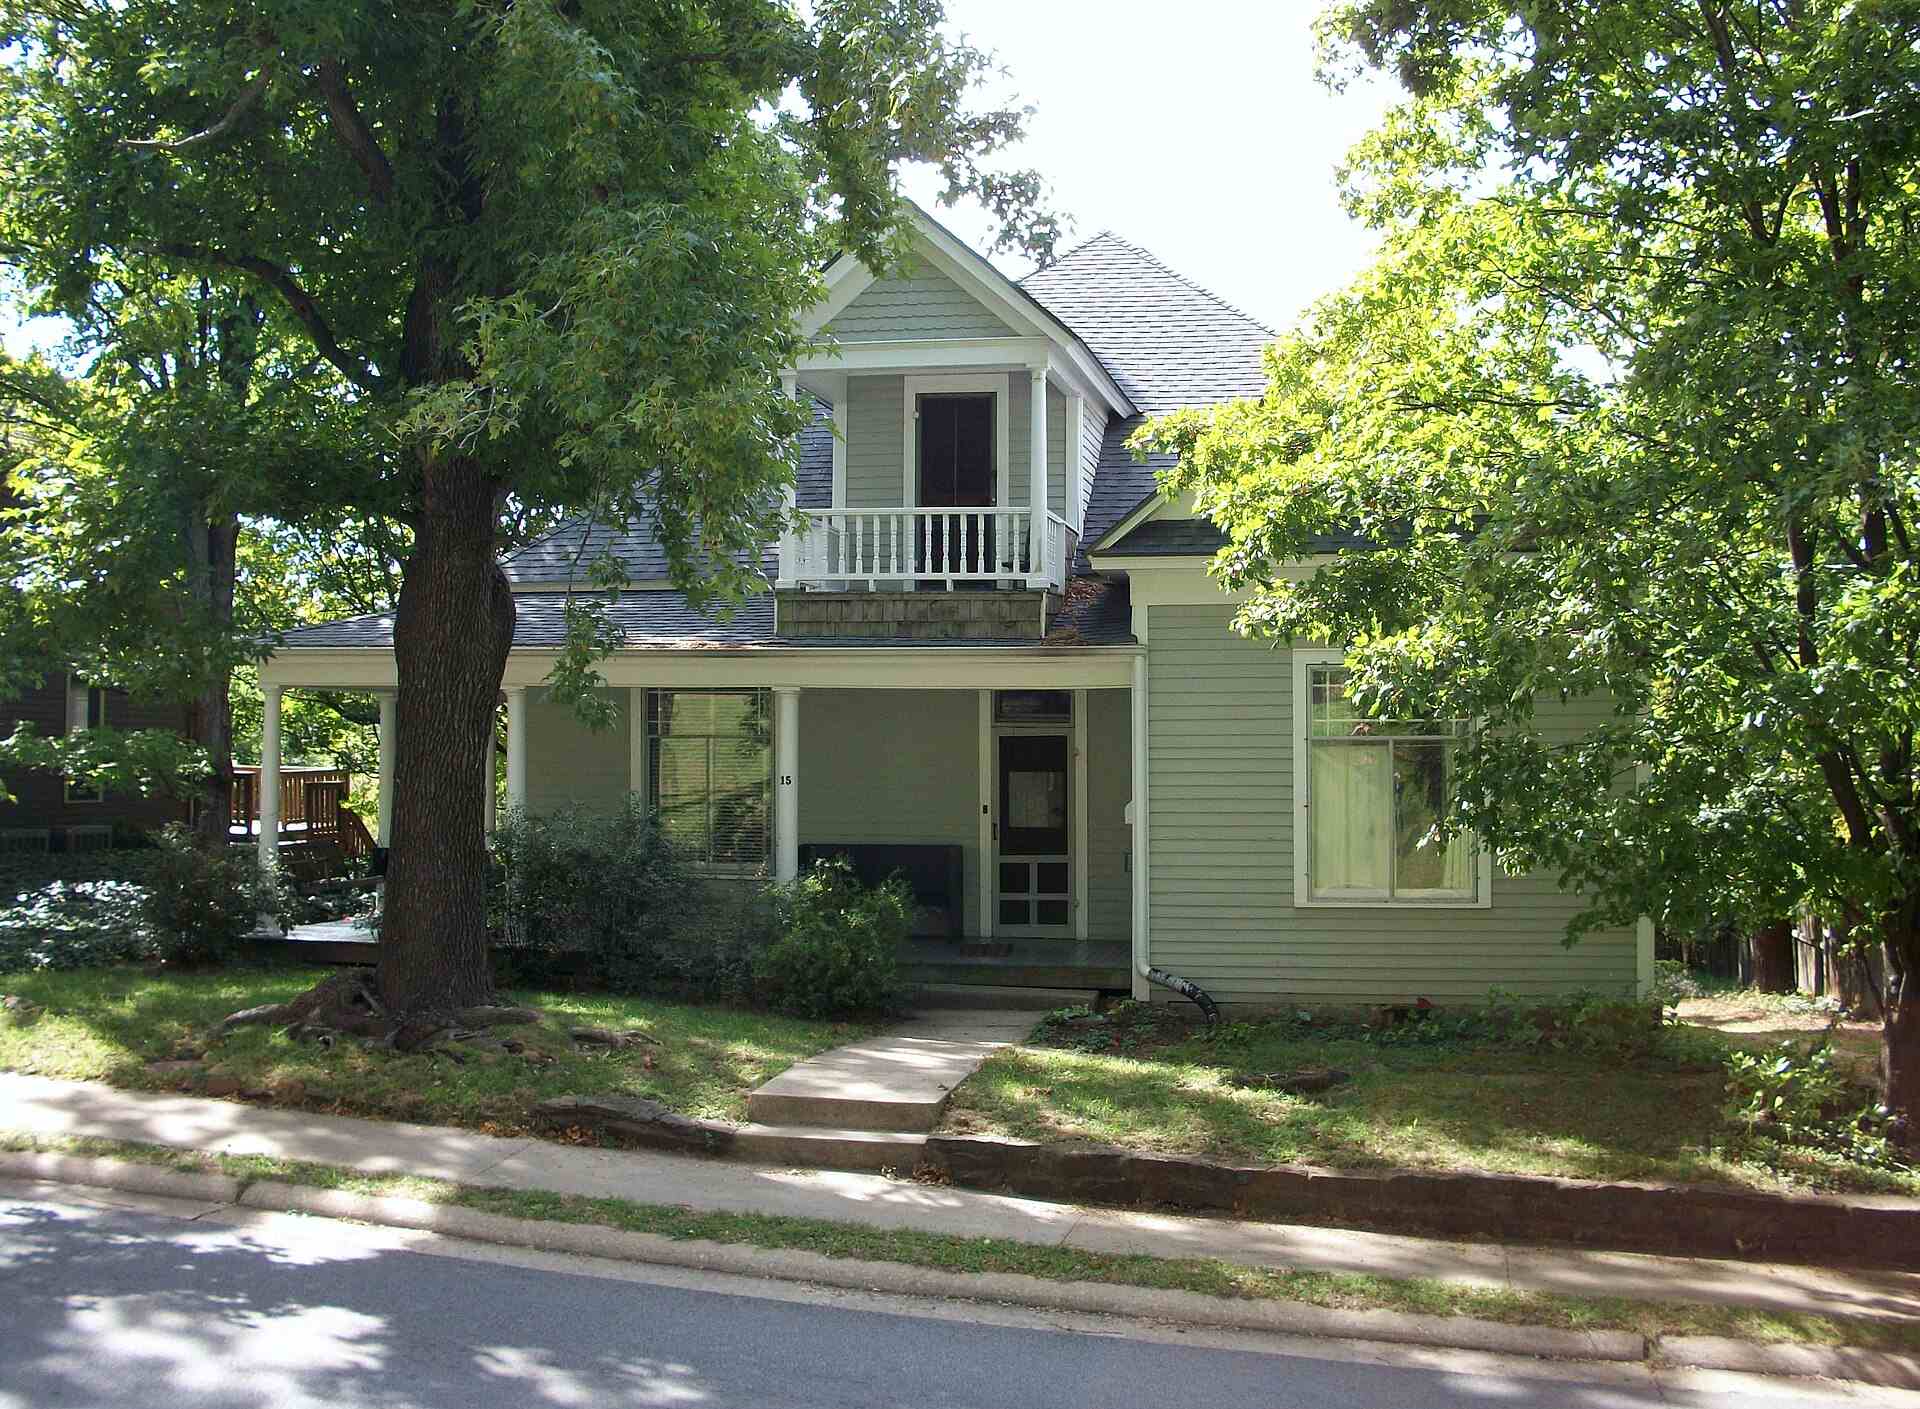
| Washington-Willow Historic District | Mid-19th- through mid-20th-century houses, extending into the 1960s: Queen Anne, Italianate, Classical Revival and bungalows. The inventory documents wood-frame and brick buildings, stone foundations or piers, and hip and gable roofs. | Evaluating a sale with deferred maintenance. For the individual house, investigate roof drainage, damp wood and moisture where masonry meets wood before committing to restoration. | An owner may choose a current-condition offer instead of managing moisture repairs and restoration. |
| Wilson Park Historic District | Early-20th-century housing; the nomination’s significance period is approximately 1900–1945. Craftsman, Queen Anne and Colonial Revival styles appear, along with asphalt roofing and concrete, brick or stone foundation materials. | Assessing a house before rehabilitation. Check drainage, exterior finishes and water entry; material descriptions alone do not identify the foundation system or current roof condition. | An owner may compare rehabilitation bids with selling before commissioning the work. |
| University Heights | Predominantly postwar Ranch houses, including low-pitched roofs and some architect-designed modernist homes. About half the buildings in the combined University Heights/Haskell Heights study area date to the 1950s and 1960s. | Comparing an as-is sale with paint-safe renovation. Older coatings and window friction dust warrant evaluation; appearance cannot establish whether lead is present. | An owner may prefer selling before undertaking an older-home renovation. |
These are conditional seller examples, not measured neighborhood defect rates or seller-motivation trends. The National Park Service moisture guide explains the older-building checks; EPA guidance explains age-related lead precautions.
The City’s housing assessment also links university enrollment growth with housing demand and describes affordability pressure and limited rental mobility. For a rental sale, gather the lease, occupancy details and maintenance history so you can compare keeping, improving or selling the property using its actual circumstances.
Local conditions that change the decision
Fayetteville Repair, Permit and Insurance Questions to Check First
Floodplain parcels and creek drainage
The City monitors Town Branch and Mud Creek. Creek overflow and storm runoff can inundate low areas and enter buildings. This is a localized floodplain exposure; a neighborhood name does not establish a house’s flood history.
Standing water, water entering during heavy rain or previous inundation damage call for an address-specific assessment. Fayetteville’s floodplain guidance explains separate flood insurance, permits and substantial-damage or improvement requirements that can trigger elevation or other current standards. Check the current City flood data and FEMA map before pricing restoration.
Persistent dampness in older wood floors
Where a house has a crawlspace, raised wood floor or roof leak, persistent moisture can let decay fungi break down cellulose and hemicellulose in joists and subfloors. Arkansas Extension documents musty odors, fungal growth, and darkened or shrinking wood with cube-like cracking as indicators.
This is a regional exposure mechanism, not a measured Fayetteville damage rate. Obtain an assessment of both the wood and moisture source. In a listing, an inspection finding may lead to a repair or credit negotiation; compare that scope with an as-is offer. Read our water-damage selling guide.
Older paint before a renovation
The documented postwar and historic housing makes construction date useful. In a pre-1978 house, deteriorating lead-bearing coatings or friction at old windows and doors can create contaminated dust. Peeling, chipping or chalking paint is a reason to evaluate, not a diagnosis; EPA recommends appropriate testing and precautions.
Include qualified paint-safe work in the repair-and-list comparison if it applies. Share existing reports when requesting an offer, and complete the applicable lead disclosures before contract signing.
Roof age and policy terms
Arkansas Insurance Department Bulletin 17-2023 permits separate wind/hail deductibles and, under its notice conditions, mandatory roof-schedule endorsements for roofs seven years or older. That can change a claim settlement and the owner’s repair budget.
Review the actual policy, roof age and damage report with your insurer before choosing repairs. The bulletin does not make every seven-year-old roof uninsurable. If you want to sell first, disclose known leaks and compare the current-condition offer with the full roof-work budget.
Additions, alterations and code notices
Fayetteville Building Safety reviews plans, permits and inspections for additions, alterations and repairs. Its office is at 125 W Mountain Street, Fayetteville, AR 72701; 479-575-8238. The Code Compliance Program sits within Building Safety in Development Services.
Gather notices and permit records before agreeing to a repair scope. Ask the relevant office about the specific work, and give those records to the buyer and closer. See our guide to selling with code issues.
Inspection records and service accounts
The state’s home-inspection framework covers accessible structural, roof, drainage, electrical and plumbing systems. For susceptible wood, Arkansas Extension identifies termite mud tubes, discarded wings and damaged wood as checks worth reporting.
For electric-service records, the City lists AEP/SWEPCO and Ozarks Electric, with service depending on location. Identify the provider by address and retain relevant account and repair records.
These checks help define the property’s condition. A finding can change repair allowances, insurance questions or a buyer’s decision after inspection; its effect depends on the actual property and contract.
Interactive planning tool
AS-IS Repair Cost Estimator
Use a broad repair range to compare listing preparation with a direct sale. Fayetteville’s floodplain requirements and older-house moisture or paint issues can change the scope substantially, so those specialist needs require separate bids.
Illustrative U.S.-dollar planning assumptions, not measured Fayetteville contractor prices. Square-foot rates cover interior finishes only. Select additional work only when it falls outside that scope to avoid double counting.
This is a broad planning estimate, not an inspection, appraisal, contractor quote, MHIC offer or guarantee. Actual costs vary with scope, materials, labor, permitting, access and concealed damage. Permits, structural repairs, extensive flood restoration, elevation work, lead-safe work and specialist remediation are excluded. These ranges are not automatic deductions from a cash offer.
Compare the amount you keep
Cash Sale vs. Traditional Listing in Fayetteville
A traditional sale may produce a higher gross price, but commissions, seller closing costs, repairs, concessions and ongoing holding expenses reduce the amount you ultimately keep. A direct cash sale generally prioritizes speed, certainty and convenience rather than the highest possible gross price.
If you need to sell a house fast in Fayetteville, Arkansas, build the comparison around your actual condition and deadline. The reported 38 days on market excludes the rest of the closing process, and a floodplain repair scope may require more than a cosmetic budget.
| Decision point | Traditional listing | Direct cash sale with MHIC |
|---|---|---|
| Gross Price | Potentially higher gross price | Usually lower than full retail value |
| Commissions | Agent commission may apply | No agent commission |
| Closing Costs | Seller closing costs may apply | MHIC pays normal closing costs |
| Property Condition | Repairs or buyer credits may be requested | Property sold as-is |
| Contingencies | Financing and appraisal contingencies | No buyer-financing contingency |
| Timeline | Longer and less predictable timeline | Seller selects an available closing date |
Compare Your Estimated Selling Options
Use our adjustable calculator to compare a traditional listing with a direct cash sale using your property’s estimated value and expenses.
Use the Net-Proceeds Calculator →The purchase agreement controls costs, inspections, title requirements and cancellation rights. Mortgage balances, taxes, liens and negotiated exceptions can reduce seller proceeds even when MHIC pays normal closing costs. Our cash-offer guide explains the pricing discussion.
Ownership, notices and payoffs
Probate, Foreclosure Deadlines, and Complicated Title Situations in Fayetteville
Inherited property: a small-estate filing can include real estate
Arkansas’s Affidavit for Collection of Small Estate by Distributee can permit qualifying collection and distribution without appointing a personal representative or obtaining an ordinary administration order. One or more entitled distributees file a sworn affidavit with the probate clerk; it is a court filing, not simply a private affidavit placed in land records.
- The adjusted estate value must be $100,000 or less, after encumbrances and excluding the decedent’s homestead and statutory spouse/minor-child allowances from that calculation. The affidavit still lists and values the real property, including the homestead.
- The official form requires more than 45 days after death; the supplied county procedure starts filing on day 46. No petition to appoint a personal representative may be pending or already granted.
- The affidavit identifies the persons entitled to the property and states that no unpaid claims or demands remain and that Arkansas DHS furnished no benefits or has been reimbursed as required. Exceeding the adjusted threshold makes the estate ineligible for this route.
- For an estate containing real property, publish notice within 30 days after filing and complete the applicable publication and deed-of-distribution steps. The Arkansas procedure in this county-hosted packet gives creditors three months from first publication to present verified claims. Mortgages and other enforceable liens are not erased by that claims bar.
Proper probate venue is ordinarily the decedent’s Arkansas county of residence; for a nonresident, ordinarily the county containing the greatest value of Arkansas property. The cited eligibility text sets no separate Arkansas domicile requirement for a distributee.
The Circuit Court of Washington County, Arkansas, Probate Division uses the Washington County Clerk as probate clerk. Probate filing office: Washington County Clerk, Washington County Courthouse, 280 N College Avenue, Suite 300, Fayetteville, AR 72701. Use the case’s hearing notice for its courtroom. An attorney and title examiner should confirm the authority and documents needed for a sale; the dollar threshold alone does not authorize someone to sell an inherited house. See our inherited-house selling guide.
A foreclosure notice needs a case-specific response
Arkansas allows both judicial and statutory nonjudicial foreclosure. A judicial case begins with a circuit-court lawsuit seeking a decree and commissioner’s sale. The statutory route uses an acknowledged Notice of Default and Intention to Sell recorded in the county land records.
- Statutory prerequisites include specified loan documents and holder information at least 10 days before initiation. After recording the notice, at least 60 days must pass before sale. Required recipients receive certified and first-class mail within 30 days of recording, including the property-loss warning.
- The specified modification/forbearance denial notice, when applicable, is sent by certified and first-class mail at least 10 business days before sale.
- Publication and posting rules include four consecutive weekly publications, the last no more than 10 days before sale, third-party courthouse posting and an Internet foreclosure-notice service.
These are statutory requirements, not a typical Washington County elapsed timeline or a new 60-day period after the first missed payment. For covered servicing, federal Regulation X generally bars the first notice or filing until delinquency exceeds 120 days, subject to its scope and exceptions.
Before the statutory sale, a qualifying accelerated default may be cured through reinstatement by paying amounts then due, actual enforcement expenses and applicable trustee/attorney fees, excluding principal due only because of acceleration. The process is discontinued, the loan reinstated and a cancellation recorded when the statutory requirements are met. Ask the servicer and your attorney for the actual amount and deadline.
A statutory auction occurs at the property or county courthouse front door, as designated in the notice, between 9 a.m. and 4 p.m. The courthouse is at 280 N College Avenue, Fayetteville, AR 72701. For a judicial sale, follow the decree and commissioner’s published notice. Confirm the exact place and terms instead of assuming one doorway or online portal handles every sale.
A completed statutory sale ends redemption rights, even before deed delivery or possession. Judicial redemption rights can be waived in the mortgage instruments; the Wells judicial opinion explains why the instruments, decree and confirmation matter.
A direct sale is one possible option if the owner has legal authority and enough time to complete closing and address the required payoffs before the scheduled sale. Requesting or accepting an offer does not postpone an auction. Our foreclosure selling guide can help organize questions for a qualified adviser.
Back taxes, heirship and recorded title issues
The Washington County Collector states that property taxes are due October 15 of the following year, with a 10% late-payment penalty and 10% annual interest on delinquent real estate taxes. Request the property’s current payoff from Collector Angela Wood’s office, 280 N College Avenue, Suite 202, Fayetteville, AR 72701; 479-444-1526. A personal-property late-assessment penalty is a separate charge.
The selected title company reviews ownership, heirship documents and recorded claims, then requests the releases or other documents needed for the transaction. Give it any code notices for separate municipal follow-up. Land records are maintained by the Washington County Circuit Clerk, acting as county recorder, at 280 N College Avenue, Suite 302, Fayetteville, AR 72701.
My House Into Cash provides a purchasing option, not legal, tax, probate, financial or foreclosure-defense advice. Ask the court clerk, Collector, an Arkansas real estate attorney or a tax professional about your circumstances. A purchase offer does not guarantee court approval, foreclosure prevention, lien removal, tax forgiveness or title clearance.
From agreement to seller proceeds
What Happens Between Accepting Your Cash Offer and Getting Paid in Fayetteville?
Fayetteville title and abstract companies coordinate examination, signing, escrow and recording; an attorney is not required for every closing. Lenders Title Company’s Fayetteville office, at 3761 Mall Avenue #1, Fayetteville, AR 72703, publishes these services and can be reached at 479-444-3333. It is a local provider option; select the settlement company for your transaction in the agreement.
The schedule below is an illustrative five-day sequence, not a promised closing time. Ownership, title, payoffs and signing requirements must be ready. Probate, unresolved claims or required notices can extend the schedule. Confirm the actual available date with the closer.
-
Day 0 · Agreement and contract
Put price, responsibilities and timing in writing
Finalize the purchase contract with no MHIC service fee or agent commission in a direct purchase. Record the as-is terms, normal closing costs MHIC will pay, review and cancellation provisions, occupancy, items left behind and the proposed closing date. Complete applicable disclosures before signing.
-
Days 1–2 · Title examination and property records
Check the chain of title and the actual work history
Under Arkansas title-insurance rules, the examination before a title report or policy covers at least the preceding 30 years. The examiner reviews Washington County deeds, mortgages, liens, plats, releases and other recorded interests, including ownership, judgments and easements. That minimum search period does not make older title defects irrelevant.
Where additions or alterations warrant it, review Building Safety records. Municipal condition due diligence is not automatically part of every title search.
-
Days 2–4 · Payoffs and title requirements
Turn balances and recorded claims into a settlement statement
The settlement agent requests mortgage payoffs, checks county real-estate taxes and works through the recorded obligations or authority questions identified by the examiner. Obtain dated figures that include applicable county penalties and interest. The closer calculates net seller proceeds after the required payoffs and agreed costs; a purchase price alone is not the take-home amount.
-
Day 5, if ready · Signing and recording
Execute the deed selected for this transaction
County records document warranty deeds; the contract and examiner determine whether a general warranty, special warranty or another conveyance is appropriate. Follow the deed’s signing-capacity requirements and the Recorder’s acknowledgment and notarization requirements.
Act 752 of 2025 adds identification requirements for deeds presented personally or by mail, with exceptions that include presentation by title-agency representatives and certain professionals. Have the closer confirm the applicable method and arrange recording with the Washington County Circuit Clerk.
-
After the closing requirements are satisfied · Payout
Receive the net proceeds shown on the final statement
The title company’s seller guide describes payment by wire or check after settlement payoffs and closing requirements are satisfied. Ask the closer when proceeds will be released for your file. Office signing is available; eligible documents may use remote online notarization after the closer approves the arrangement.
Lenders Title describes seller-paid owner’s title insurance and buyer-paid lender’s coverage as customary, with allocation negotiable. The MHIC cost agreement should state what it covers. When comparing cash buyers for houses in Fayetteville, Arkansas, request the same written cost allocation and net-proceeds explanation from each buyer.
Fayetteville and Northwest Arkansas
Explore Our 75-Mile Fayetteville Service Area
Ask about a property in Fayetteville or any of the 18 nearby markets below. Their 2026 Census representative points are within approximately 28 straight-line miles of Fayetteville’s reference point, comfortably inside a 75-mile radius. Send the street address to confirm property coverage; road distances differ.
See the Arkansas home-buying page for statewide information, or the residential ZIP guide below for these communities and additional surrounding postal areas.
75-mile radius reference
Fayetteville is the center of this 75-mile reference area.
Google Maps loads immediately and supports pan and zoom. The separate radius diagram uses straight-line distance from 36.071451, −94.166679, the Census city reference point. Selecting a community updates both views. This geographic guide does not guarantee eligibility for every property.
Terms that affect the next step
Fayetteville Real Estate & Legal Terms Homeowners Should Know
- Notice of Default and Intention to Sell
- Arkansas’s recorded statutory-foreclosure notice. Get the recording date and proposed sale details when asking about your remaining options.
- Affidavit for Collection of Small Estate by Distributee
- A qualifying probate-clerk filing for collection and distribution without appointing a personal representative. Real estate adds publication and deed steps; confirm the lawful transfer path before promising a closing date.
- 30-year title search
- The minimum continuous title-examination period before a title report or policy is issued. It sets a search minimum, not an expiration date for older defects.
- Special Flood Hazard Area (SFHA)
- A mapped flood-hazard area that can affect permits, separate flood insurance and restoration requirements. Use the City’s floodplain guidance when comparing repair bids with a sale.
- October 15 property-tax delinquency
- The county’s annual payment cutoff. Late penalties and real-estate interest can change the payoff deducted at settlement, so obtain the current parcel balance.
Direct answers for local sellers
Fayetteville Home-Selling Questions
Which residential ZIP codes do you cover in Fayetteville and surrounding communities?
Fayetteville’s main residential street-delivery ZIPs are 72701, 72703 and 72704. Postal names and municipal boundaries can overlap; Fayetteville mailing addresses also appear in shared 72730 and 72764 postal areas. The table covers Fayetteville and every nearby market named above.
| Community / postal area | Residential street-delivery ZIPs |
|---|---|
| Fayetteville | 72701, 72703, 72704; shared postal areas 72730, 72764 |
| Springdale | 72762, 72764 |
| Lowell | 72745 |
| Rogers | 72756, 72758 |
| Bentonville | 72712, 72713 |
| Bella Vista | 72714, 72715 |
| Centerton | 72719 |
| Tontitown | 72762; some addresses use 72704 |
| Farmington | 72730 |
| Prairie Grove | 72753 |
| Lincoln | 72744 |
| Greenland | 72701 for street addresses |
| West Fork | 72774 |
| Elkins | 72727 |
| Johnson | 72704; verify shared 72762 addresses individually |
| Siloam Springs | 72761 |
| Huntsville | 72740 |
| Pea Ridge | 72751 |
| Gravette | 72736 |
Additional surrounding residential postal areas include Canehill 72717; Cave Springs 72718; Combs 72721; Decatur 72722; Evansville 72729; Garfield 72732; Gentry and Springtown 72734; Hindsville 72738; Hiwasse 72739; Kingston 72742; Maysville 72747; Morrow 72749; Pettigrew 72752; Saint Paul 72760; Sulphur Springs 72768; Summers 72769; Wesley 72773; and Witter 72776. Little Flock shares 72756, and Bethel Heights postal addresses use 72764.
PO Box codes are separate: Fayetteville 72702, Springdale 72765/72766, Rogers 72757, Greenland 72737, Johnson 72741 and Tontitown 72770. Bentonville 72716 is a unique-use code. These should not be substituted for a home’s street-delivery ZIP.
Sources: City ZIP boundary data, the Arkansas ZIP classification directory, the Johnson ZIP boundary guide, and official address examples from Greenland, Johnson and Tontitown. Check the complete property address with USPS ZIP Code Lookup and ask us to confirm coverage. This is a guide to the named postal areas, not an inventory of every ZIP intersecting the 75-mile circle.
How do I sell my house for cash in Fayetteville, AR?
Share the address, known condition, ownership details and preferred date. Review the written offer, inspection and cancellation terms, costs and estimated net proceeds. If you accept, the selected title company examines title and coordinates payoffs, signing and recording before releasing proceeds.
Can I sell my house as-is in Fayetteville, AR?
Yes. MHIC can evaluate the home in its present condition, including repairs you do not want to complete. Put the condition and any items left behind in the agreement. Applicable disclosures still matter; most pre-1978 sales require federal lead information before the contract is signed.
How should I compare cash home buyers in Fayetteville, AR?
Compare the written price, legal buyer, property-review and cancellation rights, assignment terms, normal closing costs and the amount left after payoffs. Ask how any post-review price change would work. In Arkansas, the title-insurance examination includes at least 30 years of title-affecting matters, so confirm who will handle that work and the required releases.
Can an Arkansas small-estate affidavit include a Fayetteville house?
Yes, qualifying real property can be included, but the affidavit alone does not guarantee an immediately insurable sale. Eligibility includes an adjusted estate value of $100,000 or less and more than 45 days since death, together with the other statutory conditions. Real property adds publication and deed steps. Have an Arkansas probate attorney and the title examiner confirm authority before agreeing to a sale date.
Can I sell before a Washington County foreclosure auction?
Potentially, if you have authority to sell, enough time to close, and a workable plan for required payoffs. Arkansas has judicial and statutory nonjudicial routes, with different case documents. Read the actual sale notice and contact the servicer, trustee or commissioner and an Arkansas attorney promptly. An offer does not stop a scheduled sale.
Does a wet crawlspace mean my Fayetteville property is in a flood zone?
No. Moisture is a condition to investigate, not proof of a mapped flood zone. Check the current City flood layer and FEMA map for your parcel and have the water source evaluated. Fayetteville’s Town Branch and Mud Creek floodplain exposure is localized, while persistent moisture can damage susceptible wood wherever it occurs.
Do I receive the entire cash-offer amount at closing?
The offer is the purchase price. Net proceeds reflect mortgage payoffs, delinquent taxes, recorded obligations and any negotiated exceptions. MHIC pays normal closing costs under the agreement and charges no agent commission in a direct purchase. Ask the closer for an itemized settlement estimate before deciding.
Can I sell a rental or a house with unfinished permitted work?
We can evaluate an occupied property or unfinished work. Share leases, occupancy information, plans, permits, inspection results and code notices. Fayetteville Building Safety keeps relevant permitting and inspection information. Confirm access, remaining requirements and delivery terms in the contract.
Is a five-day cash closing guaranteed?
No. The five-day sequence above illustrates a straightforward file. Arkansas title examination, ownership authority, payoffs, required documents and signing arrangements determine when the property is ready. Confirm an available date in writing; an estate or unresolved recorded claim can need longer.
Request a Cash Offer for Your Fayetteville House
Share the address, known condition and the timing that works for you. If floodplain repairs, an inherited title question or a sale notice affects the property, include those details so the proposed terms and schedule address them.
Request Your No-Obligation Offer →Prefer to talk? Call (866) 651-6617.
Primary sources for your property
Official Fayetteville Homeowner Resources
Use the relevant office to confirm the record, notice or requirement for your own parcel.