
Sell My House Fast in Juneau, AK — We Buy Houses in Juneau, AK for Cash
“Can I sell my house fast in Juneau, AK?” Start today by calling with your address and known condition. We buy houses in Juneau, AK as-is for cash. Review the written offer, then choose an available closing date after title review.
An offer for the home you own today.
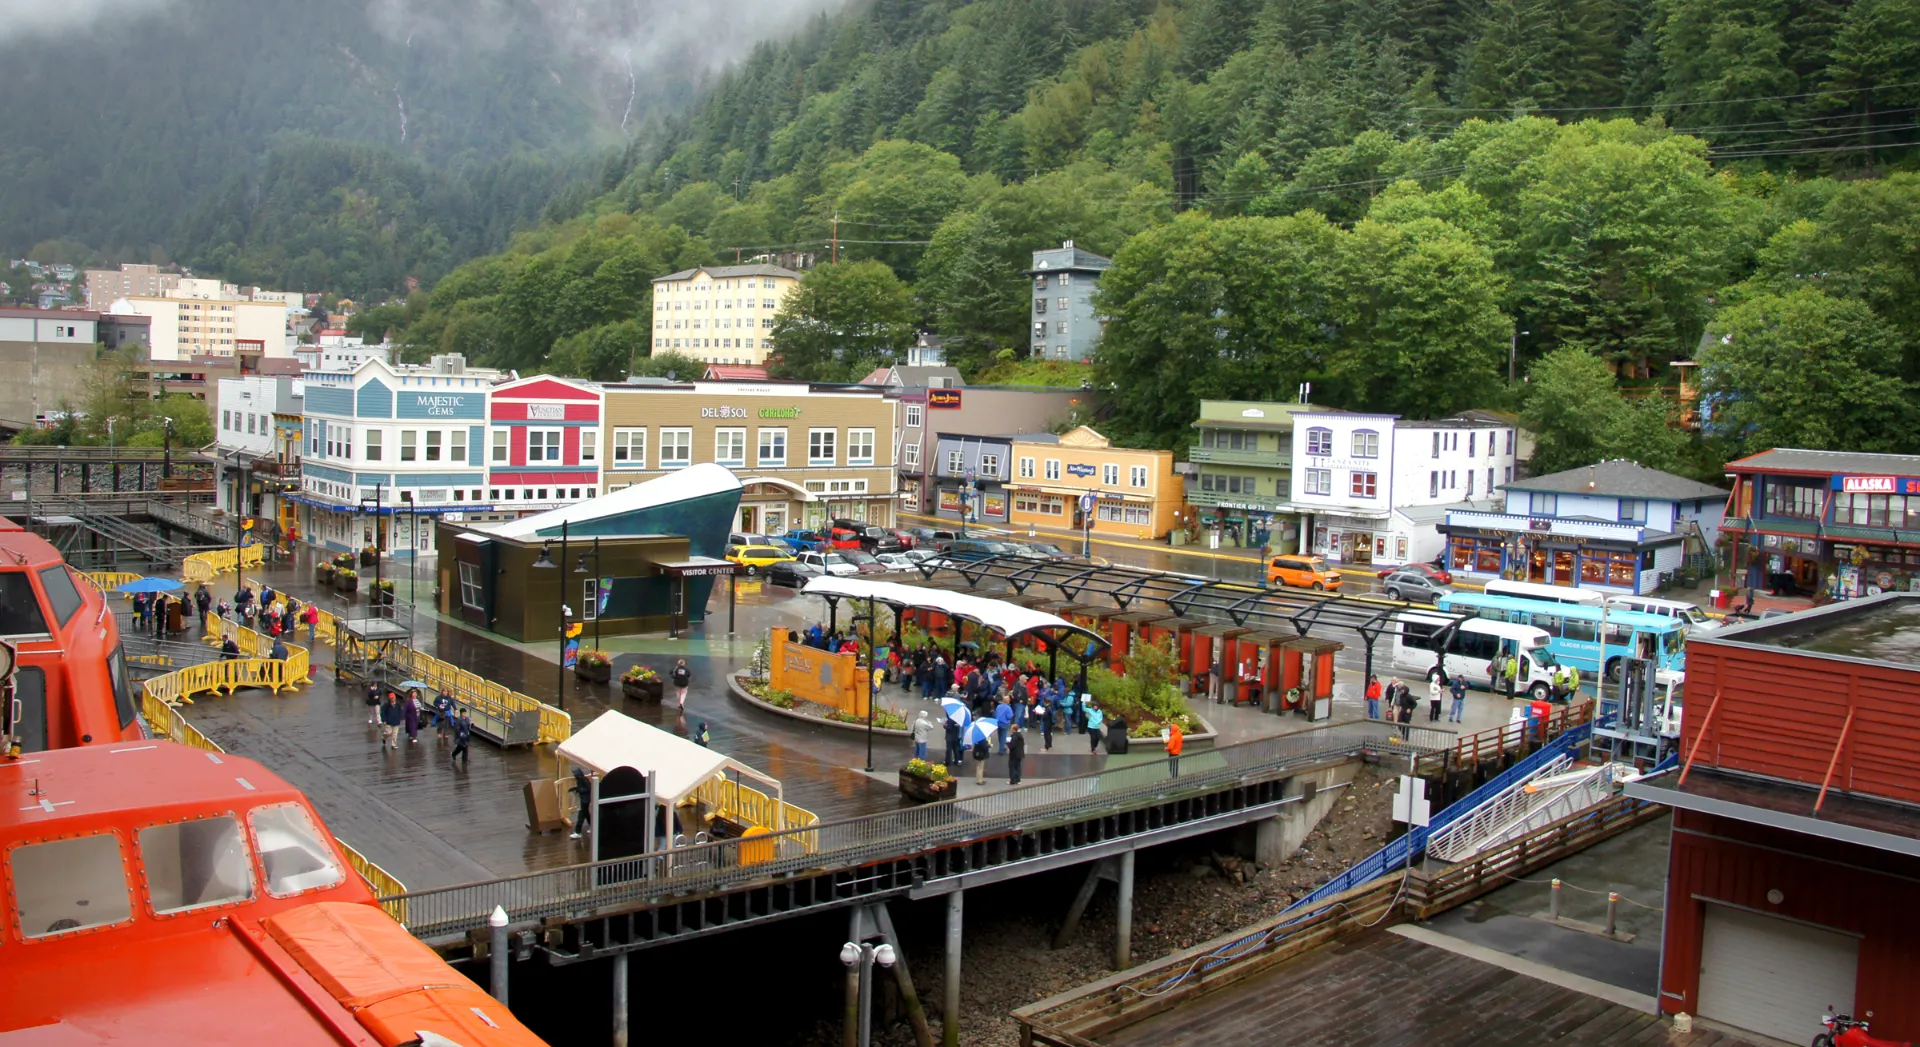
Call (866) 651-6617 →A downtown wood-frame house and a flood-affected Mendenhall River property call for different reviews. Tell us about the actual condition, any reports, and the timing you need so the offer reflects your property.
Juneau market watch
Compare the Market With Your Property’s Condition
Those citywide results can make a listing worth considering if your home is ready for retail buyers. They do not price an older house with concealed moisture or a parcel with flood damage. Compare a written as-is offer with realistic repair costs and your expected listing proceeds.
Source: Redfin’s Juneau housing-market report, data through September 30, 2026; accessed October 19, 2026. Its separate 32-day pending-time statement belongs to the 12-month competition section, not the 17-day three-month median. Some metrics have limited data; this snapshot is not a forecast.
Juneau’s July 2024 housing study also reported a 4% rental vacancy rate from the 2023 AHFC survey and a need for roughly 400 additional units to address overcrowding. Those are historical planning baselines, not 2026 vacancy figures. If you need another home after selling, check actual availability before agreeing to possession dates.
Current-condition purchase
Sell It Exactly as It Sits in Juneau
We buy houses in Juneau, AK in their current condition. Our direct purchase lets you compare an offer before organizing a renovation. The following is our as-is purchasing policy; include the agreed condition and any items left behind in the purchase contract.
- Don’t paint. Skip interior touch-ups and exterior repainting.
- Don’t replace flooring. Leave stained carpets, worn hardwoods, or cracked tile.
- Don’t fix the roof. We buy with active leaks, missing shingles, or aged roofs.
- Don’t stage the home. Avoid professional staging and pre-sale decluttering costs.
- Don’t clean it out. Take what you want; arrange in writing to leave unwanted furniture, trash, and clutter behind.
- Don’t schedule dozens of showings. Skip open houses and lockboxes; coordinate the access needed for our property review.
For an older downtown home, the Juneau Townsite survey documents late-19th- and early-20th-century wood-frame residences. Tell us about alterations and known water entry so we can assess the actual building. An as-is purchase is an agreement about condition, not a substitute for accurately sharing what you know.
Learn more in our as-is selling guide and cash-offer explanation.
Property-level context
Selling a House in Juneau’s Neighborhoods
The sources below describe specific local housing and hazards. Seller scenarios are examples to help compare options, not findings about why residents sell.
| Neighborhood / District | Housing Profile | Common Challenges We Resolve | Seller Scenario |
|---|---|---|---|
| Mendenhall Valley | Residential neighborhoods near the Mendenhall River; the source does not establish construction-era shares. | Flood inundation and riverbank damage at affected corridor parcels. Share the actual damage and mitigation records; exposure varies by site. | Illustrative: compare an as-is sale with organizing flood repairs or mitigation. |
| Downtown Juneau / Juneau Townsite | Late-19th- and early-20th-century wood-frame houses and apartments, including Queen Anne and Craftsman examples. | Review older building fabric and alterations individually. The historic survey gives no neighborhood-wide defect rate. | Illustrative: sell an inherited or older house before managing rehabilitation. |
| Douglas Townsite | Modest historic homes, with documented cohorts through 1917, 1918–1936, and 1937–1941, including rebuilding after fires. | Assess maintenance and past work at the property. Age and utilitarian construction do not prove rot or structural failure. | Illustrative: compare rehabilitation with a direct current-condition offer. |
What can change a sale plan
Juneau Property Conditions That Deserve a Closer Look
Mendenhall River flooding and bank scour
The National Weather Service’s local flood account documents glacial-lake outburst inundation and erosion. On erodible banks, scour can remove supporting ground; water can also wet building materials. This is a localized river-corridor or floodplain issue, not a finding about every Valley home.
Bank retreat, missing ground beside a structure, or water entering the home warrant specialist evaluation. These observations help identify a question; they do not diagnose structural safety. Bring prior reports and the parcel’s damage history to the sale discussion.
CBJ’s HESCO project updates include August 2026 barrier-damage mapping. A barrier is mitigation, not proof that a property cannot flood. Floodplain development permits and mapping can affect a repair plan; compare the documented scope with a current-condition offer.
Moisture inside wood-frame walls
CBJ’s historic-neighborhood records document local wood-frame houses. Southeast Alaska wall research makes drainage and drying relevant for wet framing, leakage paths, and assemblies that dry poorly, including inadequately detailed retrofits. It does not measure how many Juneau homes are defective.
Juneau test-wall work examined drying and simulated leaks: water retained in an enclosure can keep sheathing or framing damp. Climate alone did not make every test wall fail. Repeated condensation, stains, visible mold, or a persistent moldy odor are reasons to investigate, consistent with EPA moisture guidance.
Document the source and scope before choosing repairs or a price allowance. Painting over a stain does not answer where the water came from.
Financing and insurance questions
Under Fannie Mae property-condition guidance, damage affecting safety, soundness, or structural integrity can require investigation or repairs. Depending on severity and the appraisal, a financed buyer may request repairs, renegotiate, or decide not to proceed. Cosmetic wear alone does not automatically prevent conventional financing.
The Alaska Division of Insurance explains that standard homeowners and renters policies typically exclude flood damage. Separate private or NFIP flood coverage is needed and often has an advance waiting period. Check actual coverage rather than assuming a standard policy pays for flood repairs.
The state’s October 2021 insurance guide flags older homes, log or unusual construction, remote locations, and home businesses as potentially harder to place in broad coverage. These are not automatic denial rules; ask the insurer about the specific property.
Hillside hazards and permit records
For downtown hillside properties, CBJ’s avalanche and landslide assessment page says the 2022 avalanche maps were adopted in December 2023, the landslide maps were not adopted, and the 1987 maps were repealed. Evaluate the actual site rather than treating every published map as an adopted development rule.
For uncertain additions or unfinished work, ask the CBJ Building / Permit Center at 230 S. Franklin Street about the parcel’s records. Code Compliance handles violations. Review the actual file before deciding whether to complete work or sell as-is.
If you are thinking, “I want to sell my Juneau house as-is,” send the reports you already have. We can evaluate a direct purchase without requiring you to finish the repair project first. Safety concerns and engineering questions still deserve qualified advice.
Read the evidence carefully
What Juneau’s Housing Records Can Tell You
The July 2024 municipal housing study reproduces 2021 ACS estimates showing approximately 18% of homes built in the 1970s and 27% in the 1980s. Use those dated stock estimates to prompt questions about your home’s updates, not to infer a defect from its decade.
AHFC’s 2017 Juneau housing assessment modeled moderate indoor-air/moisture risk for 34% of occupied units and high risk for 15%. These are historical modeled risk estimates, not observed mold rates or inspection failures. For a sale, actual moisture findings and ventilation condition are more useful than applying a citywide percentage to your house.
A municipal inventory entry for the Martin/Stevens House documents a concrete foundation with a basement and a steeply pitched roof. A CBJ residential permit, BLD2004-00055 documents metal roofing installed over asphalt shingles. These establish local examples, not dominant citywide systems. Identify your own foundation, roof layers, and maintenance history before paying for a scope of work.
Interactive planning tool
AS-IS Repair Cost Estimator
Build a broad repair budget to compare with an as-is offer. This is not an inspection, appraisal, contractor quote, or guarantee. The rates below are illustrative planning assumptions in U.S. dollars, not measured Juneau contractor prices.
Finish rates cover selected-area paint, flooring, and other interior finish work only. Add a system below only if that work falls outside your interior scope. Each allowance applies once to the whole project, not per square foot.
Actual costs vary substantially with scope, materials, labor, permitting, access, and concealed damage. Engineering, permit fees, major flood remediation, structural support loss, and hillside work are excluded. Mendenhall bank repairs can require floodplain review and No-Rise analysis; obtain a separate professional scope rather than placing that work inside a small moisture allowance.
Compare proceeds and terms
Cash Sale vs. Traditional Listing in Juneau
A traditional sale may produce a higher gross price, but commissions, seller closing costs, repairs, concessions and ongoing holding expenses reduce the amount you ultimately keep. A direct cash sale generally prioritizes speed, certainty and convenience rather than the highest possible gross price.
| Decision point | Traditional listing | Direct cash sale with MHIC |
|---|---|---|
| Gross Price | Potentially higher gross price | Usually lower than full retail value |
| Commissions | Agent commission may apply | No agent commission |
| Closing Costs | Seller closing costs may apply | MHIC pays normal closing costs |
| Property Condition | Repairs or buyer credits may be requested | Property sold as-is |
| Contingencies | Financing and appraisal contingencies | No buyer-financing contingency |
| Timeline | Longer and less predictable timeline | Seller selects an available closing date |
Compare Your Estimated Selling Options
Use our adjustable calculator to compare a traditional listing with a direct cash sale using your property’s estimated value and expenses.
Use the Net-Proceeds Calculator →Use your actual CBJ tax bill in holding costs. The municipal tax explanation describes overlapping Areawide, Roaded Service, and Fire Service levies plus a debt-service levy; location matters. Deduct existing mortgage balances, tax payoffs, and recorded claims when comparing proceeds. Paying normal closing costs does not erase those seller obligations.
For a direct MHIC purchase, put cost allocation in writing. No buyer-financing contingency does not eliminate title review, agreed property review, or other written contract conditions.
Ownership and deadlines
Probate, Foreclosure Deadlines, and Complicated Title Situations in Juneau
Inherited property: Alaska’s affidavit does not transfer a house
The P-110 Affidavit for Collection of Personal Property of Decedent under AS 13.16.680 is available only after at least 30 days and within separate net ceilings: up to $100,000 in qualifying Alaska-registered vehicles and $50,000 in other personal property, after liens and encumbrances. These are not a $150,000 house-transfer allowance.
The Alaska Court System’s affidavit guidance excludes estate real property of any value. The route is for estates without real property remaining, including where qualifying ownership arrangements already transferred it automatically. An entitled successor, or someone acting for that successor, presents the sworn affidavit to the property holder; ordinarily no judge’s order or probate case is needed for qualifying personal property.
Estate real property, excess net assets, or a personal-representative application or appointment pending or granted in any jurisdiction prevent use of P-110. The form has no separate Alaska-domicile condition and counts the estate wherever located; it does not override another jurisdiction’s requirements. Being a creditor alone does not make someone an entitled successor.
A separate summary-administration route under AS 13.16.690–695 begins with probate and an appointed personal representative. Its ceiling depends on applicable allowances and specified administration, funeral, and final-illness expenses, not a universal house-value cap. The court’s small-estates guidance requires an inventory and a Sworn Statement of Personal Representative Closing Small Estate. An attorney should confirm the available route and authority to convey a house.
Juneau probate matters generally belong in Superior Court, under the court’s filing guidance. The Superior Court for the State of Alaska, First Judicial District at Juneau is at 123 4th Street, Juneau, Alaska, the physical courthouse address. Contact the court clerk for filing information and a real estate or probate attorney for legal advice. Our inherited-house guide explains the purchasing option.
Foreclosure: work from the actual recorded notice
Alaska permits judicial foreclosure and qualifying nonjudicial deed-of-trust foreclosure, as discussed in the bankruptcy court’s Macavilca decision. For the nonjudicial route, the initiating instrument is a recorded Notice of Default. Alaska’s Title 34 requires recording at least 30 days after default and at least 90 days before sale. Those statutory floors are not an observed total Juneau foreclosure duration.
Under the enacted notice and cure provisions, certified-mail copies go to statutory recipients within 10 days of recording; the permitted personal-delivery alternative for the property or occupants can use 20 days. The notice identifies the breach, amount owing, property, sale date, time, place, and cure conditions. Title 9 notice rules include posting in three public places at least 30 days before sale and newspaper publication weekly for four successive weeks; qualifying website publication starts at least 45 days before sale and continues through the fourth newspaper publication. Ask counsel to check the notices applicable to your case.
A payment default can generally be cured before the stated or postponed sale with arrears plus actually incurred foreclosure fees and costs, without paying unaccrued principal. After two earlier recorded-and-cured defaults under the same deed, the trustee may refuse another cure. For covered mortgages, Regulation X generally bars the first foreclosure notice or filing until more than 120 days delinquent, subject to exceptions and loss-mitigation protections. Federal rules or review can affect initiation and sale timing.
The default statutory auction venue is the front door of a Superior Court courthouse in the property’s judicial district unless the deed specifies another place. Juneau’s courthouse is at 123 4th Street; use the particular notice and any postponement to confirm the actual venue and time.
After a nonjudicial sale, there is no redemption right unless the deed expressly grants one. For judicial foreclosure, if not redeemed before confirmation, the judgment debtor may redeem within 12 months from the confirmation order under AS 09.35.250. Get case-specific advice rather than assuming the same rules apply to both routes.
An off-market sale is one possible option when you have legal authority to sell and enough time for an actual closing before the scheduled sale. An offer or signed contract does not by itself stop foreclosure. See our foreclosure selling guide and promptly discuss the actual deadline with your servicer and an attorney.
Back taxes, heirship, and recorded claims
CBJ Finance / Treasury’s property-tax rules set September 30 as the due date. For 2026, payment must be received by September 30; a postmark alone is insufficient. Unpaid tax receives a 5% penalty October 1 and an additional 10% March 1. Interest is 15% annually, applied monthly to unpaid tax. Obtain a current parcel payoff instead of calculating a settlement figure from the original bill.
The title professional reviews ownership, heirship documents, mortgages, and recorded claims using Alaska DNR’s records and the title report. If a Code Compliance matter exists, establish its actual status and whether any recorded claim requires a release. A violation is not, by itself, proof of a title lien. Heir disputes, missing releases, or insufficient proceeds can require legal work or creditor agreement and may prevent a scheduled closing.
Deeds and related instruments go to the State of Alaska DNR Recorder’s Office — Juneau Recording District, serviced by the Anchorage Office at 550 West 7th Avenue, Suite 108, Anchorage, AK 99501-3564. Use the state recording district rather than looking for a Juneau county recorder.
Purchasing services, not professional advice. My House Into Cash does not provide legal, tax, probate, financial, or foreclosure-defense advice. We cannot guarantee court approval, authority to sell, foreclosure prevention, lien removal, property-tax forgiveness, or title clearance. Consult the court clerk for procedure, CBJ tax staff for the account, and a qualified attorney or tax professional about your circumstances.
From contract to proceeds
What Happens Between Accepting Your Cash Offer and Getting Paid in Juneau?
Juneau providers document a title/escrow-led process: opening the order, obtaining payoffs and tax information, preparing settlement paperwork, overseeing signing, and arranging recording and disbursement. Alaska Escrow and Title’s closing guide explains that progression.
The days below are an illustrative fast-closing target, not a Juneau average or guaranteed five-day closing. Ownership, probate authority, payoffs, recordable documents, and funding must be ready. The closing agent confirms the actual schedule and when proceeds can be released.
Day 0: Mutual agreement and purchase contract
Put the price, current condition, items left behind, possession, property review, cancellation rights, and available closing date in writing. A direct MHIC purchase has no MHIC service fee or agent commission, and MHIC pays normal closing costs under the written agreement. Existing debts still affect net proceeds.
Local title-insurance guidance distinguishes owner’s and lender’s policies; the lender policy is commonly required with financing. Cost allocation belongs in the agreement, rather than assuming a mandatory Juneau seller-pays custom.
Days 1–2: Title search and parcel review
The selected title professional searches deeds, mortgages, assessments, liens, wills, and divorce records; reviews ownership and debts; and issues a commitment or preliminary report. Alaska Escrow and Title Insurance Agency, Inc. has a Juneau office and publishes these closing steps. It is an example of a local provider, not a claimed MHIC partner.
The agent can order tax information, loan payoffs, relevant association or maintenance information, and legal papers. DNR’s search portal provides document, historic-book, plat, and subdivision searches. Ask CBJ Building about uncertain permit records and Code Compliance about an actual violation file.
Days 2–4: Payoffs and title requirements
Review the report’s exceptions and obtain releases or other documents needed for closing. Confirm mortgages and the current CBJ tax payoff, including applicable penalties and interest. Unpaid property taxes follow the property; CBJ does not calculate the buyer/seller proration. The settlement allocation needs to be agreed and documented.
Heirship, probate authority, disputed claims, or missing releases can extend this stage. Ask the closing professional what remains unresolved before committing to a move. For electric-account arrangements, contact Alaska Electric Light & Power Company (AEL&P); do not treat an ordinary electric bill as a recorded title lien.
Day 5 target, if ready: Signing, recording, and disbursement
An Alaska statutory warranty deed under AS 34.15.030 is an available private-sale conveyance; the actual deed follows the contract and title review. Grantors sign with an acknowledgment or permitted statutory proof. An ordinary acknowledged deed does not require two subscribing witnesses. AS 34.15.010(b) calls for both spouses to join a family-home or homestead conveyance, with exceptions and curing provisions requiring individual review.
Follow DNR document requirements, including signed documents, generally original signatures unless another law permits a copy, and acknowledgment of conveyances. Local providers offer courtesy signings, notarization, and recording services; no single mandatory physical format is established here. Alaska notaries may request a thumbprint but are not required to collect one.
The closing agent arranges recording in the Juneau Recording District and pays the seller and other entitled parties under the settlement instructions. Confirm the proceeds method and release time with that agent before signing; neither immediate availability nor a universal Juneau payment instrument is assumed. Review the final statement for your actual net proceeds.
Southeast Alaska geography
Juneau and Nearby Communities
Start with your Juneau property address. For the wider region, Alaska DOT’s Northern Inside Passage information describes communities connected through marine and air travel. Hoonah, Gustavus, Tenakee Springs, Angoon, Pelican, and Haines are regional communities, not ordinary road-commuter suburbs. We confirm purchasing availability individually.
- Hoonah, AK
- Gustavus, AK
- Tenakee Springs, AK
- Angoon, AK
- Pelican, AK
- Haines, AK
| Community | Calculated straight-line miles | Associated ZIP |
|---|---|---|
| Hoonah | 39.6 | 99829 |
| Gustavus | 48.4 | 99826 |
| Tenakee Springs | 46.4 | 99841 |
| Angoon | 55.5 | 99820 |
| Pelican | 70.0 | 99832 |
| Haines | 74.2 | 99827 |
This interactive Google map is a regional overview centered on Juneau. The communities and distances are local references, not purchasing-area boundaries. The table uses the published approximate Juneau reference point, 58.30194, −134.41972. Distances are calculated great-circle miles from coordinates in Alaska DEC’s April 2013 community-location reference using a 3,958.7613-mile Earth radius. They are not road, flight-route, or ferry-route mileage. Haines calculates to about 74.2 miles, while DEC’s rounded narrative describes 80 air miles. Properties farther away are welcome for review; purchasing availability is confirmed for the individual property address.
For other Alaska locations, see our Alaska home-buying page. Postal designations do not establish legal location or purchasing availability; use the ZIP FAQ below and provide the physical property address.
Terms in local paperwork
Juneau Real Estate & Legal Terms Homeowners Should Know
- Glacial Lake Outburst Flood (GLOF)
- A sudden release from a glacier-dammed lake, including Suicide Basin, that can raise Mendenhall River levels. A seller should distinguish actual parcel damage from general regional exposure. Read the source ↗
- HESCO flood barrier
- A temporary flood-protection barrier used along the Mendenhall River. Its presence is mitigation, not proof that an individual property cannot flood; CBJ publishes damage and reconstruction updates. Read the source ↗
- Juneau Recording District
- The state land-record jurisdiction used for Juneau deeds, deeds of trust, and related instruments; its records are administered through Alaska DNR, currently serviced by the Anchorage recording office. Read the source ↗
- Affidavit for Collection of Personal Property of Decedent
- Alaska's P-110 successor affidavit for qualifying personal property after 30 days. It cannot transfer a house remaining in the probate estate. Read the source ↗
- Areawide, Roaded Service, and Fire Service mill levies
- Overlapping CBJ property-tax components that depend on parcel location. A separate debt-service levy also applies; use the actual parcel's tax bill when estimating holding costs. Read the source ↗
- No-Rise Certification
- A qualified engineer's floodway analysis showing proposed work will not raise flood levels. CBJ requires it for specified Mendenhall bank-stabilization permitting, which can affect an owner's repair plan. Read the source ↗
Practical seller questions
Juneau Home-Selling FAQs
Which residential ZIP codes are covered in Juneau and nearby communities?
For Juneau and Douglas homes, provide the physical property address in 99801 or 99824. For nearby Southeast Alaska communities, use the residential property’s location and the associated community ZIP below. A postal code is not a promise that every property in that area is served.
| Residential area / community | ZIP code | What to provide |
|---|---|---|
| Juneau street addresses, including Auke Bay street addresses | 99801 | The full street address and known condition; ZIP alone does not establish flood exposure. |
| Douglas | 99824 | The physical property address and relevant reports. |
| Hoonah | 99829 | Confirm the property location, access, and purchasing availability. |
| Gustavus | 99826 | Confirm the property location, access, and purchasing availability. |
| Tenakee Springs | 99841 | Confirm the property location, access, and purchasing availability. |
| Angoon | 99820 | Confirm the property location, access, and purchasing availability. |
| Pelican | 99832 | Confirm the property location, access, and purchasing availability. |
| Haines | 99827 | Provide the physical property address, access information, and known condition so we can review the property. |
| Other nearby residential community: Elfin Cove | 99825 | Ask about the actual property; this reference does not establish a confirmed purchasing market. |
If you receive mail at a PO Box or use a separate mailing address, send the house’s physical location. Mailing-only and government ZIP codes are not listed as additional residential neighborhoods. If your property uses another Southeast Alaska designation, ask us to review its exact location.
Check the complete physical mailing address with USPS ZIP Code Lookup. USPS lists the Auke Bay Post Office’s street address in 99801. The Juneau ZIP directory distinguishes standard delivery from mailing-only classifications; nearby community postal usage also appears in Alaska’s historical address appendix. These sources identify postal usage, not MHIC coverage.
How do I sell my house for cash in Juneau?
Call (866) 651-6617 or use our contact form with the property address, known condition, and preferred timing. Review the written offer and estimated proceeds. If you accept, the closing professional checks ownership, payoffs, and recording requirements before arranging payout.
How fast can a Juneau cash sale close?
Timing depends on the actual title, signing authority, payoffs, and funding. The illustrative schedule above targets day five only if everything is ready; it is not a guarantee or a verified Juneau average. An estate house, missing release, or pending foreclosure deadline can need additional work. The local closing guide describes the necessary settlement steps.
Can I sell a flood-damaged Mendenhall Valley house as-is?
You can request an offer on the property in its current condition. Provide the actual water and erosion history, repair reports, and available mitigation records. CBJ’s HESCO updates document localized recovery work; they do not show every Valley parcel has the same exposure. Engineering and title questions still need appropriate review.
Does a cash sale require a roof replacement or cleanout?
MHIC’s as-is policy lets you request an offer without replacing the roof, staging, or completing a cleanout. Agree in writing on any furniture, trash, or clutter that will remain, and coordinate access for our condition review. Share known leaks and reports so both parties understand the property being sold.
Can Alaska’s small-estate affidavit transfer an inherited Juneau house?
No. The P-110 affidavit route collects qualifying personal property and cannot convey real estate remaining in the estate. Its separate $100,000 vehicle and $50,000 other-personal-property ceilings are not house-value allowances. Ask an attorney to establish the lawful title route and signer’s authority.
Can a sale stop a scheduled Juneau foreclosure?
A completed sale may be one option if the owner has authority and enough time to satisfy closing requirements before the scheduled auction. An offer alone does not stop foreclosure. Check the actual notice, postponements, cure rights, and applicable federal servicing protections with your servicer and an attorney; no foreclosure prevention is guaranteed.
What if my Juneau property taxes are overdue?
Ask CBJ Finance / Treasury for a current payoff. For 2026, the rules require receipt by September 30, then apply a 5% penalty October 1 and another 10% March 1, with 15% annual interest applied monthly to unpaid tax. A closing may use proceeds toward a verified payoff when the transaction permits; selling does not forgive the balance.
How should I compare cash home buyers in Juneau?
Compare the actual written price, proof of funds, inspection and cancellation terms, cost allocation, available date, and expected net proceeds. Ask what could change before closing. Check our cash-buyer verification guide. A lower cash price can make sense for convenience, while a market-ready house may merit a listing comparison.
Are cash buyers for houses in Juneau required to use a particular title company?
The material here documents local title and escrow services, not a mandatory company or a verified exclusive MHIC partnership. Confirm the settlement provider in the agreement. Alaska Escrow and Title’s guide explains title orders, payoffs, paperwork, recording, and disbursement.
Will an old or damp Juneau house automatically fail financing or insurance?
No universal age or dampness cutoff is established here. Fannie Mae guidance focuses on condition affecting safety, soundness, or structural integrity. The Alaska Division of Insurance separately explains flood exclusions in standard policies. Use property-specific reports and an insurer’s actual terms.
Can you evaluate a rental or a home outside Juneau’s road system?
Ask with the physical address, occupancy information, known condition, and access arrangements. Regional marine and air access makes an address review important; the map is a regional overview, not a promise of purchasing coverage. If your goal is to sell house fast in Juneau, Alaska, an early title and access review helps establish a workable date.
Start with the actual property
Request Your Juneau Cash Offer
Share the physical address, known condition, and timing you would like to explore. Include flood, moisture, title, or probate documents you already have. We will explain the written purchase terms so you can compare a cash offer with repairing and listing.
Or call (866) 651-6617. Read how our buying process works before deciding.
Primary homeowner references
Official Juneau Homeowner Resources
Use the office and record that match your question. Court procedure, tax balances, permit status, and the actual title report can change the available sale options.